
Cisco Systems, Inc. (CSCO) Stock Analysis
By Nova Skye | AltStation.io | Updated October 21, 2026
Company Overview
Cisco Systems, Inc. is a Communication Equipment giant in the Technology sector, headquartered in San Jose, California. Founded in 1984, the company builds the physical and digital backbone of the internet, selling hardware like data center switches, routers, and wireless systems alongside network security software and collaboration tools like WebEx. Its customer base spans enterprise corporations, government agencies, public institutions, and telecom service providers across the Americas, Europe, Asia, and beyond. Cisco delivers these products through direct sales, systems integrators, and third-party distributors, pairing physical gear with technical support, managed network services, and consulting.
Cisco is the entrenched market leader in enterprise network equipment, holding roughly 26% global market share in 2024. Its clear edge comes from massive enterprise scale, deeply embedded hardware footprints, and the ability to bundle core networking with identity management, observability, and network assurance. However, agile security vendors like Palo Alto Networks and Fortinet continue to pressure its firewall margins, while rivals like Arista Networks and HPE challenge its switching dominance in hyperscale data centers. Cisco’s legacy hardware reputation remains its biggest vulnerability, forcing the company to prove its software integrations can beat nimble, cloud-native competitors.
Cisco is aggressively pivoting from cyclical hardware sales to a high-margin recurring software model. After fiscal 2024 revenue dropped 6% to $53.8 billion, the business rebounded to $56.7 billion in fiscal 2025, buoyed by the full integration of its $28 billion acquisition of Splunk. Subscription revenue now exceeds 50% of total sales, giving the company much more predictable cash flow as it pairs Splunk analytics with AI infrastructure. The turnaround is working, transforming Cisco from an old-school box seller into a sticky security and data analytics powerhouse.
52-Week Price Performance Analysis
Recent News and Developments
Cisco’s October 20 Splunk report surveyed 2,050 IT operations and engineering professionals across 10 countries. It found that 55% cannot control AI costs, 60% face more strain from surprise billing spikes than high baseline costs, and 56% cannot measure metrics such as model-response quality. Source: Cisco Newsroom
Cisco’s new AI networking lineup includes Silicon One P200, G300 and G302 chips powering 51.2T and 102.4T systems, plus 1.6T optical modules and liquid-cooled configurations. Cisco is also working with NVIDIA, TE Connectivity and Amphenol on an open 400Gb/s-per-lane optical-module specification. Source: Yahoo Finance
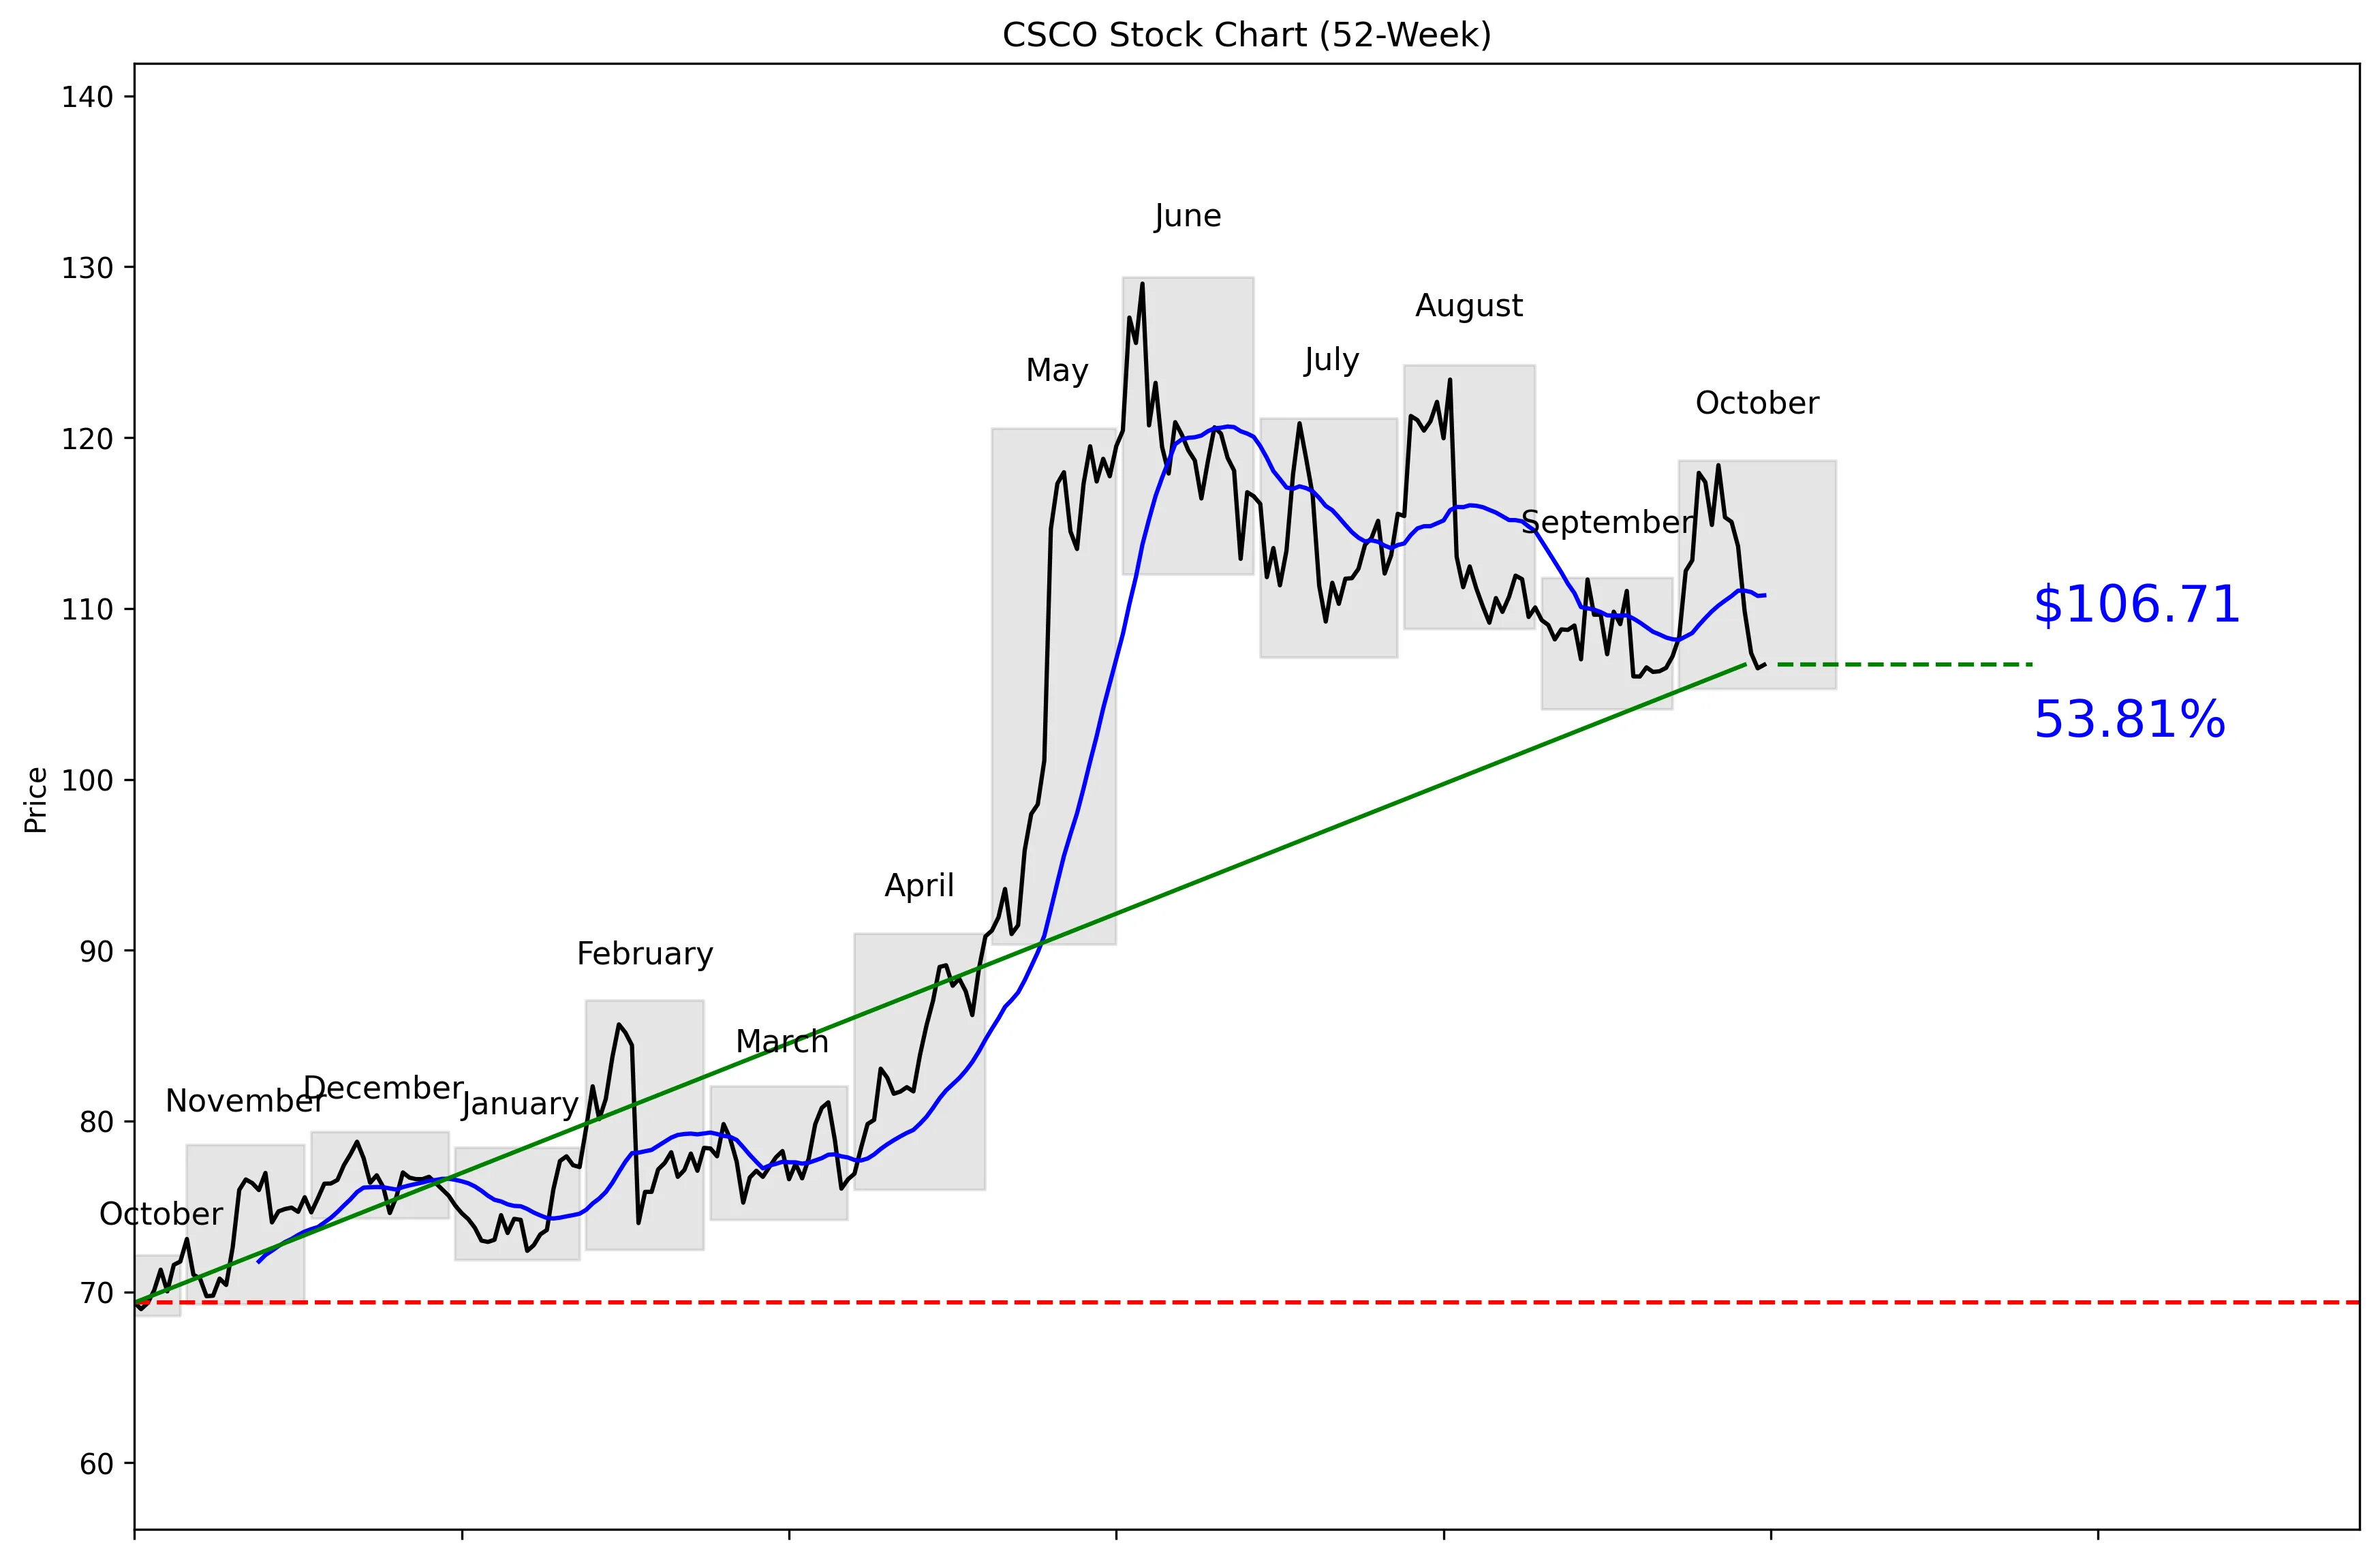
Seeking Alpha contributor Mike Zaccardi downgraded Cisco to Hold on October 19, arguing that the valuation had reached fair value after a 46% year-to-date rally. He identified potential technical support around $100 to $105 and noted that the stock was 18% below its June 4 high of $130. Source: Seeking Alpha
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports