ALTSTATION.IO

Enphase Energy, Inc. (ENPH) Stock Analysis

By Nova Skye | AltStation.io | Updated September 07, 2026

Price
$36.23
Change
-0.22%
Market Cap
$4.79B
Avg Volume
5.4M

Company Overview

Enphase Energy is a solar technology company headquartered in Fremont, California that makes complete home energy systems. Their core product is the semiconductor-based microinverter, which converts power at the individual solar panel level rather than through a single central box. Beyond microinverters, they sell home energy storage through their IQ Battery line, EV chargers, and cloud-based monitoring software. They sell these products directly to large solar installers, distributors, original equipment manufacturers, and retail homeowners.

Enphase is the dominant market leader in residential microinverters, holding roughly 70% to 75% of global microinverter revenue and an estimated 70% of the North American residential market. Their primary competitive edge is an integrated hardware and software ecosystem that commands premium pricing, consistently delivering non-GAAP gross margins between 46% and 49%. The real threat to their position comes from budget-focused challengers like APsystems and Hoymiles, alongside broader residential inverter competition from SolarEdge. While lower-cost alternatives are chipping away at price-sensitive buyers, installers still pay up for Enphase reliability and safety.

Enphase is currently managing a cyclical demand slowdown after generating $1.47 billion in revenue in 2025, an 11% increase over $1.33 billion in 2024. Softer U.S. residential solar demand entering 2026 prompted management to execute a restructuring plan that cut roughly 6% of the workforce. Strategically, the company is defending its margins by scaling domestic production at manufacturing facilities in Texas and South Carolina to capture federal manufacturing tax credits. Enphase holds strong gross margins and a resilient balance sheet, but top-line growth will stay muted until residential solar demand stabilizes.

Key Financials
Market Cap
$4.79B
Revenue
$1.33B
EBITDA
$191.79M
Gross Margin
30.0%
Profit Margin
10.1%
Revenue Growth
-19.6%
Total Cash
$937.71M
Total Debt
$613.36M
Free Cash Flow
$78.32M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
35.17
Forward P/E
15.93
Beta
1.65
52-Week High
$73.74
52-Week Low
$25.78
EPS
$1.03
50-Day Avg
$40.58
200-Day Avg
$40.70
Price/Book
4.05
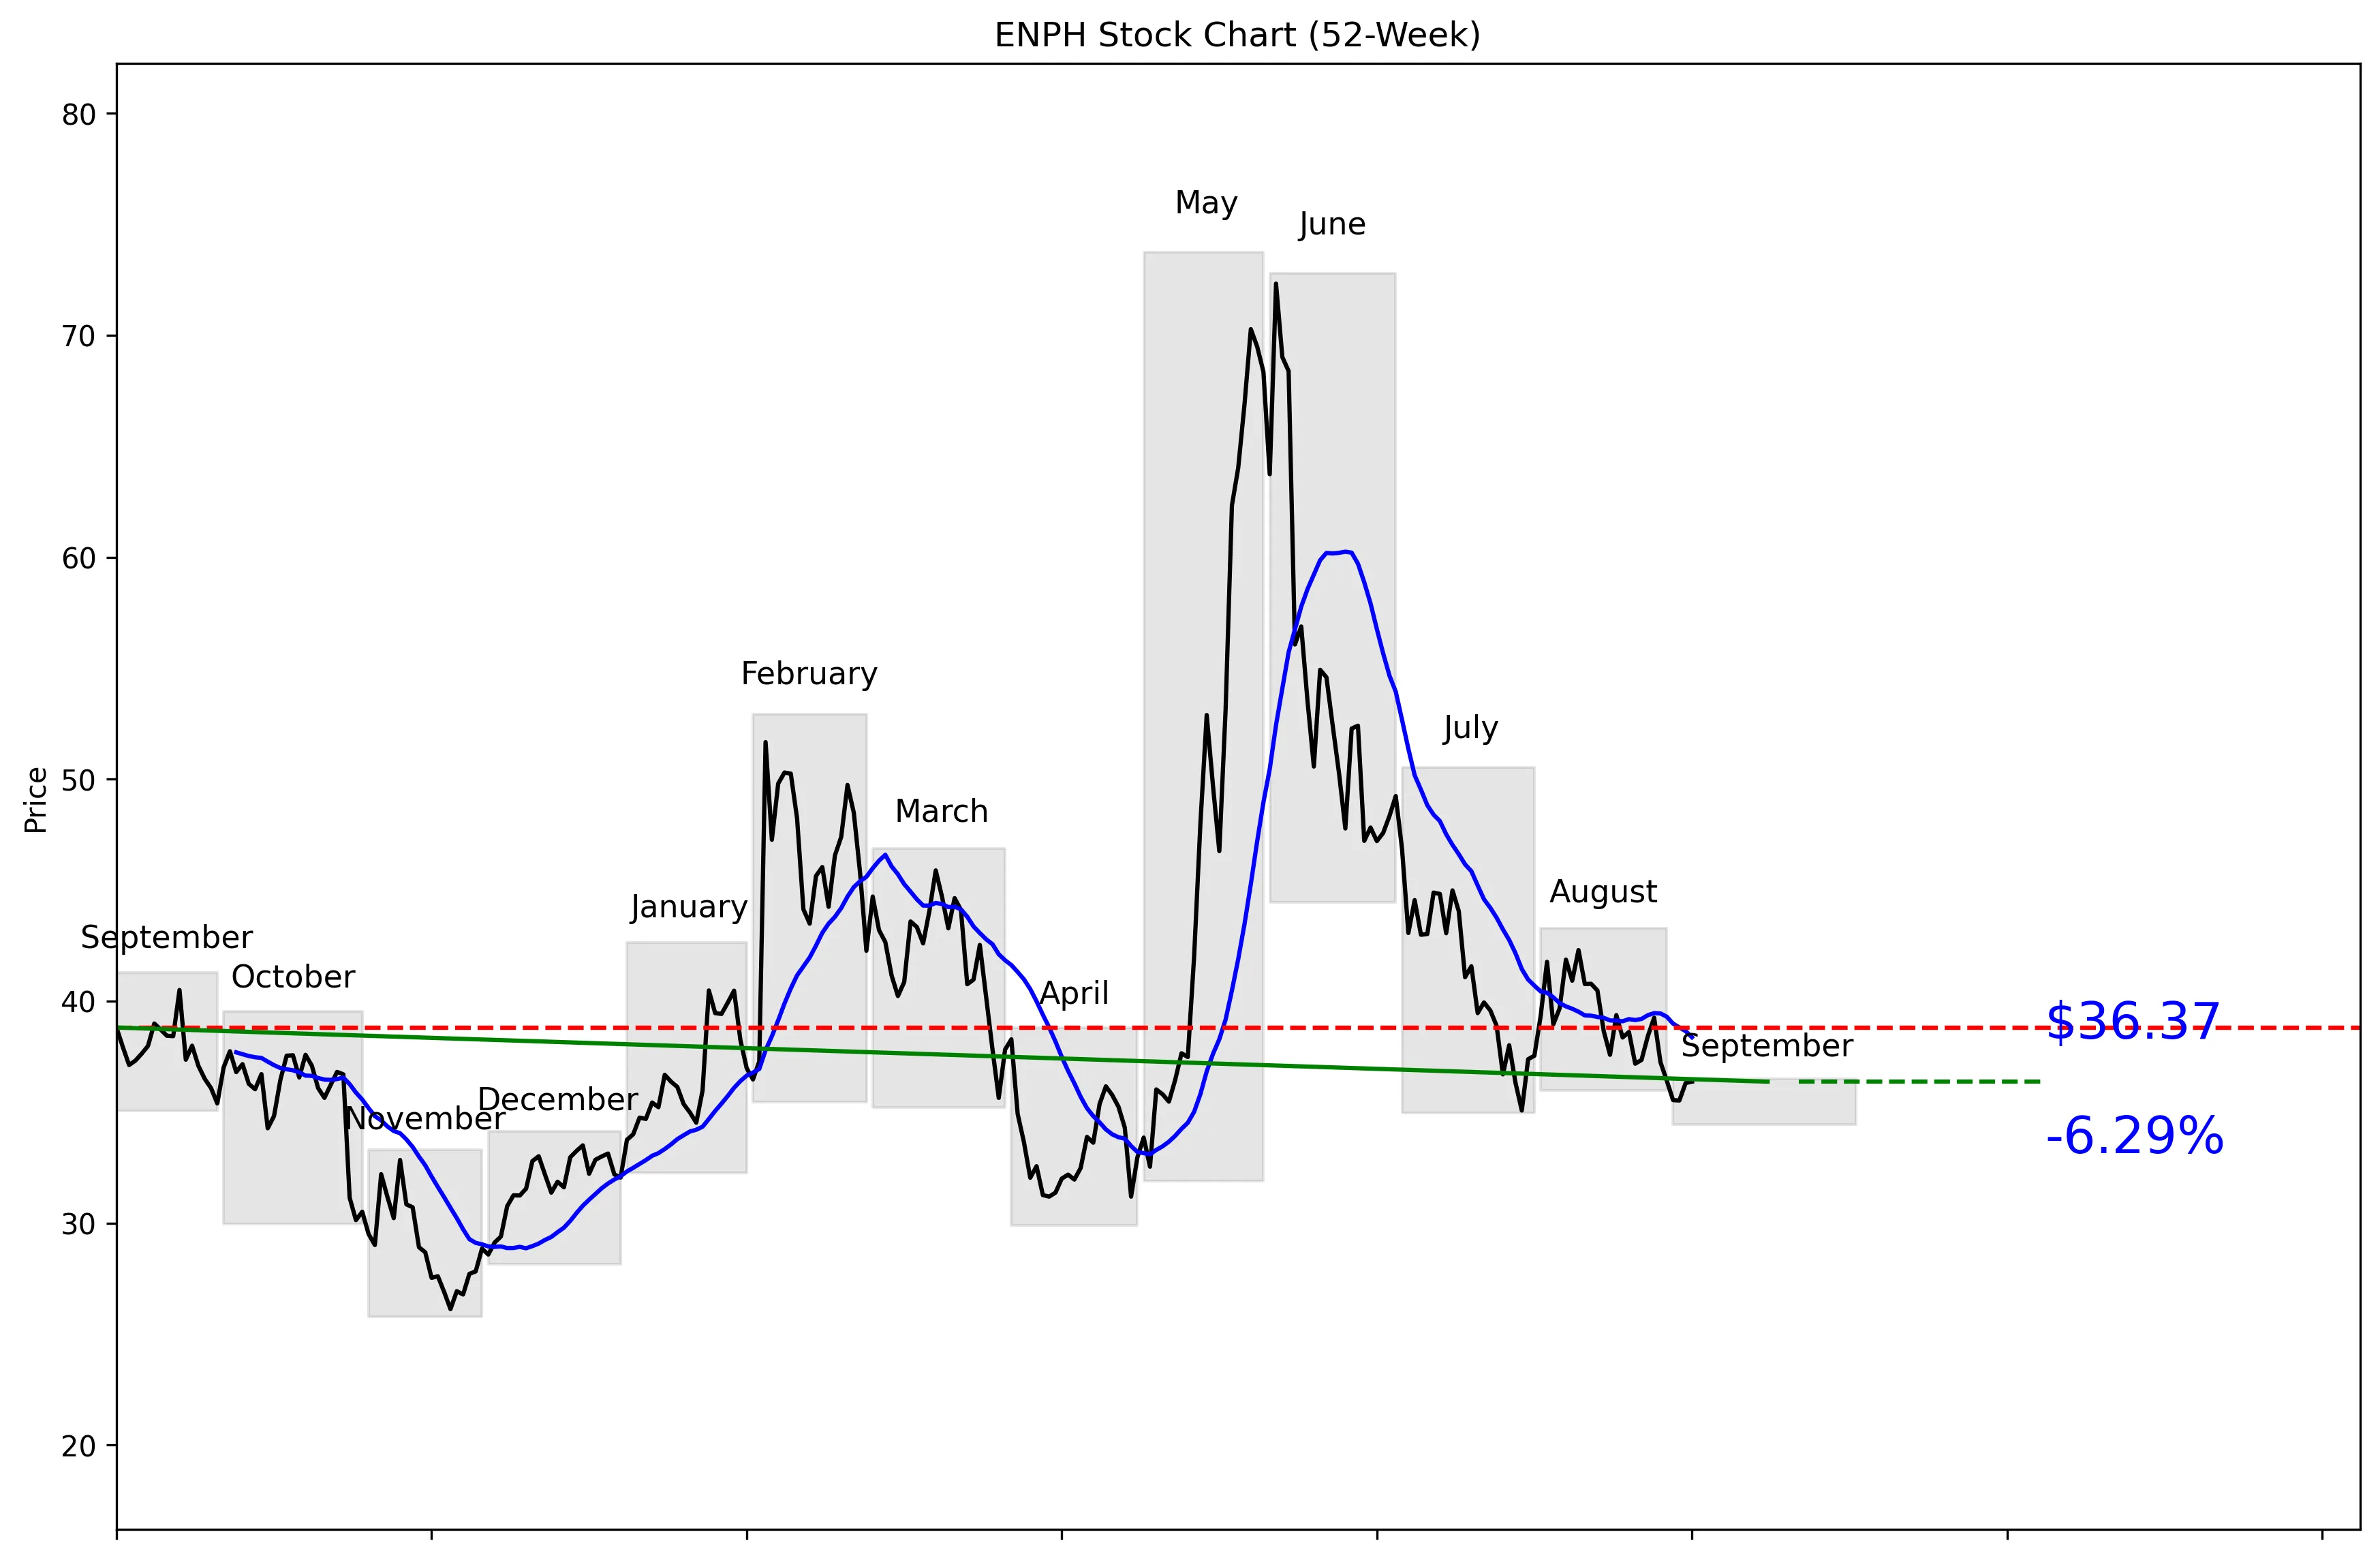
ENPH 52-Week Stock Chart
Technical Analysis
ENPH trades at $36.23, 50.68% below its 52-week high of $73.74 and 41.08% above its $25.78 low. The stock sits just 22% of the way from the bottom of its 52-week range, confirming that the broader trend remains weak. Price is 5.22% below the 20-day moving average of $38.37, while momentum is negative at 2.36% over five trading days and 13.14% over 20 trading days. Near-term support is $35.07, only $1.16 below the current price. Resistance sits at $42.30, and reclaiming that level would be the first meaningful technical improvement.


Recent News and Developments

Enphase expands smart EV charging across Europe

Enphase expanded IQ EV Charger 2 metering compatibility on September 3, enabling dynamic load balancing and surplus-solar charging in homes with Enphase systems, third-party solar, or no solar. Supported integrations include Linky in France, P1/DSMR in the Netherlands, Belgium and Luxembourg, and HAN connections in Norway. Source: Enphase Energy

Enphase Care enrollment tops 7,500 homeowners

Enphase said more than 7,500 U.S. homeowners have enrolled in its premium support program, which is available in all 50 states. The company said enrollment is running above 10,000 homeowners annually, creating a recurring service opportunity beyond the initial hardware sale. Source: GlobeNewswire

ENPH ends the week at $36.37 after volatile trading

ENPH closed at $36.37 on September 4, down 0.14% from its August 31 close of $36.42. Shares fell to a weekly intraday low of $34.45 on September 2 before gaining 2.22% on September 3 and another 0.17% on September 4. Source: Enphase Energy


Market Sentiment and Analyst Recommendations

Bull Case
Enphase has $937.71 million in cash against $613.36 million in debt, leaving cash $324.35 million above debt. That balance-sheet position gives the company room to manage weak demand while investing in additional products and services. The IQ EV Charger 2 expansion announced September 3 extends smart charging compatibility across France, the Netherlands, Belgium, Luxembourg, and Norway. Enphase Care has enrolled more than 7,500 U.S. homeowners and is running above 10,000 enrollments annually, creating a recurring service opportunity beyond hardware sales. Analysts rate ENPH a buy, with 26 analysts setting an average target of $47.13 versus the current $36.23 price. The bull case is straightforward: the stock is heavily discounted from its $73.74 high, the balance sheet is solid, and the average analyst target offers meaningful upside if revenue stabilizes.
Bear Case
Revenue is shrinking 19.6%, which is the biggest problem in the thesis. A P/E ratio of 35.17 is expensive for a company with declining revenue. The stock remains 50.68% below its 52-week high and trades 5.22% under its 20-day moving average, so investors are not yet rewarding the product expansion story. Twenty-day momentum is negative 13.14%, showing that recent selling pressure extends beyond a single weak session. The $613.36 million debt load is manageable relative to $937.71 million in cash, but it still reduces financial flexibility. ENPH needs stronger operating results to justify its valuation; new charging integrations and service enrollments are promising, but the supplied data does not show that they have reversed the revenue decline.
What to Watch
The first threshold is $35.07 support; a break below it would reinforce the negative 20-day momentum trend. On the upside, ENPH must first recover its $38.37 moving average and then challenge $42.30 resistance. Investors should track whether revenue growth improves from the current negative 19.6% rate during the next quarter. Enphase Care enrollment is another key metric after the company reported more than 7,500 homeowners and an annual enrollment pace above 10,000 on September 1. Watch adoption following the September 3 expansion of IQ EV Charger 2 compatibility across five listed European markets. The bullish thesis strengthens if revenue stabilizes and price clears $42.30; it weakens if revenue contraction continues and the stock loses $35.07.
Analyst Consensus
BUY

Based on 26 analyst opinions
Low Target
$27.00
Mean Target
$47.13
High Target
$85.00


Earnings and Financial Data

Sector
Technology
Industry
Solar
Employees
2,872
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$1.03
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is ENPH a good stock to buy?
The analyst recommendation is buy based on 26 analysts, but revenue is declining 19.6% and the stock has negative short-term momentum. The takeaway is that ENPH offers upside potential with substantial execution risk.
What is ENPH’s analyst price target?
The average analyst target is $47.13, with estimates ranging from $27.00 to $85.00. The takeaway is that analysts see upside from $36.23, but their wide target range signals major uncertainty.
Is ENPH stock undervalued?
ENPH trades 50.68% below its 52-week high, but its P/E ratio remains 35.17 while revenue growth is negative 19.6%. The takeaway is that the lower share price does not automatically make the stock cheap.
What are ENPH’s support and resistance levels?
Near-term support is the 30-day low of $35.07, while resistance is the 30-day high of $42.30. The takeaway is that those are the key price levels defining the current trading range.
How strong is Enphase Energy’s balance sheet?
Enphase has $937.71 million in total cash and $613.36 million in total debt, so cash exceeds debt by $324.35 million. The takeaway is that the company has a positive net cash position based on the supplied figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 07, 2026.