
Lam Research Corporation (LRCX) Stock Analysis
By Nova Skye | AltStation.io | Updated October 27, 2026
Company Overview
Headquartered in Fremont, California, Lam Research operates in the Technology sector as a vital player in the Semiconductor Equipment & Materials industry. The company builds the multi-million-dollar machinery that semiconductor foundries use to manufacture advanced integrated circuits. Its core product lineup focuses on thin-film deposition tools like ALTUS and VECTOR, high-precision etch equipment like Kiyo and Vantex, and specialized wafer-cleaning platforms like Coronus. Major chipmakers and memory manufacturers across the United States, South Korea, Taiwan, and China buy these systems, providing Lam with a steady follow-on stream of revenue from recurring servicing, replacement parts, and upgrades.
Lam is not a generalist; it is the dominant market leader in semiconductor etch and holds the clear number two spot worldwide in deposition. While larger rival Applied Materials sells a broader catalog of equipment and ASML corners lithography, Lam dominates the high-aspect-ratio etching needed to carve billions of microscopic channels into silicon. That technological edge gives Lam formidable pricing power, though it also concentrates risk by tying results directly to the capital spending swings of a few giant memory and foundry clients. If chipmakers want to build next-generation 3D NAND or advanced logic chips, they cannot bypass Lam’s toolset.
The business is expanding fast, posting $23.23 billion in revenue for fiscal year 2026, a 26% increase over the $18.44 billion reported in the prior fiscal year. That growth is fueled by massive demand for artificial intelligence hardware, which requires high-bandwidth memory and taller 3D chip architectures that consume more of Lam’s etching tools per wafer. Profitability is outstanding, with Lam turning in a 31.27% net margin for fiscal 2026. Trade friction and export controls regarding sales into China remain the primary overhang, but Lam sits in a prime position as the global wafer fab equipment market expands toward the low-$150 billion range.
52-Week Price Performance Analysis
Recent News and Developments
September-quarter revenue rose 22% sequentially to $8.22 billion, while non-GAAP EPS increased 21% to $2.20. Lam guided December-quarter revenue to $8.60 billion, plus or minus $400 million, with non-GAAP EPS of $2.33, plus or minus $0.15. Source: Lam Research Corporation
Bernstein maintained its Buy rating on October 26 but cut its target from $385 to $350. UBS lowered its target from $425 to $400, while TD Cowen cut from $700 to $400; both retained Buy ratings. Source: Stock Analysis
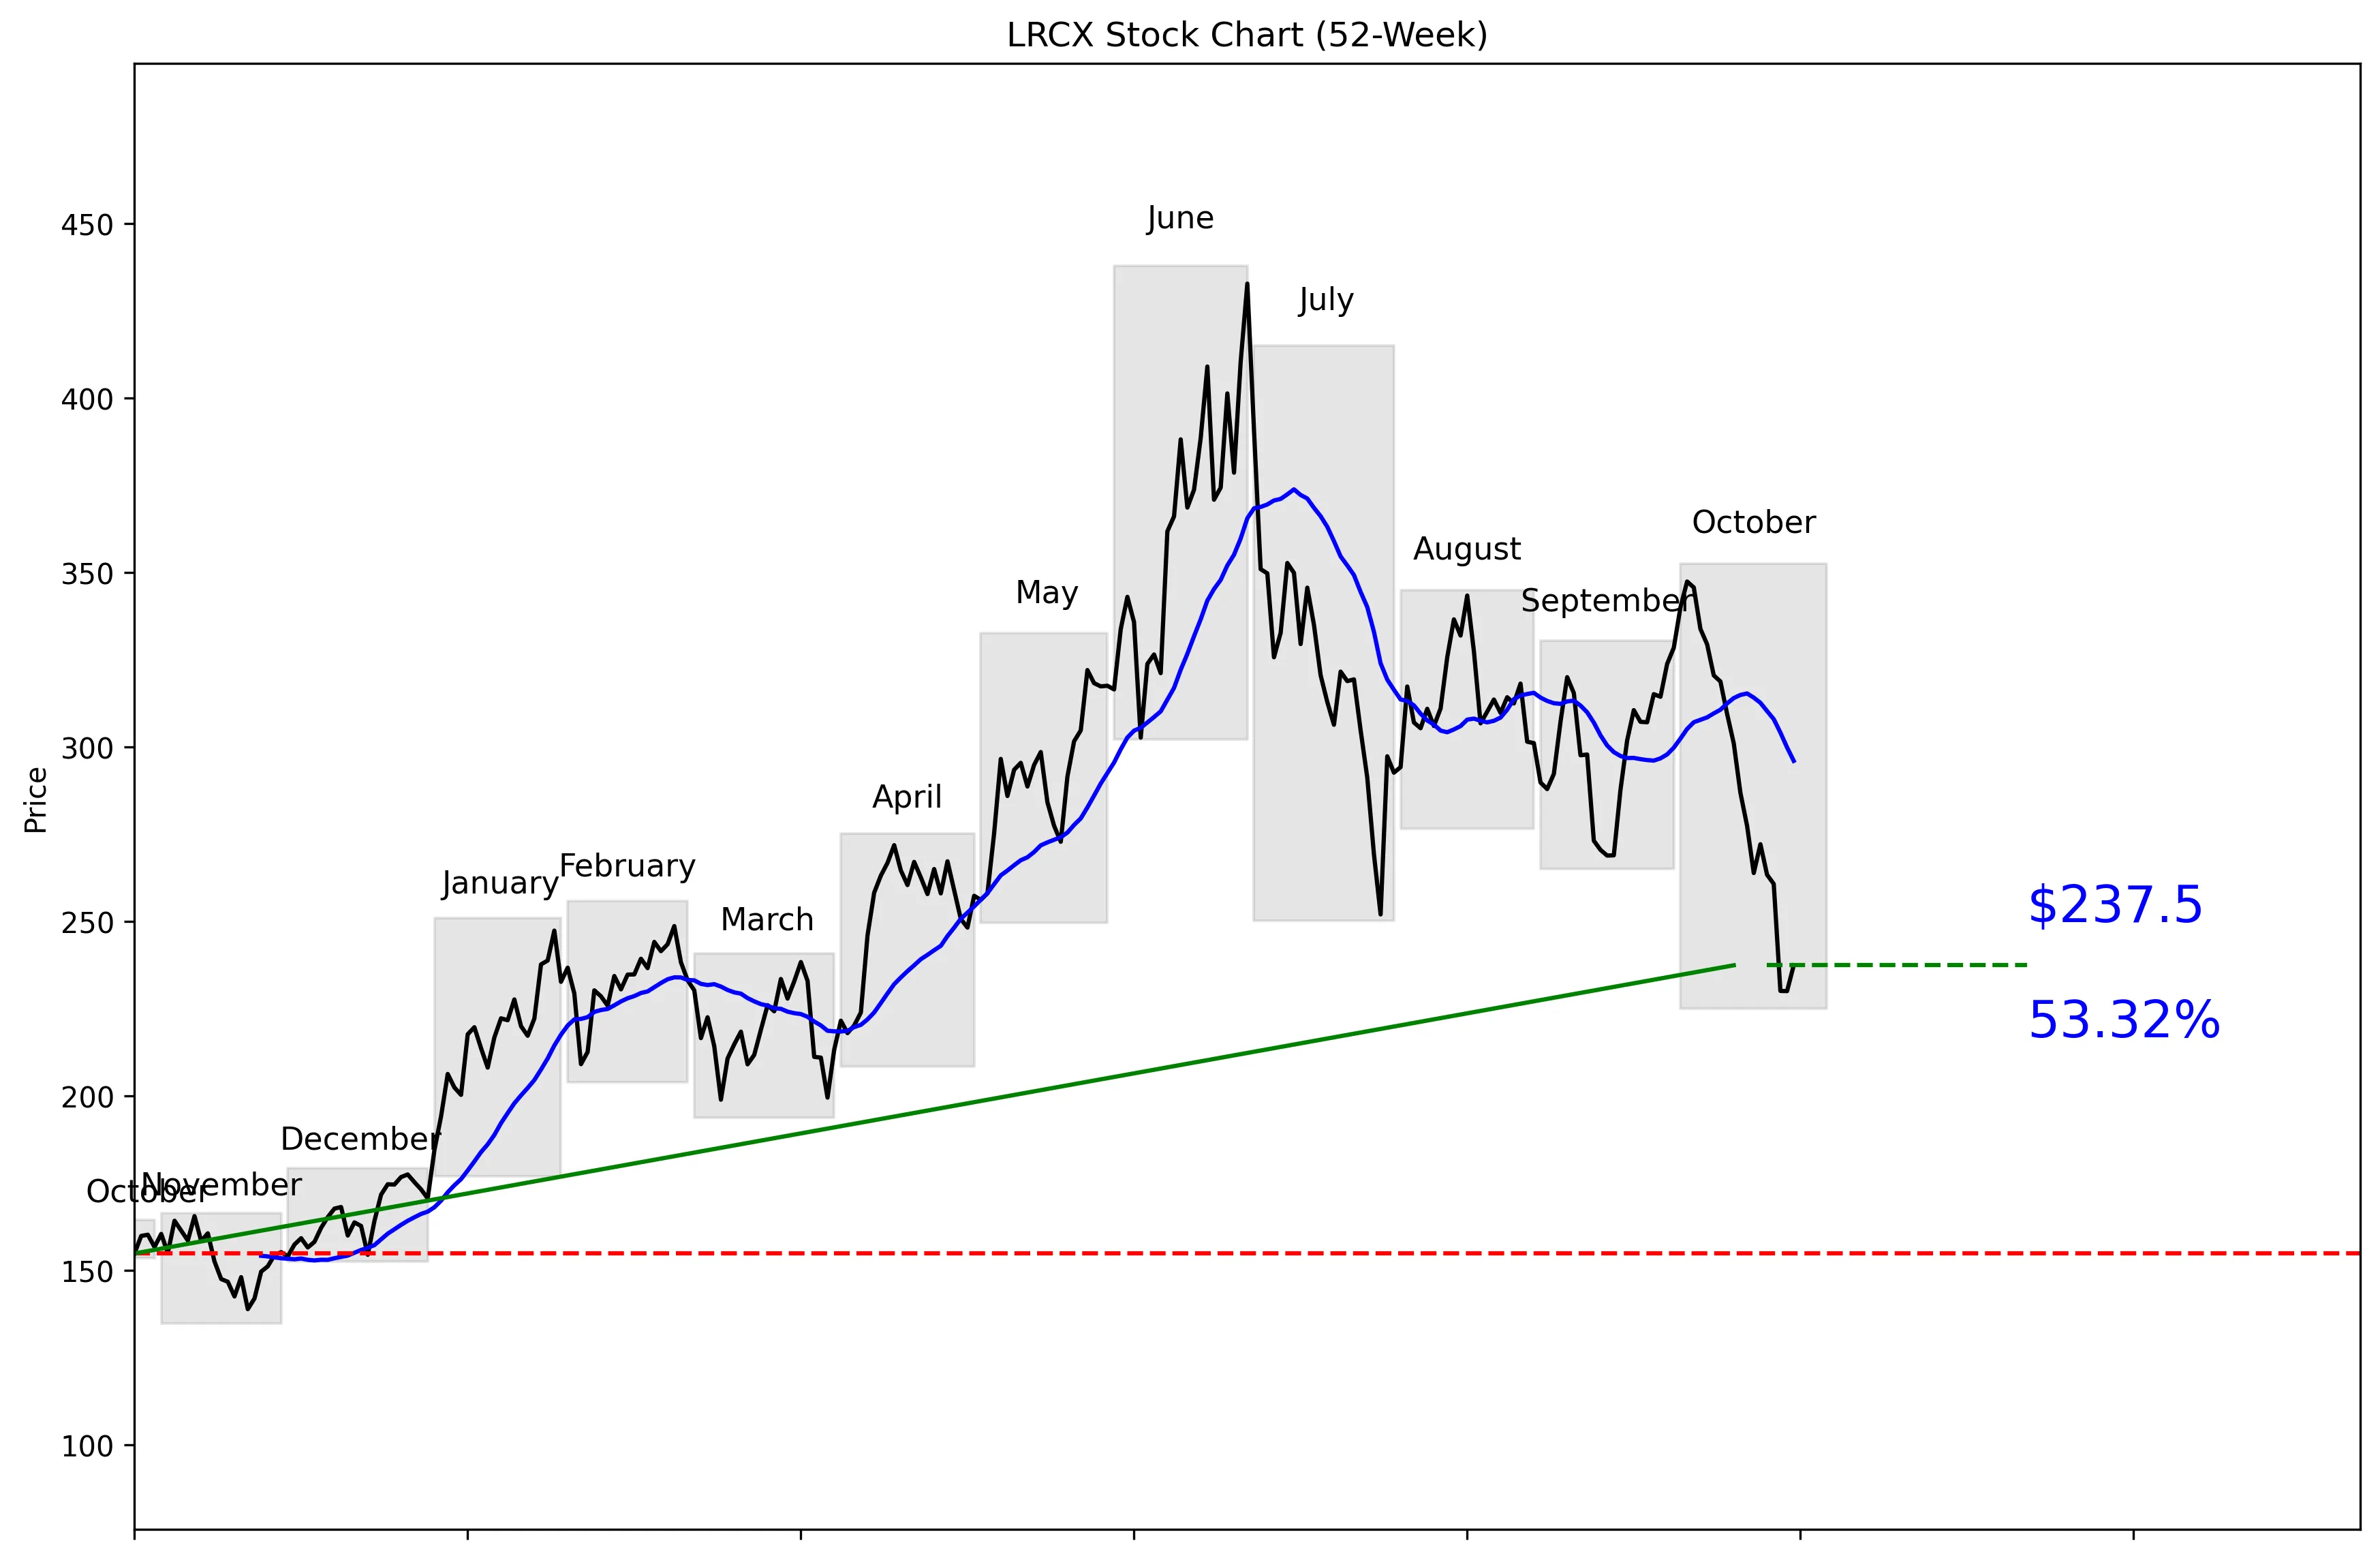
Lam shares dropped 11.8% on October 22 after the midpoint of its quarterly profit forecast came in slightly below analyst expectations. The stock entered the session up 52.4% for the year, leaving no room for merely adequate guidance. Source: Associated Press
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports