
ASML Holding N.V. (ASML) Stock Analysis
By Nova Skye | AltStation.io | Updated October 14, 2026
Company Overview
ASML Holding N.V., founded in 1984 and headquartered in Veldhoven, Netherlands, operates in the semiconductor equipment and materials industry within the technology sector. The company builds the specialized lithography systems that semiconductor fabricators rely on to print integrated circuit patterns onto silicon wafers. Its product portfolio spans extreme ultraviolet (EUV) systems and deep ultraviolet (DUV) immersion and dry systems, supported by YieldStar optical metrology platforms and HMI electron beam inspection tools. ASML sells these complex machines, proprietary control software, and lifecycle maintenance services directly to major chipmakers across Taiwan, South Korea, China, Japan, the United States, and Europe.
ASML is the undisputed market leader in lithography, maintaining an effective monopoly on commercial EUV systems required for the most advanced semiconductor nodes. Its primary competitive moat is the sheer engineering barrier of EUV and DUV immersion hardware, combined with computational lithography software that deeply embeds the company into customer fabrication workflows. Traditional equipment makers can compete in certain inspection or legacy dry lithography segments, but none offer a viable commercial alternative at the leading edge. The most significant structural threats to its business model stem from geopolitical export restrictions and concentration risk across a handful of massive global chipmakers.
The company is currently expanding its advanced lithography footprint while maximizing recurring revenue from field upgrades, tool refurbishments, and customer support. Because its tools are critical to factory output, ASML generates steady service and software revenue across an installed base that spans every major semiconductor manufacturing region. Its operational presence across Asia, the United States, and Europe ties its financial performance directly to global chip production capacity. ASML is not fighting for market relevance; it remains the essential bottleneck for the entire advanced microchip industry.
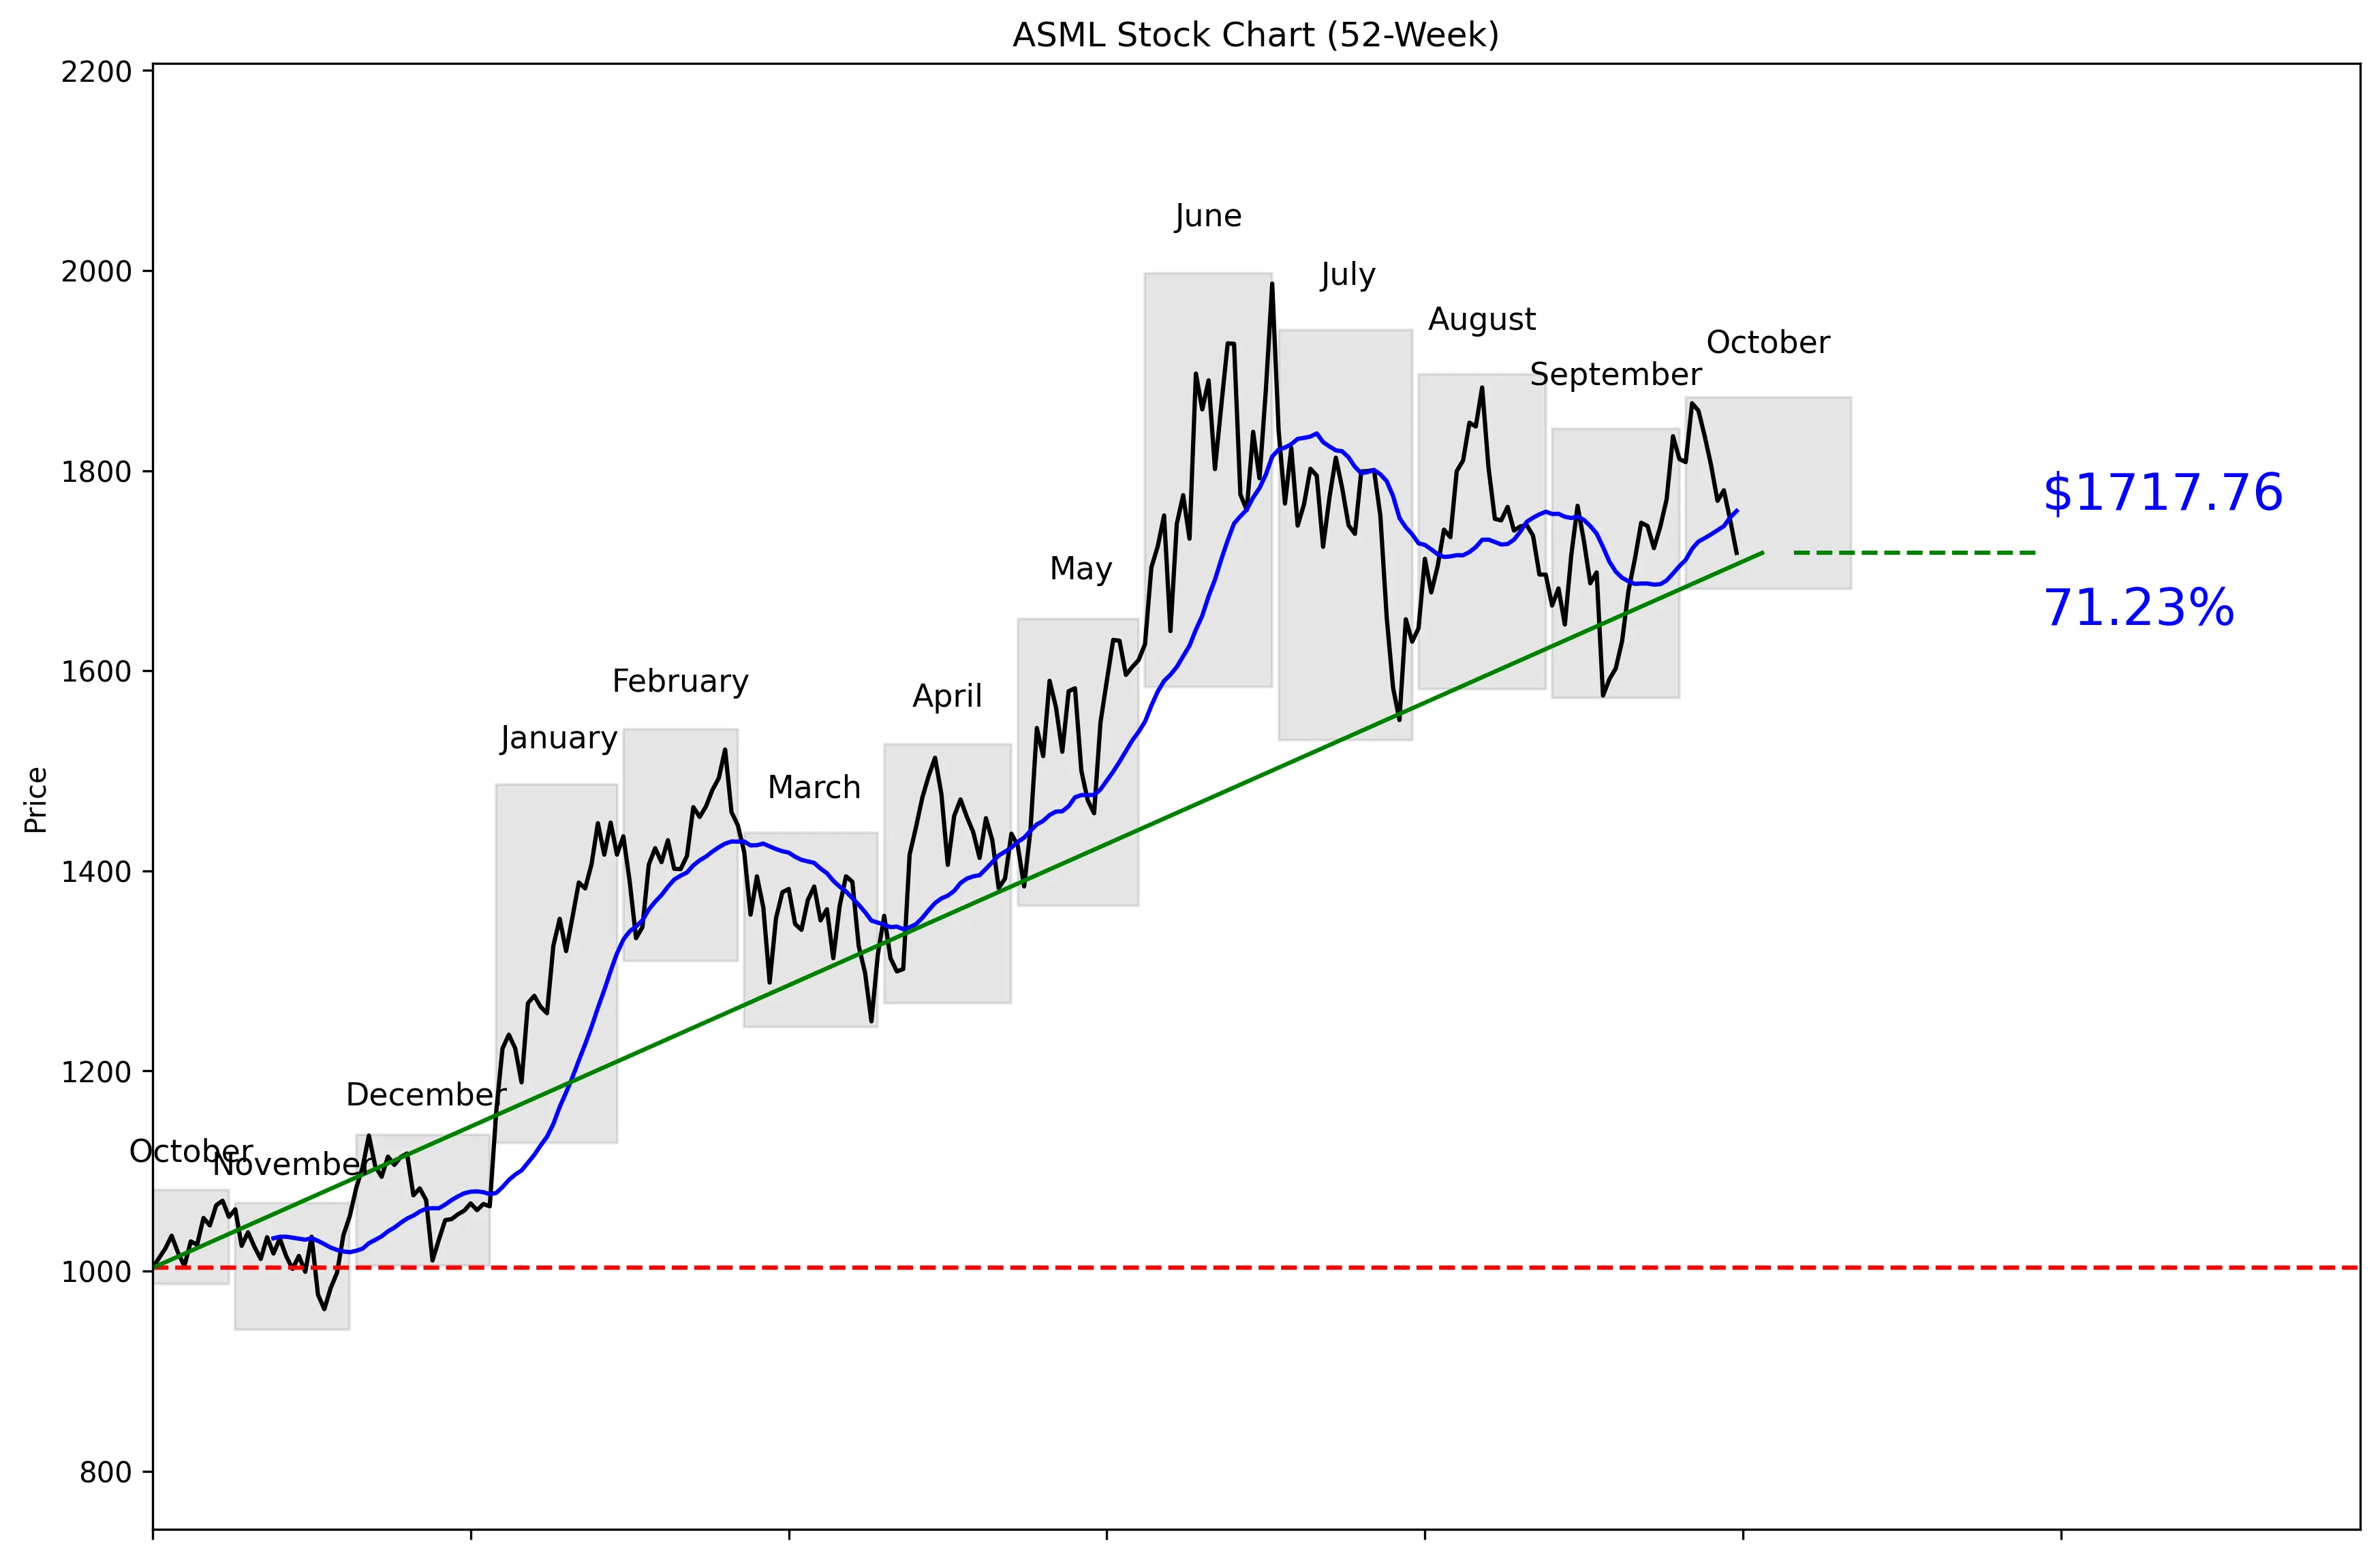
52-Week Price Performance Analysis
Recent News and Developments
ASML reported Q3 net sales of €11.7 billion, a 57.5% gross margin and €5.0 billion in net income. It raised the bottom of its full-year sales outlook to €44 billion, leaving the range at €44 billion to €45 billion, and guided Q4 sales to €14.2 billion to €15.2 billion. Source: ASML
RBC Capital reiterated its Outperform rating and $2,100 price target, citing strong EUV demand. The firm raised its 2028 revenue estimate by 8.7% to €76.5 billion and its earnings-per-share estimate by 13.0% to €85.2. Source: Investing.com
ASML and Zeiss engineers said a next-generation lithography system called Hyper NA could be ready in about 10 years. Their peer-reviewed paper said the technology could print features as small as 5 nanometers, more than one-third smaller than ASML’s current High NA system, but ASML has not committed to producing it. Source: Reuters via Euronext
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports