ALTSTATION.IO

Applied Materials, Inc. (AMAT) Stock Analysis

By Nova Skye | AltStation.io | Updated October 25, 2026

Price
$379.80
Change
+1.12%
Market Cap
$301.41B
Avg Volume
7.1M

Company Overview

Applied Materials, Inc. is a Santa Clara, California-based technology company operating in the Semiconductor Equipment and Materials industry. Incorporated in 1967, the company builds the specialized capital machinery, software, and tools required to manufacture semiconductor chips and wafers. They sell hardware across critical fabrication processes including deposition, etch, chemical mechanical planarization, metrology, and wafer packaging. Their customer base consists of chipmakers and electronic device manufacturers across key global hubs including the United States, China, Taiwan, South Korea, Japan, Southeast Asia, and Europe.

Applied Materials operates as a dominant market leader in materials engineering rather than a niche hardware player. Their primary moat is portfolio breadth, controlling critical manufacturing steps like ion implantation and rapid thermal processing under one roof. The company deepens customer lock-in through its Applied Global Services segment, which generates steady revenue from replacement spares, fab upgrades, and factory automation software. Heavy customer exposure across international hubs like China, Taiwan, and South Korea represents their primary operational risk.

The business is built on a two-segment foundation split between capital equipment sales and recurring factory services. The Semiconductor Systems segment drives growth by outfitting new fabrication facilities with tools for packaging, inspection, and deposition. Meanwhile, the Applied Global Services segment provides downside insulation through long-term maintenance, factory automation software, and 200-millimeter equipment support. Applied Materials does not design consumer devices; its valuation is a direct, unhedged bet on global chip manufacturing spending.

Key Financials
Market Cap
$301.41B
Revenue
$30.84B
EBITDA
$10.15B
Gross Margin
49.4%
Profit Margin
30.1%
Revenue Growth
24.8%
Total Cash
$9.23B
Total Debt
$7.35B
Free Cash Flow
$3.08B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
32.77
Forward P/E
20.54
Beta
1.59
52-Week High
$739.67
52-Week Low
$203.40
EPS
$11.59
50-Day Avg
$471.56
200-Day Avg
$441.51
Price/Book
11.76
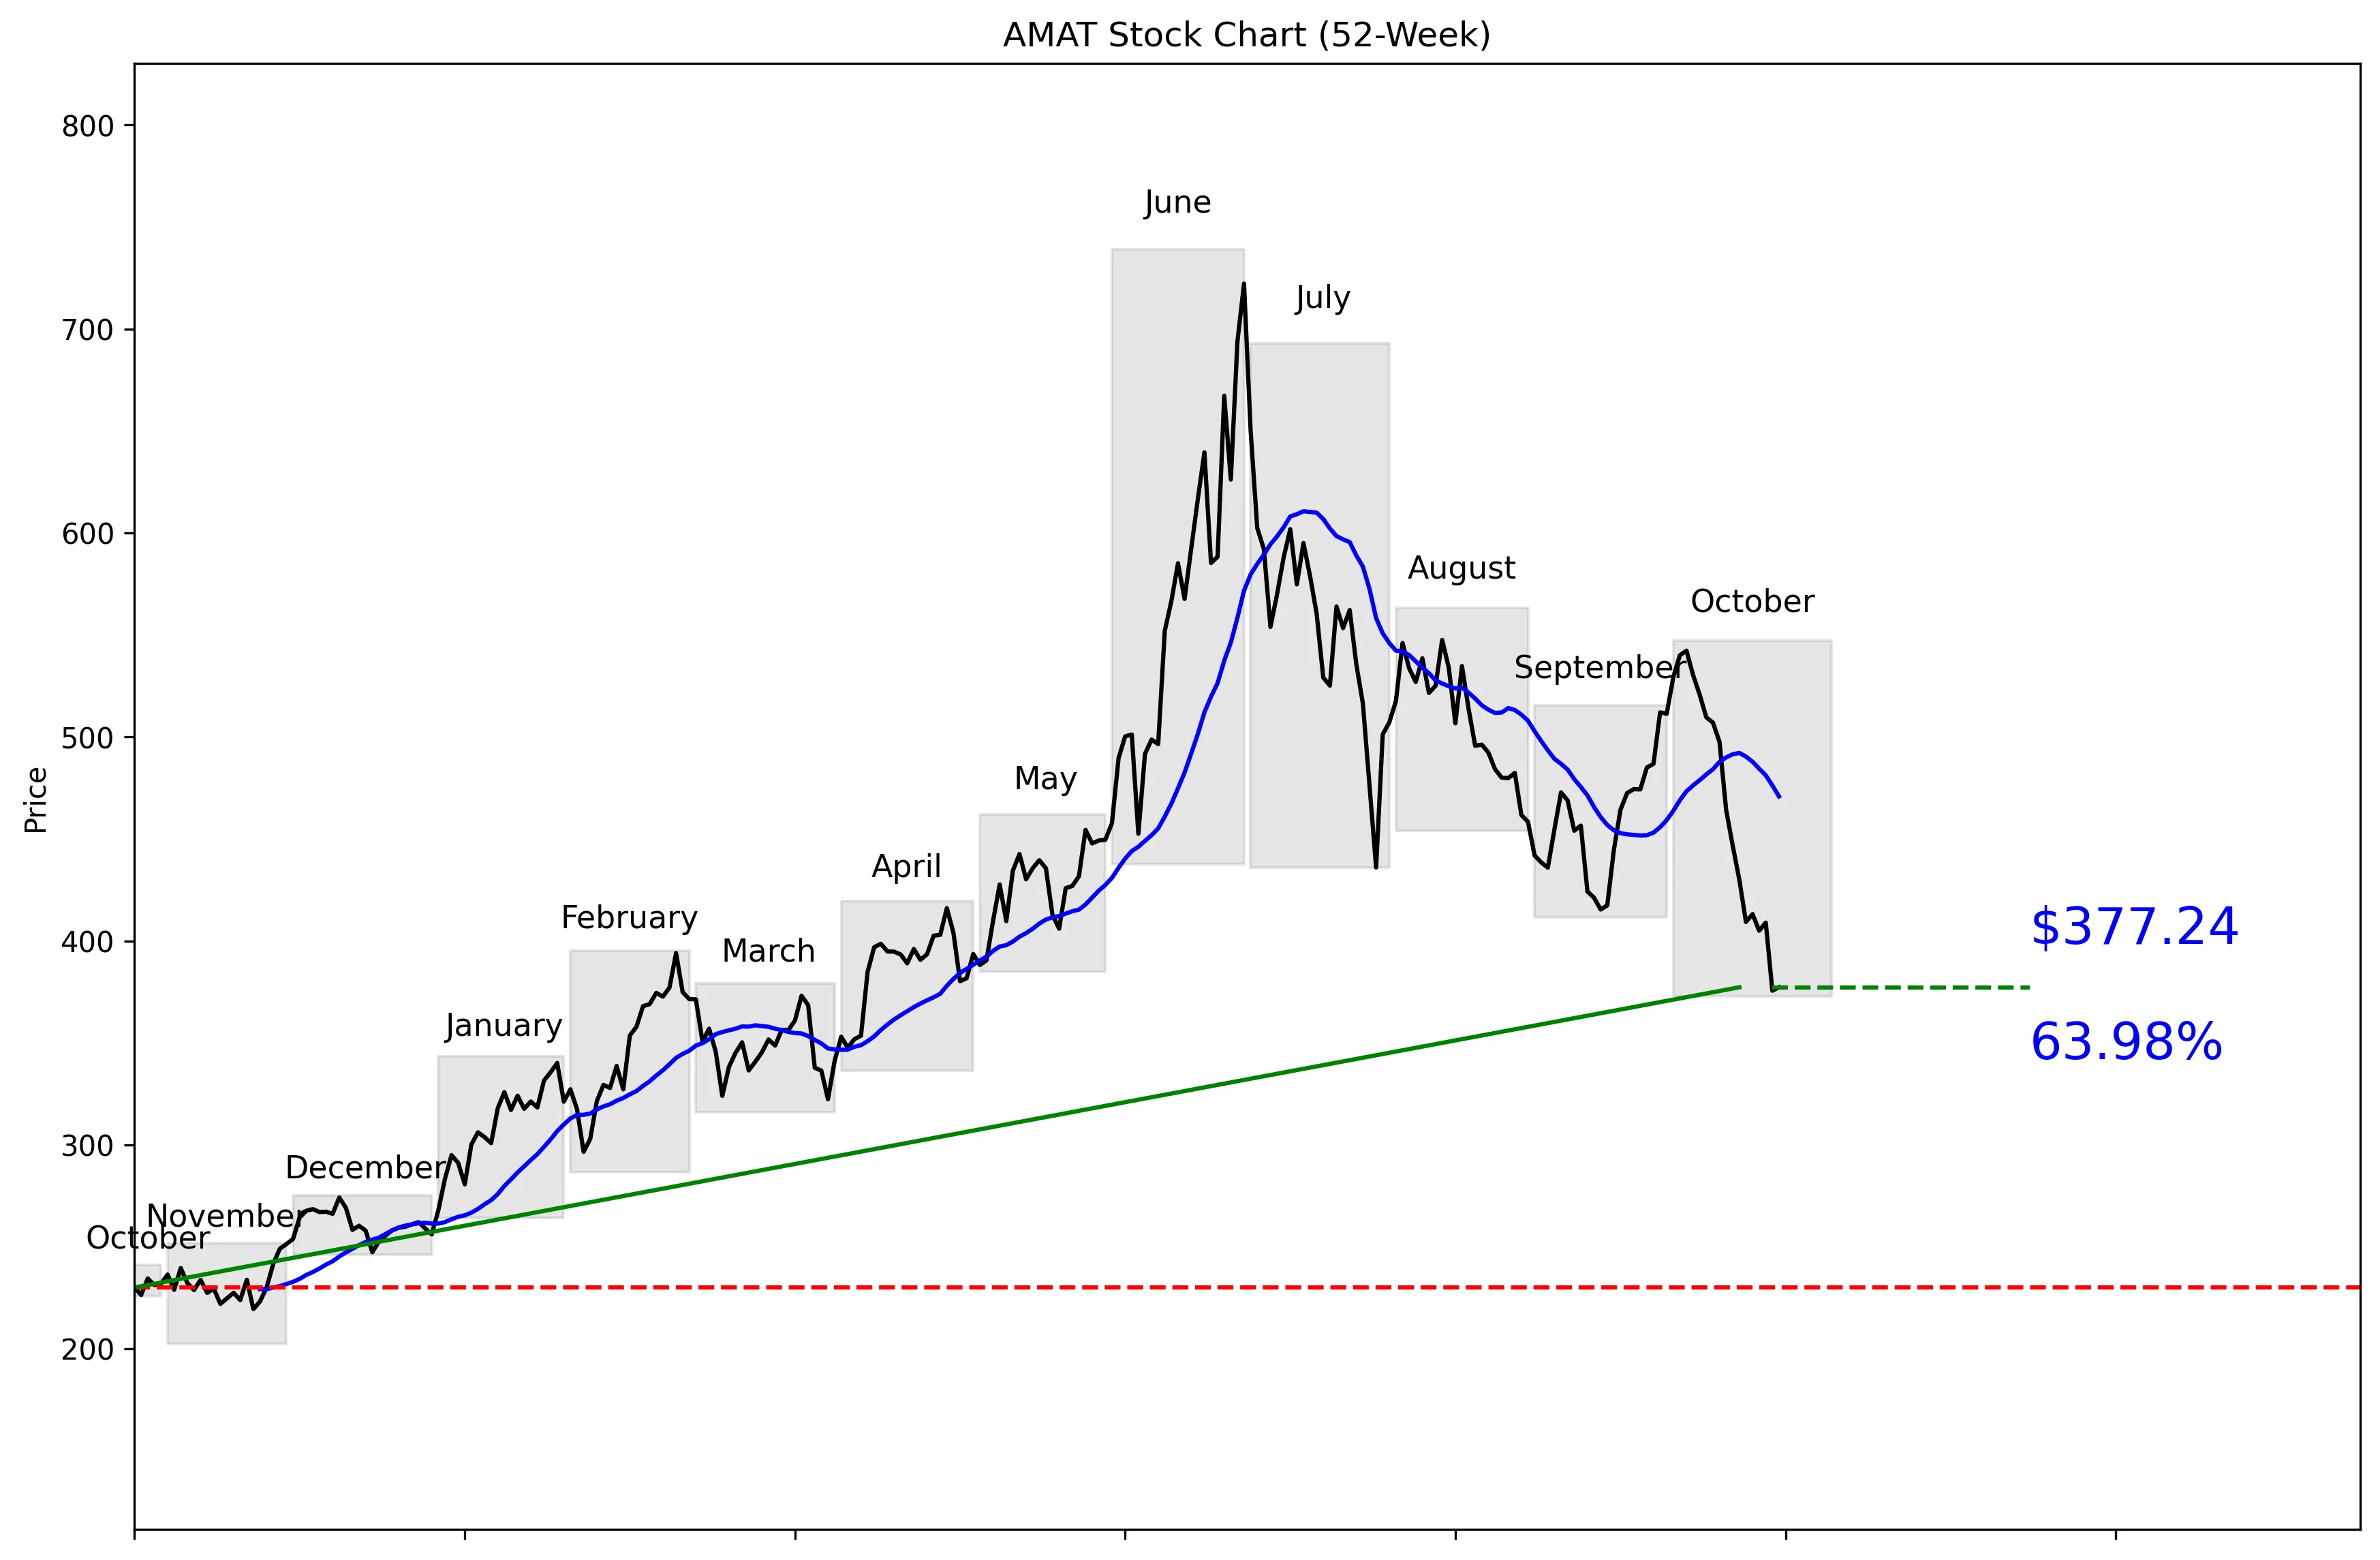
AMAT 52-Week Stock Chart
Technical Analysis
AMAT trades at $379.80, just 33% of the way from its $202.28 52-week low to its $738.88 high. The stock is 48.94% below that high but remains 86.49% above the low. Price sits 19.88% below the 20-day moving average of $470.84, confirming a weak short-term trend. Momentum is negative at 7.83% over five trading days and 22.22% over 20 trading days. Near-term support is $375.58, while resistance is $542.28.


Recent News and Developments

Applied Materials sets November 12 earnings call

Applied Materials will report fiscal fourth-quarter and full-year 2026 results on November 12. The earnings call starts at 4:30 p.m. ET, with a replay available by 8:00 p.m. ET. Source: Applied Materials

Morgan Stanley maintains Hold rating and $563 target

Morgan Stanley maintained its Hold rating and $563 price target on October 20 after attending Applied Materials’ investor breakfast and EPIC Center opening. The firm cited stronger-than-expected DRAM equipment performance and increased confidence in the long-term strategy, but that was not enough to earn an upgrade. Source: StreetInsider

AMAT plunges 8.16% after Lam Research warning

Applied Materials fell 8.16% on October 22, closing at $375.58 after Lam Research said supply constraints limited its December-quarter outlook. Applied Materials released no negative operating update of its own, making this a peer-driven selloff layered onto existing valuation concerns. Source: Yahoo Finance


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $30.84 billion and growing 24.8%, which is the strongest fundamental reason to own AMAT. The company also holds $9.23 billion in cash against $7.35 billion in total debt. Analysts remain firmly bullish, with a strong_buy recommendation based on 36 analysts. Their average target is $627.83, well above the current $379.80 price. The target range reaches as high as $900.00, showing that the most bullish analysts still see substantial upside. Morgan Stanley also cited stronger-than-expected DRAM equipment performance and increased confidence in the long-term strategy, even while keeping its Hold rating and $563 target.
Bear Case
AMAT trades at 32.77 times earnings, so the valuation still demands strong growth and clean execution. The chart is damaged: shares are 19.88% below the 20-day moving average and momentum is negative over both five and 20 trading days. The stock is also down 48.94% from its 52-week high, which shows how quickly sentiment has reversed. AMAT fell 8.16% on October 22 after Lam Research warned that supply constraints limited its December-quarter outlook. That selloff was peer-driven, but it shows AMAT remains exposed to concerns affecting the broader equipment industry. The lowest analyst target is $358.00, below the current $379.80 price, so not every analyst sees upside from here.
What to Watch
Applied Materials will report fiscal fourth-quarter and full-year 2026 results on November 12, with the earnings call starting at 4:30 p.m. ET. Revenue growth is currently 24.8%, and investors should watch whether the next report supports that pace. The $375.58 30-day low is the immediate technical threshold because the current price is only slightly above it at $379.80. A sustained recovery above the $470.84 20-day moving average would improve the short-term trend. The next major resistance level is $542.28, while a break below $375.58 would confirm further weakness. Investors should also watch whether the DRAM equipment strength noted by Morgan Stanley outweighs the supply-constraint concerns raised by Lam Research.
Analyst Consensus
STRONG BUY

Based on 36 analyst opinions
Low Target
$358.00
Mean Target
$627.83
High Target
$900.00


Earnings and Financial Data

Sector
Technology
Industry
Semiconductor Equipment & Materials
Employees
38,900
Earnings & Dividends
Next Earnings
Nov 12, 2026
EPS (Trailing)
$11.59
Dividend Yield
56.0%
Payout Ratio
16.5%

Frequently Asked Questions

Is AMAT a good stock to buy?
AMAT has a strong_buy recommendation from 36 analysts, revenue growth of 24.8%, and an average analyst target of $627.83. The takeaway is that analysts are bullish, but the weak technical trend makes timing important.
What is AMAT’s price target?
The average analyst target is $627.83, with estimates ranging from $358.00 to $900.00. The takeaway is that Wall Street sees significant potential but has a very wide range of outcomes.
Is AMAT overvalued?
AMAT trades at a P/E ratio of 32.77 while revenue is growing 24.8%. The takeaway is that the valuation is demanding, but it is supported by strong reported growth.
What are AMAT’s support and resistance levels?
Near-term support is the 30-day low of $375.58, and near-term resistance is the 30-day high of $542.28. The takeaway is that AMAT is trading close to support and well below resistance.
Does AMAT pay a dividend?
The provided data does not include dividend information. The takeaway is that no dividend conclusion can be made from these figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 25, 2026.