
Fastenal Company (FAST) Stock Analysis
By Nova Skye | AltStation.io | Updated October 18, 2026
Company Overview
Fastenal Company operates in the Industrials sector as a heavyweight in Industrial Distribution, headquartered in Winona, Minnesota. Founded in 1967, the company sells wholesale fasteners—including bolts, nuts, screws, and studs—alongside hardware like anchors, wire ropes, and maintenance supplies. Their customer base covers original equipment manufacturers, non-residential construction contractors, government agencies, and industrial maintenance operations across the United States, Canada, Mexico, and international markets. They solve the headache of supply shortages by keeping critical parts stocked where factories and builders actually use them.
Fastenal is a dominant market leader in a fragmented distribution industry, battling major players like W.W. Grainger and MSC Industrial Supply. Their competitive moat is not just shipping parts from warehouses; it is physical integration inside customer facilities through Fastenal Managed Inventory systems and FASTVend machines. That direct floor access creates immense switching costs because clients rely on their automated replenishment to prevent factory downtime. The primary threat to this position is broad industrial cyclicality, where slowdowns in heavy manufacturing or construction immediately hit order volumes.
The business is steadily expanding, generating approximately $8.74 billion in trailing twelve-month revenue and posting second-quarter 2026 revenue of $2.39 billion, a 14.7% year-over-year increase. Fastenal is aggressively executing a strategic shift away from standalone public storefronts toward dedicated Onsite locations and digital FASTBin tracking. This strategy deepens their capture of large corporate accounts, trading transactional foot traffic for sticky, recurring enterprise contracts. By embedding their staff and tech directly inside client plants, Fastenal continues to take market share even in choppy macroeconomic environments.
52-Week Price Performance Analysis
Recent News and Developments
Third-quarter sales reached $2.463 billion, while diluted EPS rose 19.8% to $0.35. Operating margin improved 90 basis points to 21.5%, and operating cash flow totaled $422 million. Source: U.S. Securities and Exchange Commission
Baird maintained its Outperform rating and raised its price target from $59 to $60. Bernstein kept its Underperform rating but increased its target from $42 to $47, leaving a sharp split on valuation despite the earnings beat. Source: Benzinga
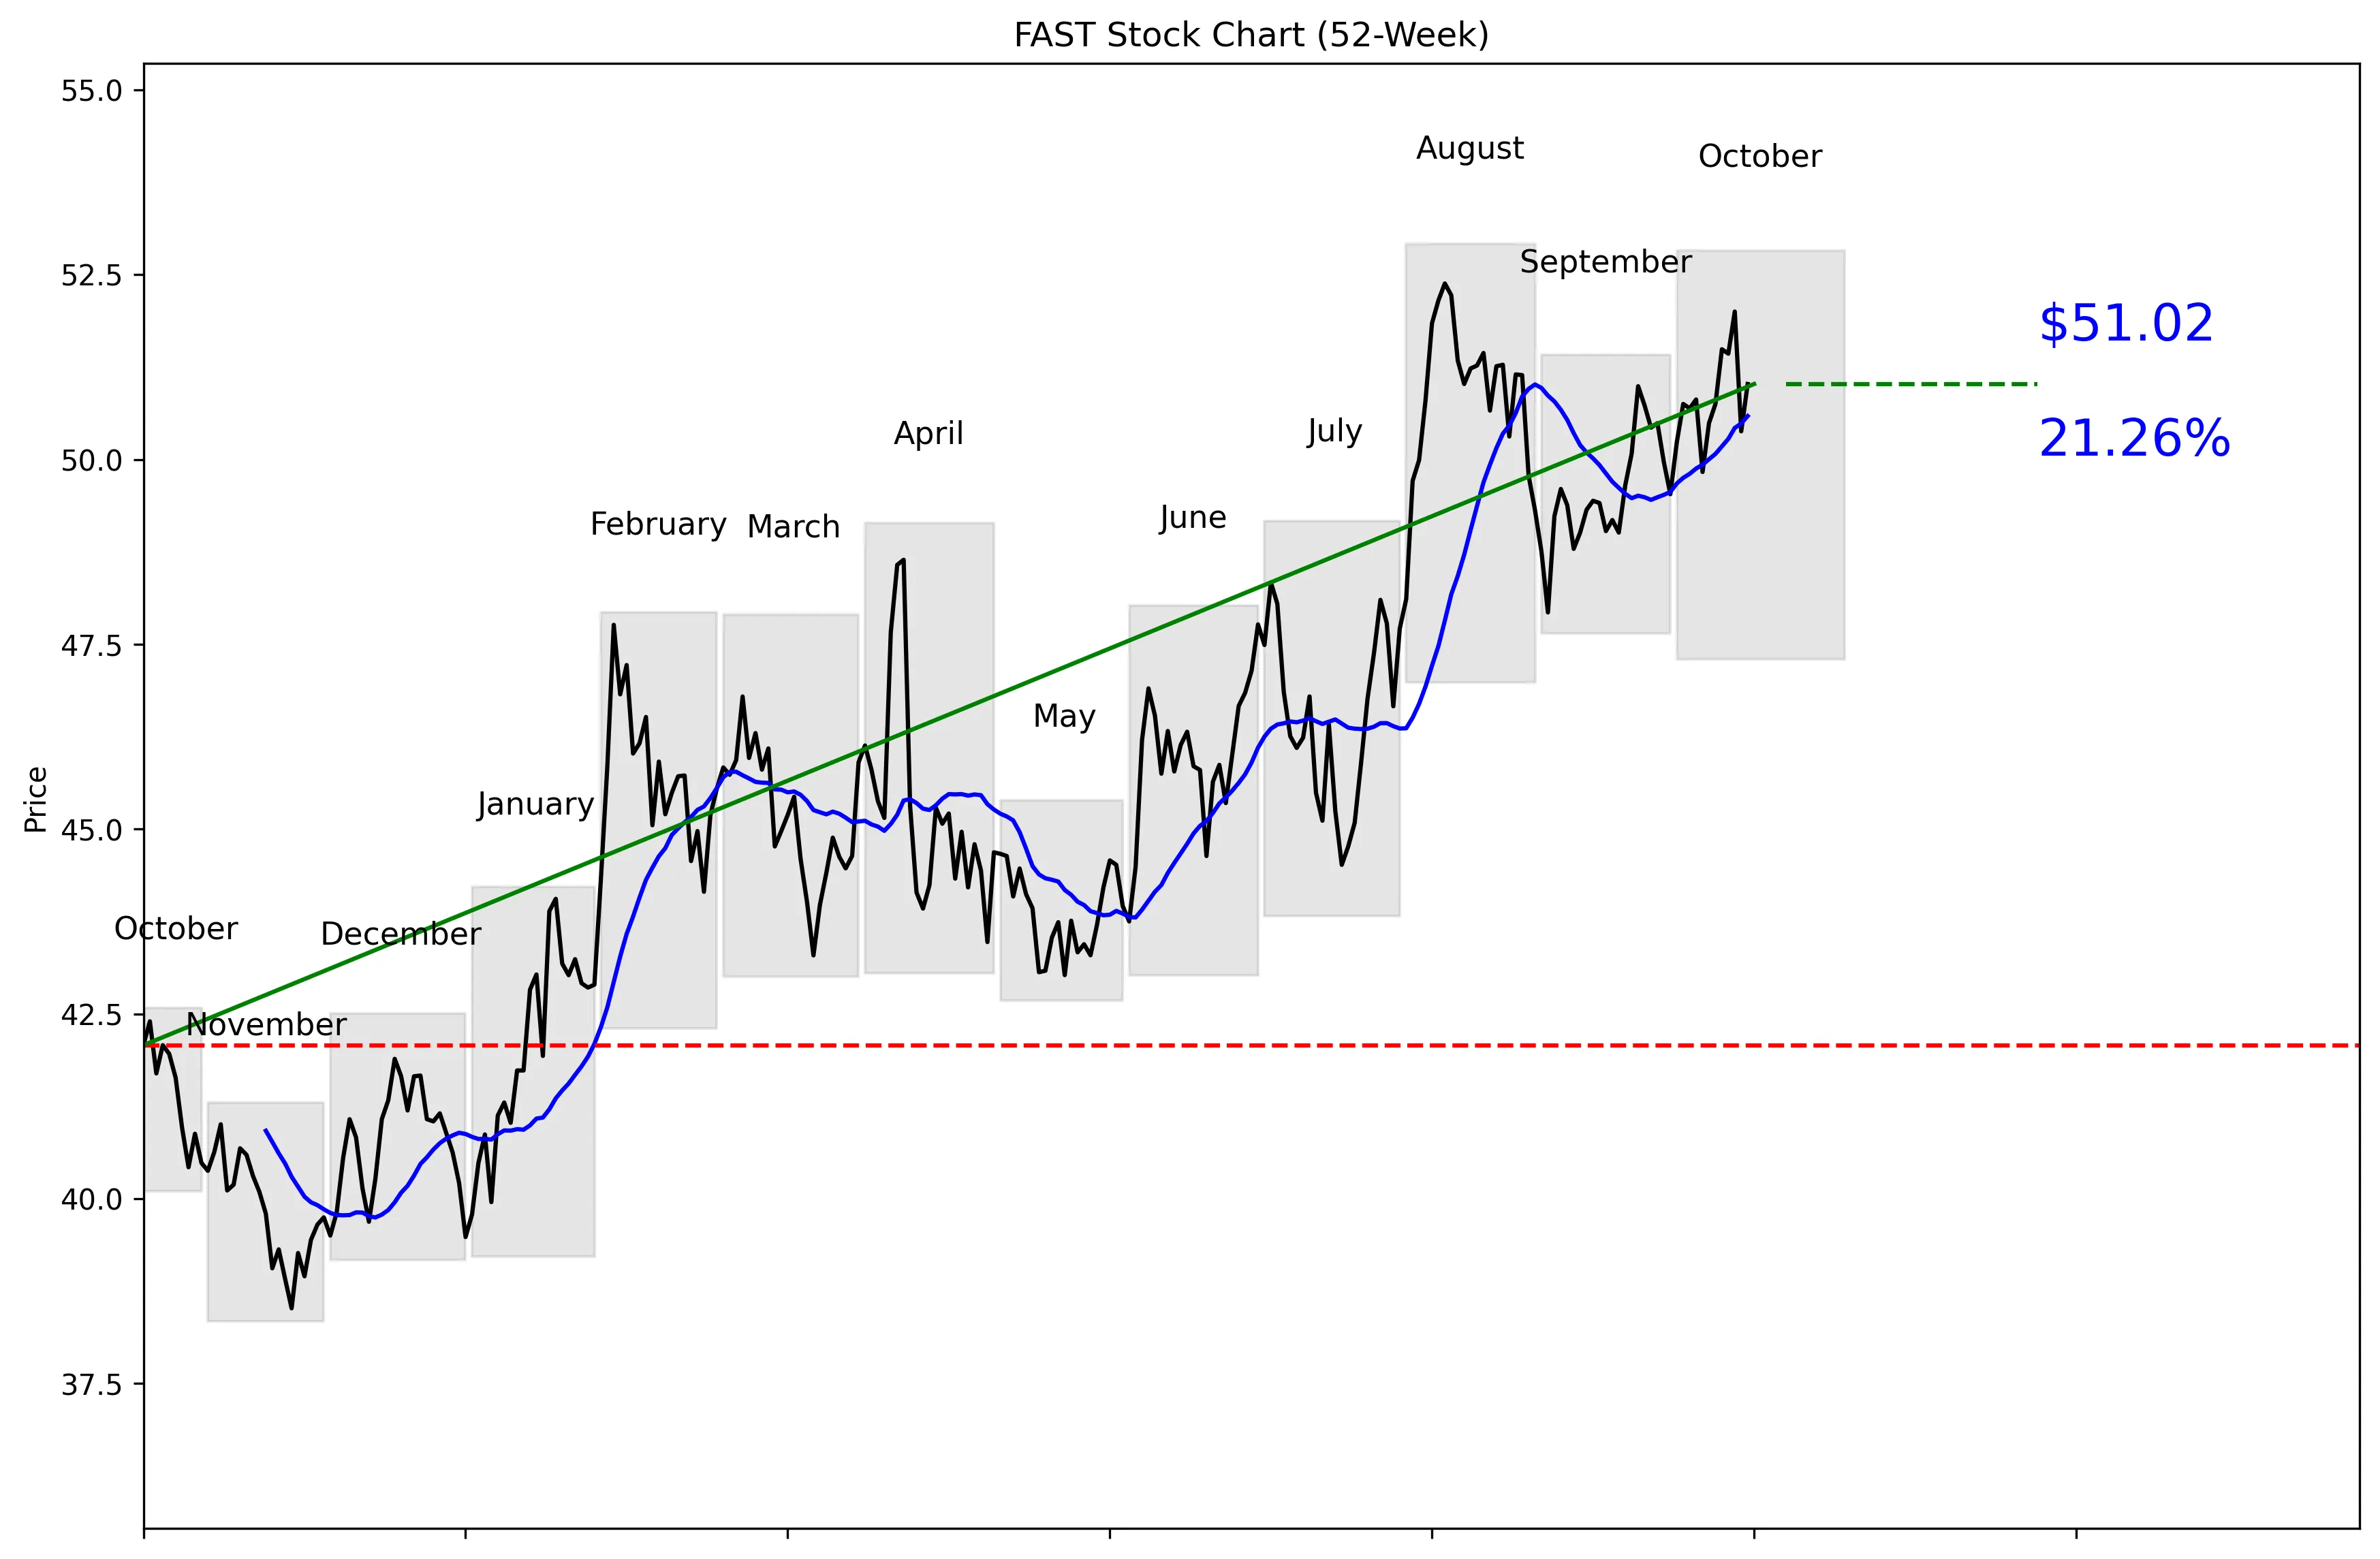
FAST traded between $47.30 and $52.43 on October 14 before closing 1.11% higher at $52.00. The stock then dropped 3.12% to $50.38 on October 15 and recovered 1.27% to $51.02 on October 16. Source: StockAnalysis
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports