ALTSTATION.IO

The Hartford Insurance Group, Inc. (HIG) Stock Analysis

By Nova Skye | AltStation.io | Updated October 27, 2026

Price
$136.82
Change
+0.05%
Market Cap
$37.06B
Avg Volume
1.6M

Company Overview

The Hartford Insurance Group (HIG) is a diversified insurance and financial services provider founded in 1810 and headquartered in Hartford, Connecticut. They sell property, casualty, and commercial coverage to individual drivers and homeowners, small businesses, and large corporate clients across the United States, the United Kingdom, and international markets. The business runs across five distinct operational units: Business Insurance, Personal Insurance, Property & Casualty Other Operations, Employee Benefits, and Hartford Funds. Alongside standard auto, home, and workers’ compensation policies, they distribute group disability and life plans to employer groups, while managing mutual funds and exchange-traded funds for retail and institutional investors.

The Hartford operates as an established market heavyweight with deep roots, relying on an extensive multi-channel distribution network of independent brokers, retail agents, third-party administrators, and financial advisers. Their edge comes from product breadth, pairing core commercial lines like liability, marine, and surety coverage with specialized employee benefits and leave management services. However, running legacy property and casualty operations exposes them to long-tail risks, specifically asbestos and environmental exposures managed within their specialized runoff unit. In a crowded diversified insurance sector, they compete directly with other multi-line carriers and asset managers for broker distribution and investment assets.

Right now, the company stands on a dual foundation of core insurance underwriting and fee-generating asset management. Rather than trying to pivot into an entirely new business model, The Hartford focuses on scaling its high-touch employee benefits administration alongside its mutual fund and ETF platforms. Managing legacy liability exposures remains an ongoing operational reality that requires disciplined risk control. For investors, HIG is fundamentally a mature, capital-intensive financial stalwart whose trajectory depends on maintaining disciplined underwriting margins across business lines while defending market share in personal and employer-sponsored coverage.

Key Financials
Market Cap
$37.06B
Revenue
$29.32B
EBITDA
$5.59B
Gross Margin
37.9%
Profit Margin
14.9%
Revenue Growth
8.1%
Total Cash
$3.99B
Total Debt
$4.38B
Free Cash Flow
$5.51B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
9.77
Forward P/E
9.94
Beta
0.49
52-Week High
$146.07
52-Week Low
$120.33
EPS
$14.01
50-Day Avg
$133.43
200-Day Avg
$135.44
Price/Book
1.93
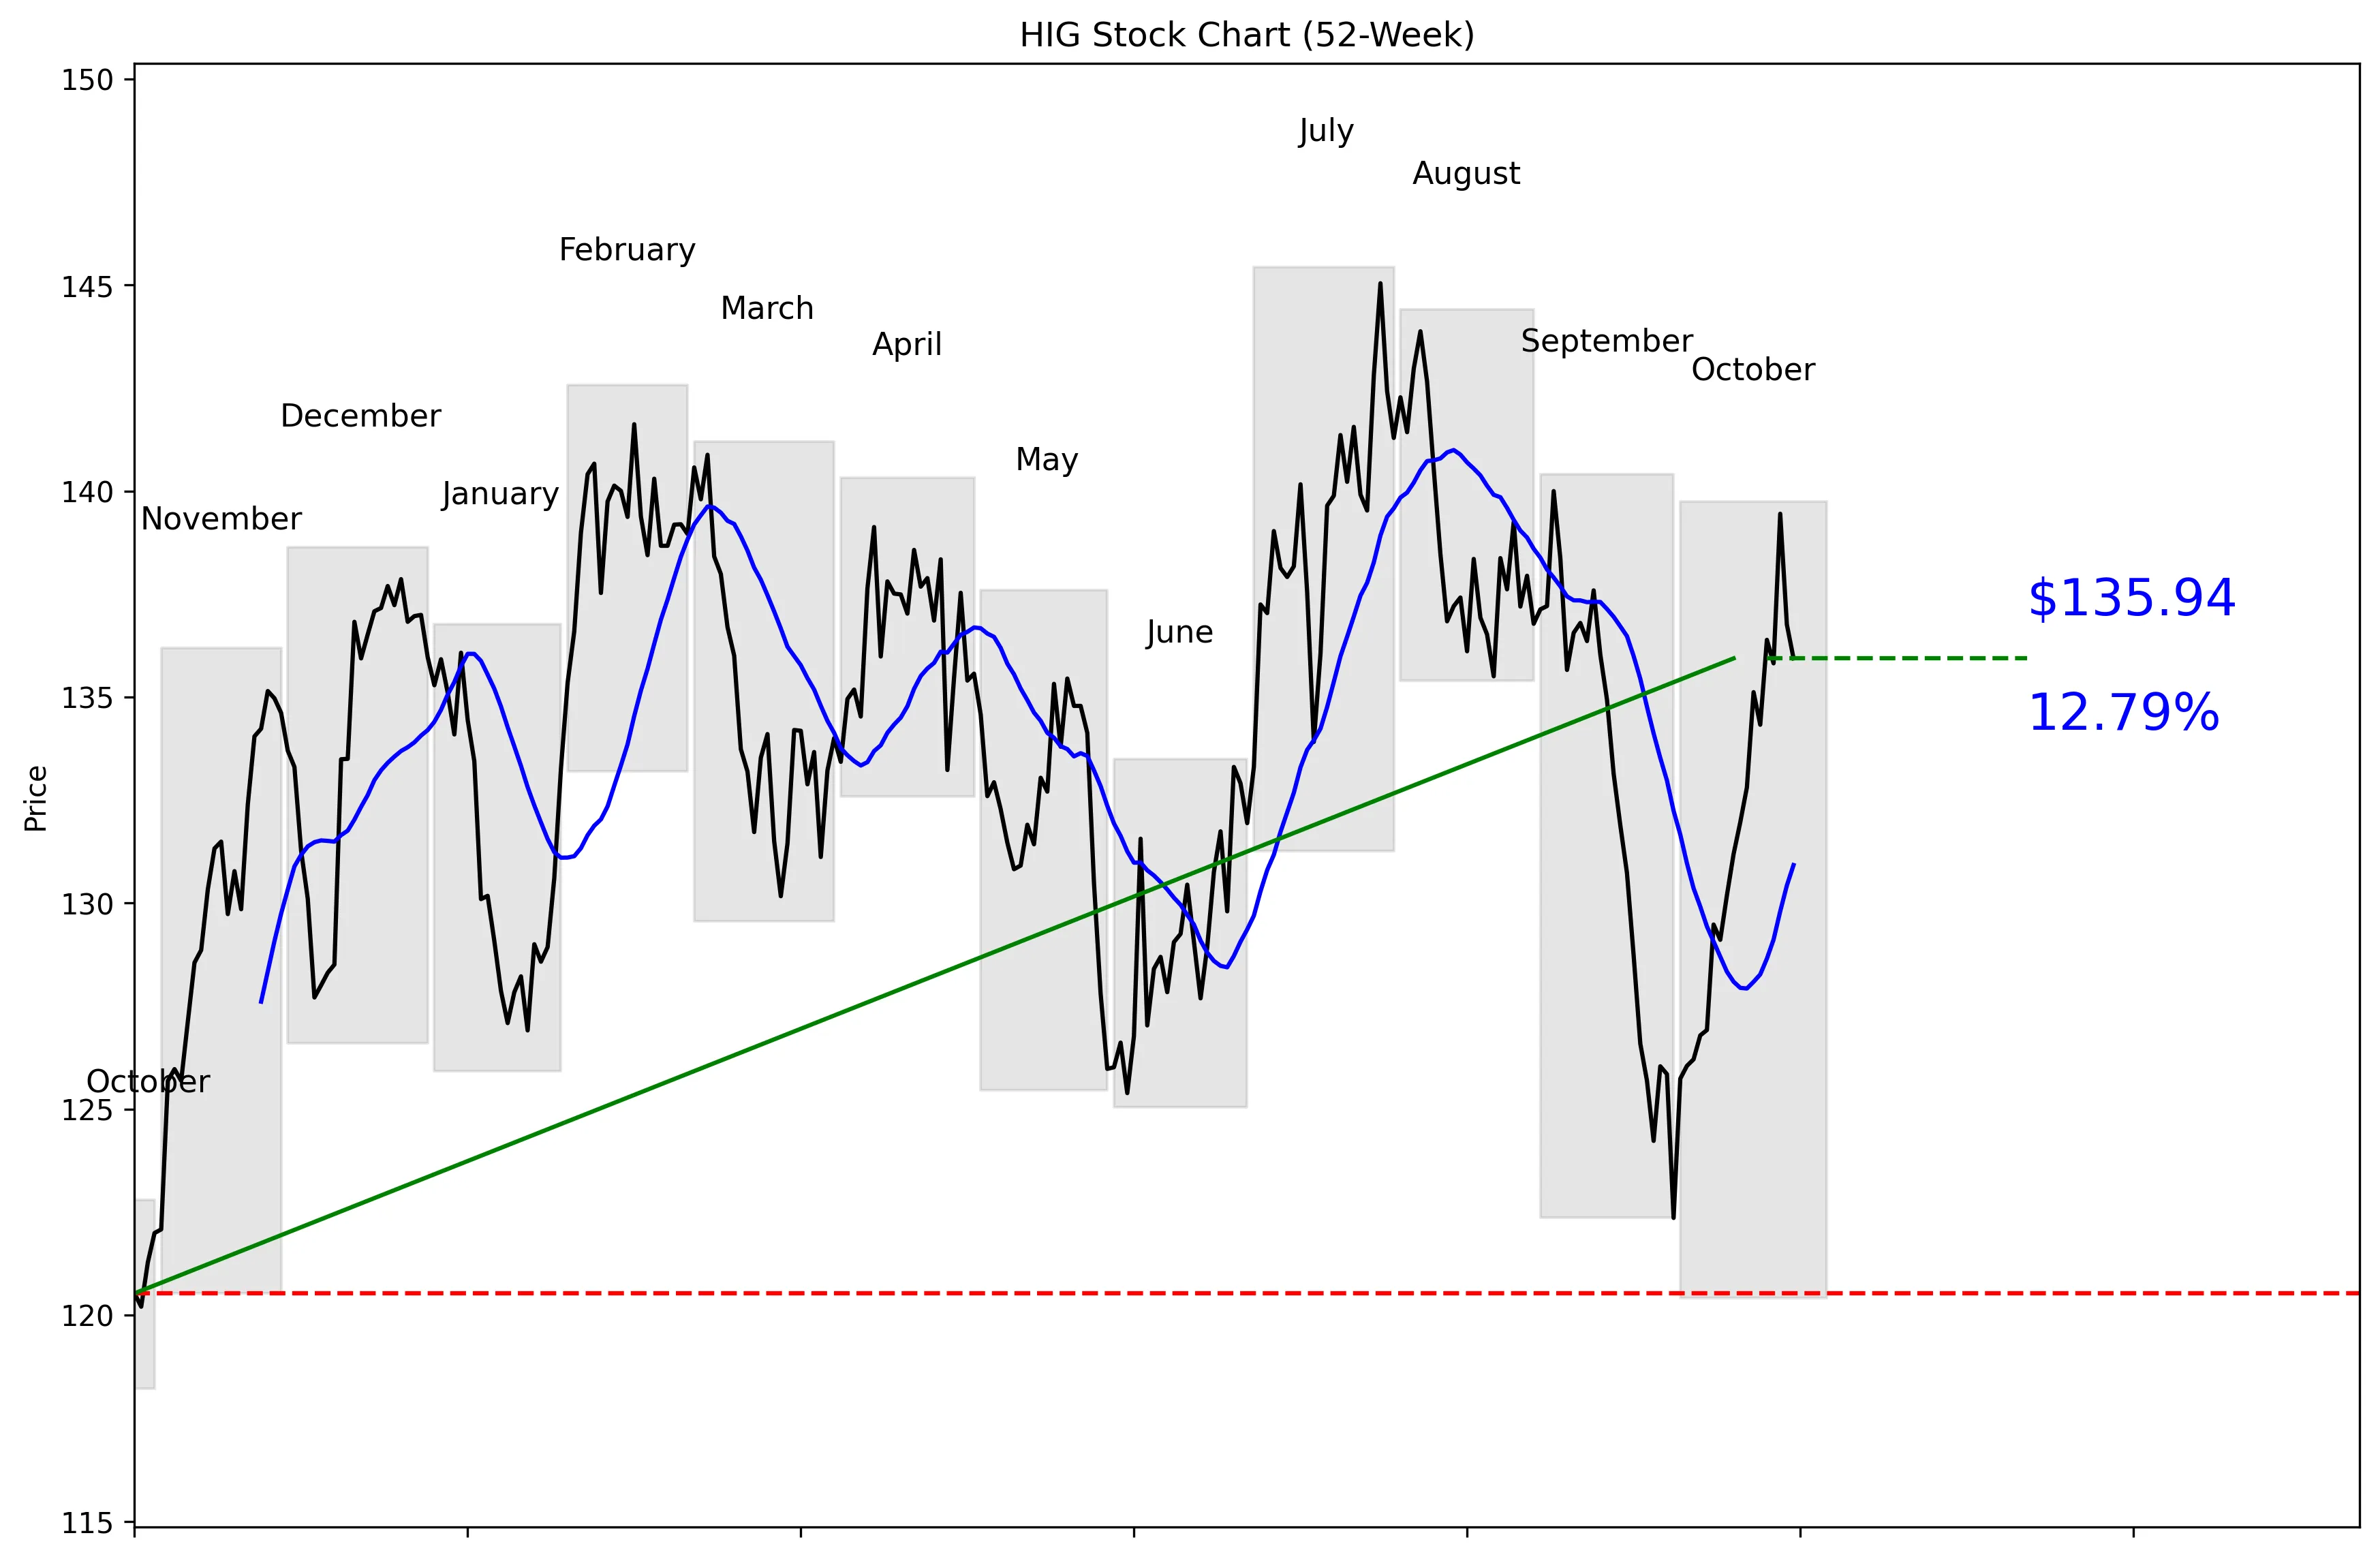
HIG 52-Week Stock Chart
Technical Analysis
HIG trades at $136.82, 65% of the way from its $118.21 52-week low to its $145.43 high. The stock is 6.53% below that high and 15.00% above the low. Price is above the $130.92 20-day moving average, with the supplied technical data showing a 3.83% difference. Momentum is positive at 1.20% over five trading days and 7.85% over 20 trading days. Near-term support is $122.36, while resistance sits at $139.45.


Recent News and Developments

Hartford posts $1.3 billion quarterly profit

Third-quarter net income rose 23% to $1.317 billion, or $4.82 per diluted share. Core earnings fell 6% to $956 million, while core EPS declined 3% to $3.50. Source: The Hartford

Hartford raises quarterly dividend 12%

The board increased the quarterly common-stock dividend 12% to $0.67 per share. It is payable January 5, 2027, to shareholders of record on December 1, 2026. Source: The Hartford

Evercore cuts HIG price target to $144

Evercore ISI lowered its HIG price target from $147 to $144 on October 27. The cut leaves the target $8.02 above HIG’s October 26 closing price of $135.98. Source: MarketScreener


Market Sentiment and Analyst Recommendations

Bull Case
HIG generated $29.32 billion in revenue, with revenue growth running at 8.1%. Third-quarter net income increased 23% to $1.317 billion, or $4.82 per diluted share. The stock trades at 9.77 times earnings, which is not demanding for a company producing that level of growth and profit. Management also raised the quarterly dividend 12% to $0.67 per share, giving shareholders a larger cash return. The $146.86 analyst target sits above the current $136.82 price, while the top target reaches $163.00. With 21 analysts rating HIG a buy, positive price momentum, and a low P/E, the case for owning it remains solid.
Bear Case
The headline profit growth masks weaker core results. Core earnings fell 6% to $956 million, and core EPS declined 3% to $3.50. That gap between net income growth and core earnings performance is the biggest fundamental concern in the supplied data. HIG also carries $4.38 billion in debt against $3.99 billion in cash. Evercore cut its target from $147 to $144, and the analyst target range falls as low as $135.00, below the current $136.82 price. Shares traded at $134.41 in extended trading after the earnings release, showing that investors were not impressed by the headline numbers alone.
What to Watch
Core earnings are the key metric next quarter because the latest 6% decline conflicts with the 23% increase in net income. Core EPS also needs to improve from $3.50 after falling 3%. Investors should watch whether revenue growth holds near 8.1% and whether stronger sales translate into better core profitability. On the chart, a move above the $139.45 near-term resistance would put the $145.43 52-week high back in focus. A drop below the $130.92 20-day moving average would weaken the current momentum, while $122.36 remains the stated near-term support. The next dated shareholder events are the December 1, 2026 dividend record date and the January 5, 2027 payment of $0.67 per share.
Analyst Consensus
BUY

Based on 21 analyst opinions
Low Target
$135.00
Mean Target
$146.86
High Target
$163.00


Earnings and Financial Data

Sector
Financial Services
Industry
Insurance – Diversified
Employees
19,200
Earnings & Dividends
Next Earnings
Oct 26, 2026
EPS (Trailing)
$14.01
Dividend Yield
175.0%
Payout Ratio
16.4%

Frequently Asked Questions

Is HIG a good stock to buy?
The analyst recommendation is buy, based on 21 analysts. Positive 20-day momentum of 7.85% and a 9.77 P/E support the bullish view, but investors still need to respect the $139.45 resistance level.
What is HIG’s price target?
The average analyst target is $146.86, with estimates ranging from $135.00 to $163.00. The takeaway is that the average and high targets sit above the current $136.82 price, while the low target sits below it.
Is HIG stock expensive?
HIG trades at a P/E ratio of 9.77 and has a market capitalization of $37.06 billion. The takeaway is that the supplied valuation is below ten times earnings.
What is HIG’s 52-week trading range?
The key data lists a 52-week range of $120.33 to $146.07, while the technical price series shows a low of $118.21 and a high of $145.43. The takeaway is that HIG currently sits 65% of the way from the technical low to the technical high.
Is HIG growing revenue?
HIG reports $29.32 billion in revenue and revenue growth of 8.1%. The takeaway is that revenue is expanding at the reported rate.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 27, 2026.