ALTSTATION.IO

The Procter & Gamble Company (PG) Stock Analysis

By Nova Skye | AltStation.io | Updated October 14, 2026

Price
$155.76
Change
+1.78%
Market Cap
$362.05B
Avg Volume
8.4M

Company Overview

Procter & Gamble is a Cincinnati-based consumer defensive giant that has been selling household essentials worldwide since 1837. The company operates across five distinct segments: Beauty, Grooming, Health Care, Fabric & Home Care, and Baby, Feminine & Family Care. Its product lineup is packed with category staples, spanning Tide and Ariel detergents, Pampers diapers, Gillette razors, Crest toothpaste, and Bounty paper towels. P&G sells these goods directly to consumers as well as through mass merchandisers, grocery stores, pharmacies, wholesale distributors, and social ecommerce channels.

P&G is an entrenched market leader whose primary edge is an unmatched portfolio of high-recognition brands like Dawn, Oral-B, Febreze, and Charmin. That massive brand footprint gives the company premium shelf space and leverage across membership clubs, department stores, and mass retail. The main threat to this position is consumer trade-down risk, as private-label alternatives constantly pressure higher-priced legacy products during tight economic stretches. Defending market share across all five segments requires P&G to constantly justify its premium pricing through brand loyalty and distribution breadth.

Right now, P&G relies on broad omni-channel distribution to drive volume across its five established units rather than gambling on unproven categories. The business pairs high-volume, recession-resilient cash cows like Vicks, Pepto-Bismol, and Swiffer with higher-margin personal care lines like SK-II and Olay. By selling everywhere from airport duty-free shops to digital storefronts, P&G keeps its revenue footprint steady across both essential home goods and discretionary beauty care. It remains a textbook defensive anchor built on massive scale and everyday consumer necessity.

Key Financials
Market Cap
$362.05B
Revenue
$87.03B
EBITDA
$24.75B
Gross Margin
50.9%
Profit Margin
18.4%
Revenue Growth
1.5%
Total Cash
$9.94B
Total Debt
$35.02B
Free Cash Flow
$13.28B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
23.53
Forward P/E
21.06
Beta
0.38
52-Week High
$167.25
52-Week Low
$137.62
EPS
$6.62
50-Day Avg
$146.25
200-Day Avg
$147.83
Price/Book
6.79
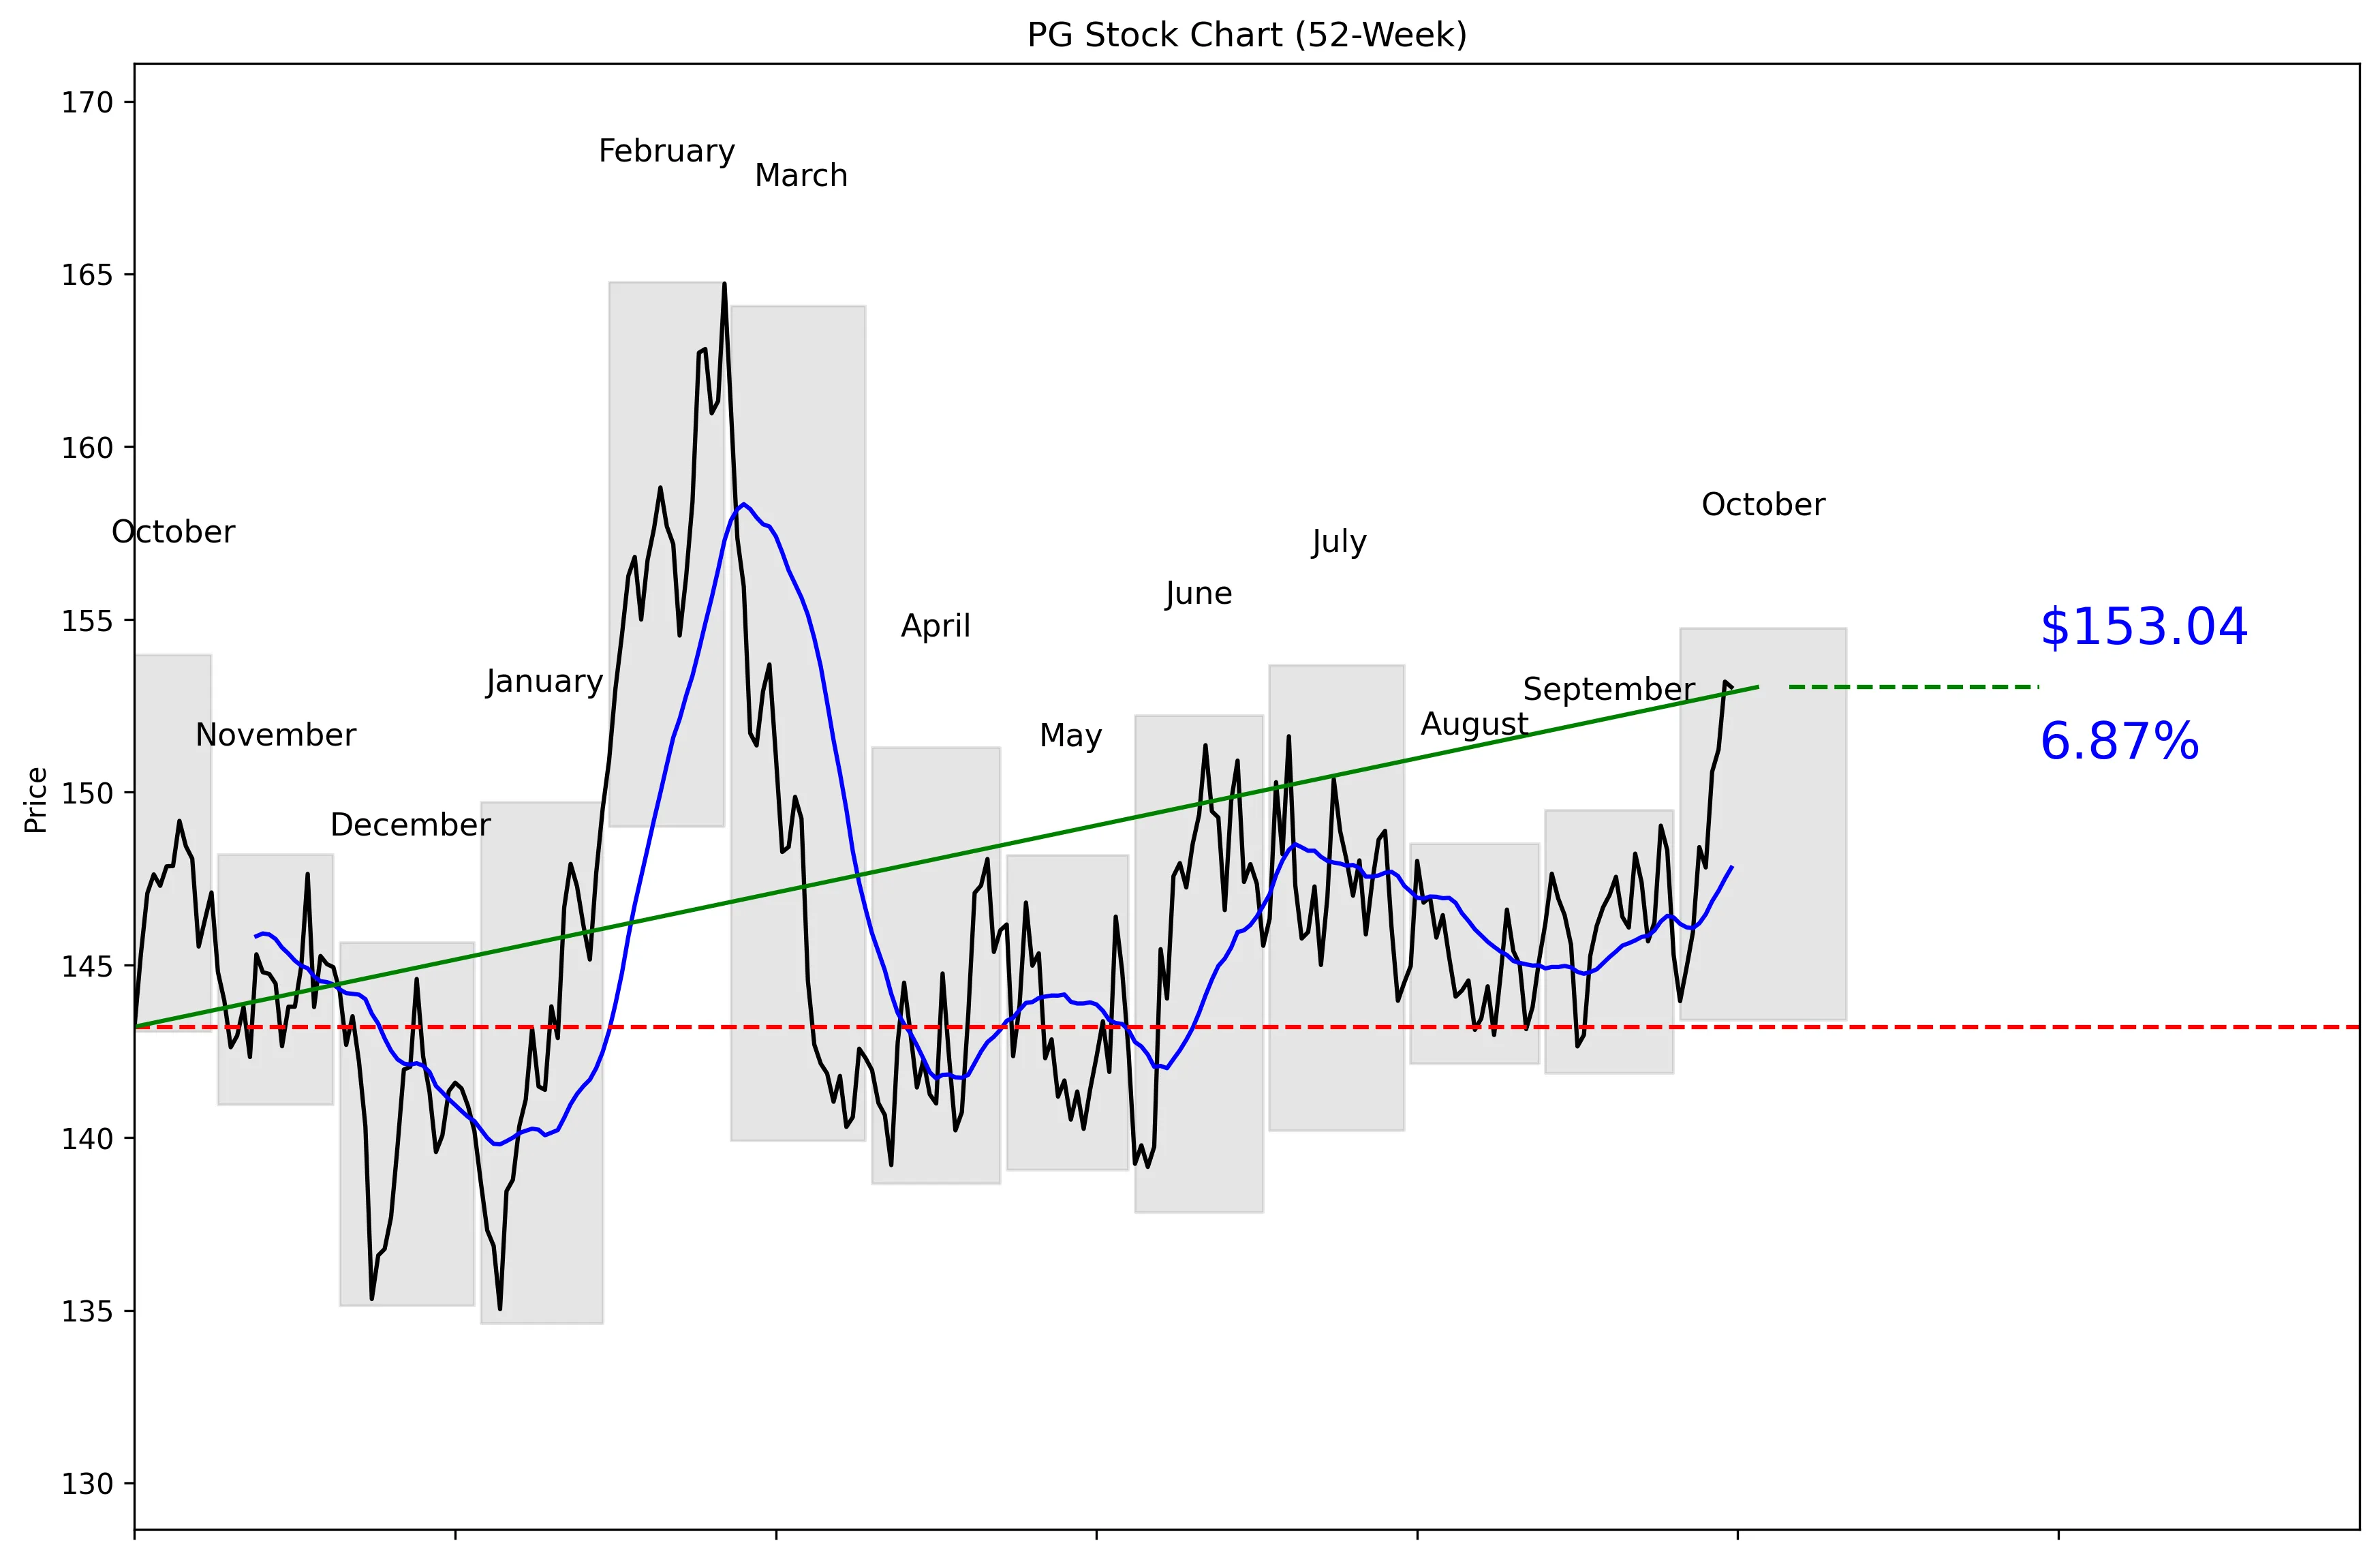
PG 52-Week Stock Chart
Technical Analysis
PG trades at $155.76, 61% of the way from its $134.62 52-week low to its $164.77 high. The stock is 7.12% below that high and 13.68% above the low. Momentum is positive, with gains of 3.12% over five trading days and 4.34% over 20 trading days. Price is 3.54% above the $147.81 20-day moving average. PG has moved above the stated near-term resistance at $153.20, while the 30-day low at $142.64 is the key support level.


Recent News and Developments

Charmin launches wider Ultra Strong sheets

P&G launched Charmin Ultra Strong with Wider Sheets on October 14, calling it the brand’s biggest Ultra Strong innovation in more than a decade. The company says the wider design provides more coverage and can help consumers use up to 50% less toilet paper versus a leading one-ply U.S. bargain brand. Source: P&G Newsroom

P&G maintains its quarterly dividend

P&G declared a quarterly dividend of $1.0885 per share, payable on or after November 16 to shareholders of record on October 23. The company has paid dividends for 136 consecutive years and increased them for 70 consecutive years. Source: P&G Newsroom

P&G backs broader oral-health initiative

P&G Oral Care supported an international consensus calling for oral health to become part of routine health care and public-health policy. The October 12 release said oral diseases affect about 3.5 billion people worldwide and highlighted evidence supporting oscillating-rotating toothbrushes and stannous-fluoride toothpaste. Source: P&G Newsroom


Market Sentiment and Analyst Recommendations

Bull Case
PG generates $87.03 billion in revenue and carries a $362.05 billion market value. Revenue is still growing, although the current rate is only 1.5%. Analysts rate the stock a buy, with 23 analysts contributing to a $161.22 target and a high estimate of $186.00. Recent price action supports the bullish view: the stock gained 3.12% over five trading days and 4.34% over 20 days. Charmin’s wider Ultra Strong sheets and the redesigned Pampers wipes show that P&G is still investing in major consumer brands based on product performance and customer feedback. The reason to buy here is straightforward: momentum is positive, the analyst consensus remains bullish, and the stock still sits below both its $164.77 technical high and the $186.00 high analyst target.
Bear Case
PG trades at 23.53 times earnings while revenue growth is just 1.5%. That is a demanding valuation for a company producing low-single-digit growth. The balance sheet also carries $35.02 billion in total debt against $9.94 billion in cash. At $155.76, the stock is already above the $153.20 near-term resistance level, so part of the recent strength may already be reflected in the price. The average analyst target of $161.22 is only $5.46 above the current price, while the low target of $143.00 is below both the current price and the $147.81 moving average. The bear case is that slow growth, a 23.53 P/E, and limited upside to the average target leave little room for weak execution.
What to Watch
The October 23 dividend record date and payment on or after November 16 are the clearest scheduled events provided. The quarterly payment is $1.0885 per share, and investors should watch whether P&G maintains its record of 136 consecutive years of dividends and 70 consecutive annual increases. Revenue growth is the key operating metric; the current 1.5% rate needs to improve to better support a 23.53 P/E. Watch whether the Charmin wider-sheet launch and updated Pampers wipes produce stronger demand, because product innovation is the most visible growth catalyst in the supplied news. Technically, holding above $153.20 would support the recent breakout, while a move below the $147.81 20-day average would weaken momentum. A break under $142.64 would damage the near-term thesis, while a move toward $161.22 or $164.77 would confirm that buyers remain in control.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$143.00
Mean Target
$161.22
High Target
$186.00


Earnings and Financial Data

Sector
Consumer Defensive
Industry
Household & Personal Products
Employees
104,000
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$6.62
Dividend Yield
284.0%
Payout Ratio
64.3%

Frequently Asked Questions

Is PG a good stock to buy?
The consensus recommendation is buy based on 23 analysts, and the average target is $161.22 versus a current price of $155.76. The takeaway: analysts are bullish, but the average target offers limited price appreciation.
What is PG’s price target?
The average analyst target is $161.22, with estimates ranging from $143.00 to $186.00. The takeaway: Wall Street’s outlook spans meaningful downside and upside.
Is PG stock overvalued?
PG trades at a P/E ratio of 23.53 while revenue growth is 1.5%. The takeaway: the valuation looks demanding relative to the reported growth rate.
What are PG’s support and resistance levels?
Near-term support is $142.64, and the stated near-term resistance is $153.20. The takeaway: PG is currently above resistance at $155.76, making $153.20 the first level to watch on a pullback.
How strong is PG’s balance sheet?
PG has $9.94 billion in total cash and $35.02 billion in total debt. The takeaway: debt substantially exceeds available cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 14, 2026.