ALTSTATION.IO

Ventas, Inc. (VTR) Stock Analysis

By Nova Skye | AltStation.io | Updated October 29, 2026

Price
$80.58
Change
-3.31%
Market Cap
$41.34B
Avg Volume
3.6M

Company Overview

Ventas is a real estate investment trust based in Chicago, Illinois, that buys and operates healthcare properties across North America and the United Kingdom. Incorporated in 1983, the company holds an S&P 500 portfolio of approximately 1,450 properties. Its core revenue driver is senior housing, which accounts for more than 900 communities and represents over 62% of its total property count. The remainder of its business comes from leasing outpatient medical buildings, life science research centers, and specialized healthcare facilities to medical operators and aging residents.

Ventas sits as a dominant market leader in healthcare real estate, sharing the top tier of the sector with its chief competitor, Welltower. The company’s primary edge is its massive scale and its proprietary Ventas OI platform, which uses data insights to optimize occupancy, pricing, and operating performance across its portfolio. That technological edge gives Ventas an advantage over smaller, fragmented competitors that lack centralized analytics. Its biggest operational risk comes from rising labor costs and staffing shortages at senior care communities, which can compress operating margins if expenses outpace rent growth.

Right now, Ventas is in aggressive growth mode as demand for senior housing outstrips limited new supply. The company produced double-digit same-store cash net operating income growth above 15% in its senior housing operating portfolio, bolstered by 300 basis points of occupancy gains. Management backed this momentum by completing over $2 billion in senior housing investments in 2024 and another $2.5 billion in 2025. Ventas is not playing defense; it is actively deploying capital to capture high-margin cash flow from an accelerating aging demographic.

Key Financials
Market Cap
$41.34B
Revenue
$6.42B
EBITDA
$2.38B
Gross Margin
40.0%
Profit Margin
4.1%
Revenue Growth
21.7%
Total Cash
$198.96M
Total Debt
$12.92B
Free Cash Flow
$1.49B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
149.23
Forward P/E
102.01
Beta
0.74
52-Week High
$101.60
52-Week Low
$68.15
EPS
$0.54
50-Day Avg
$87.66
200-Day Avg
$86.44
Price/Book
3.06
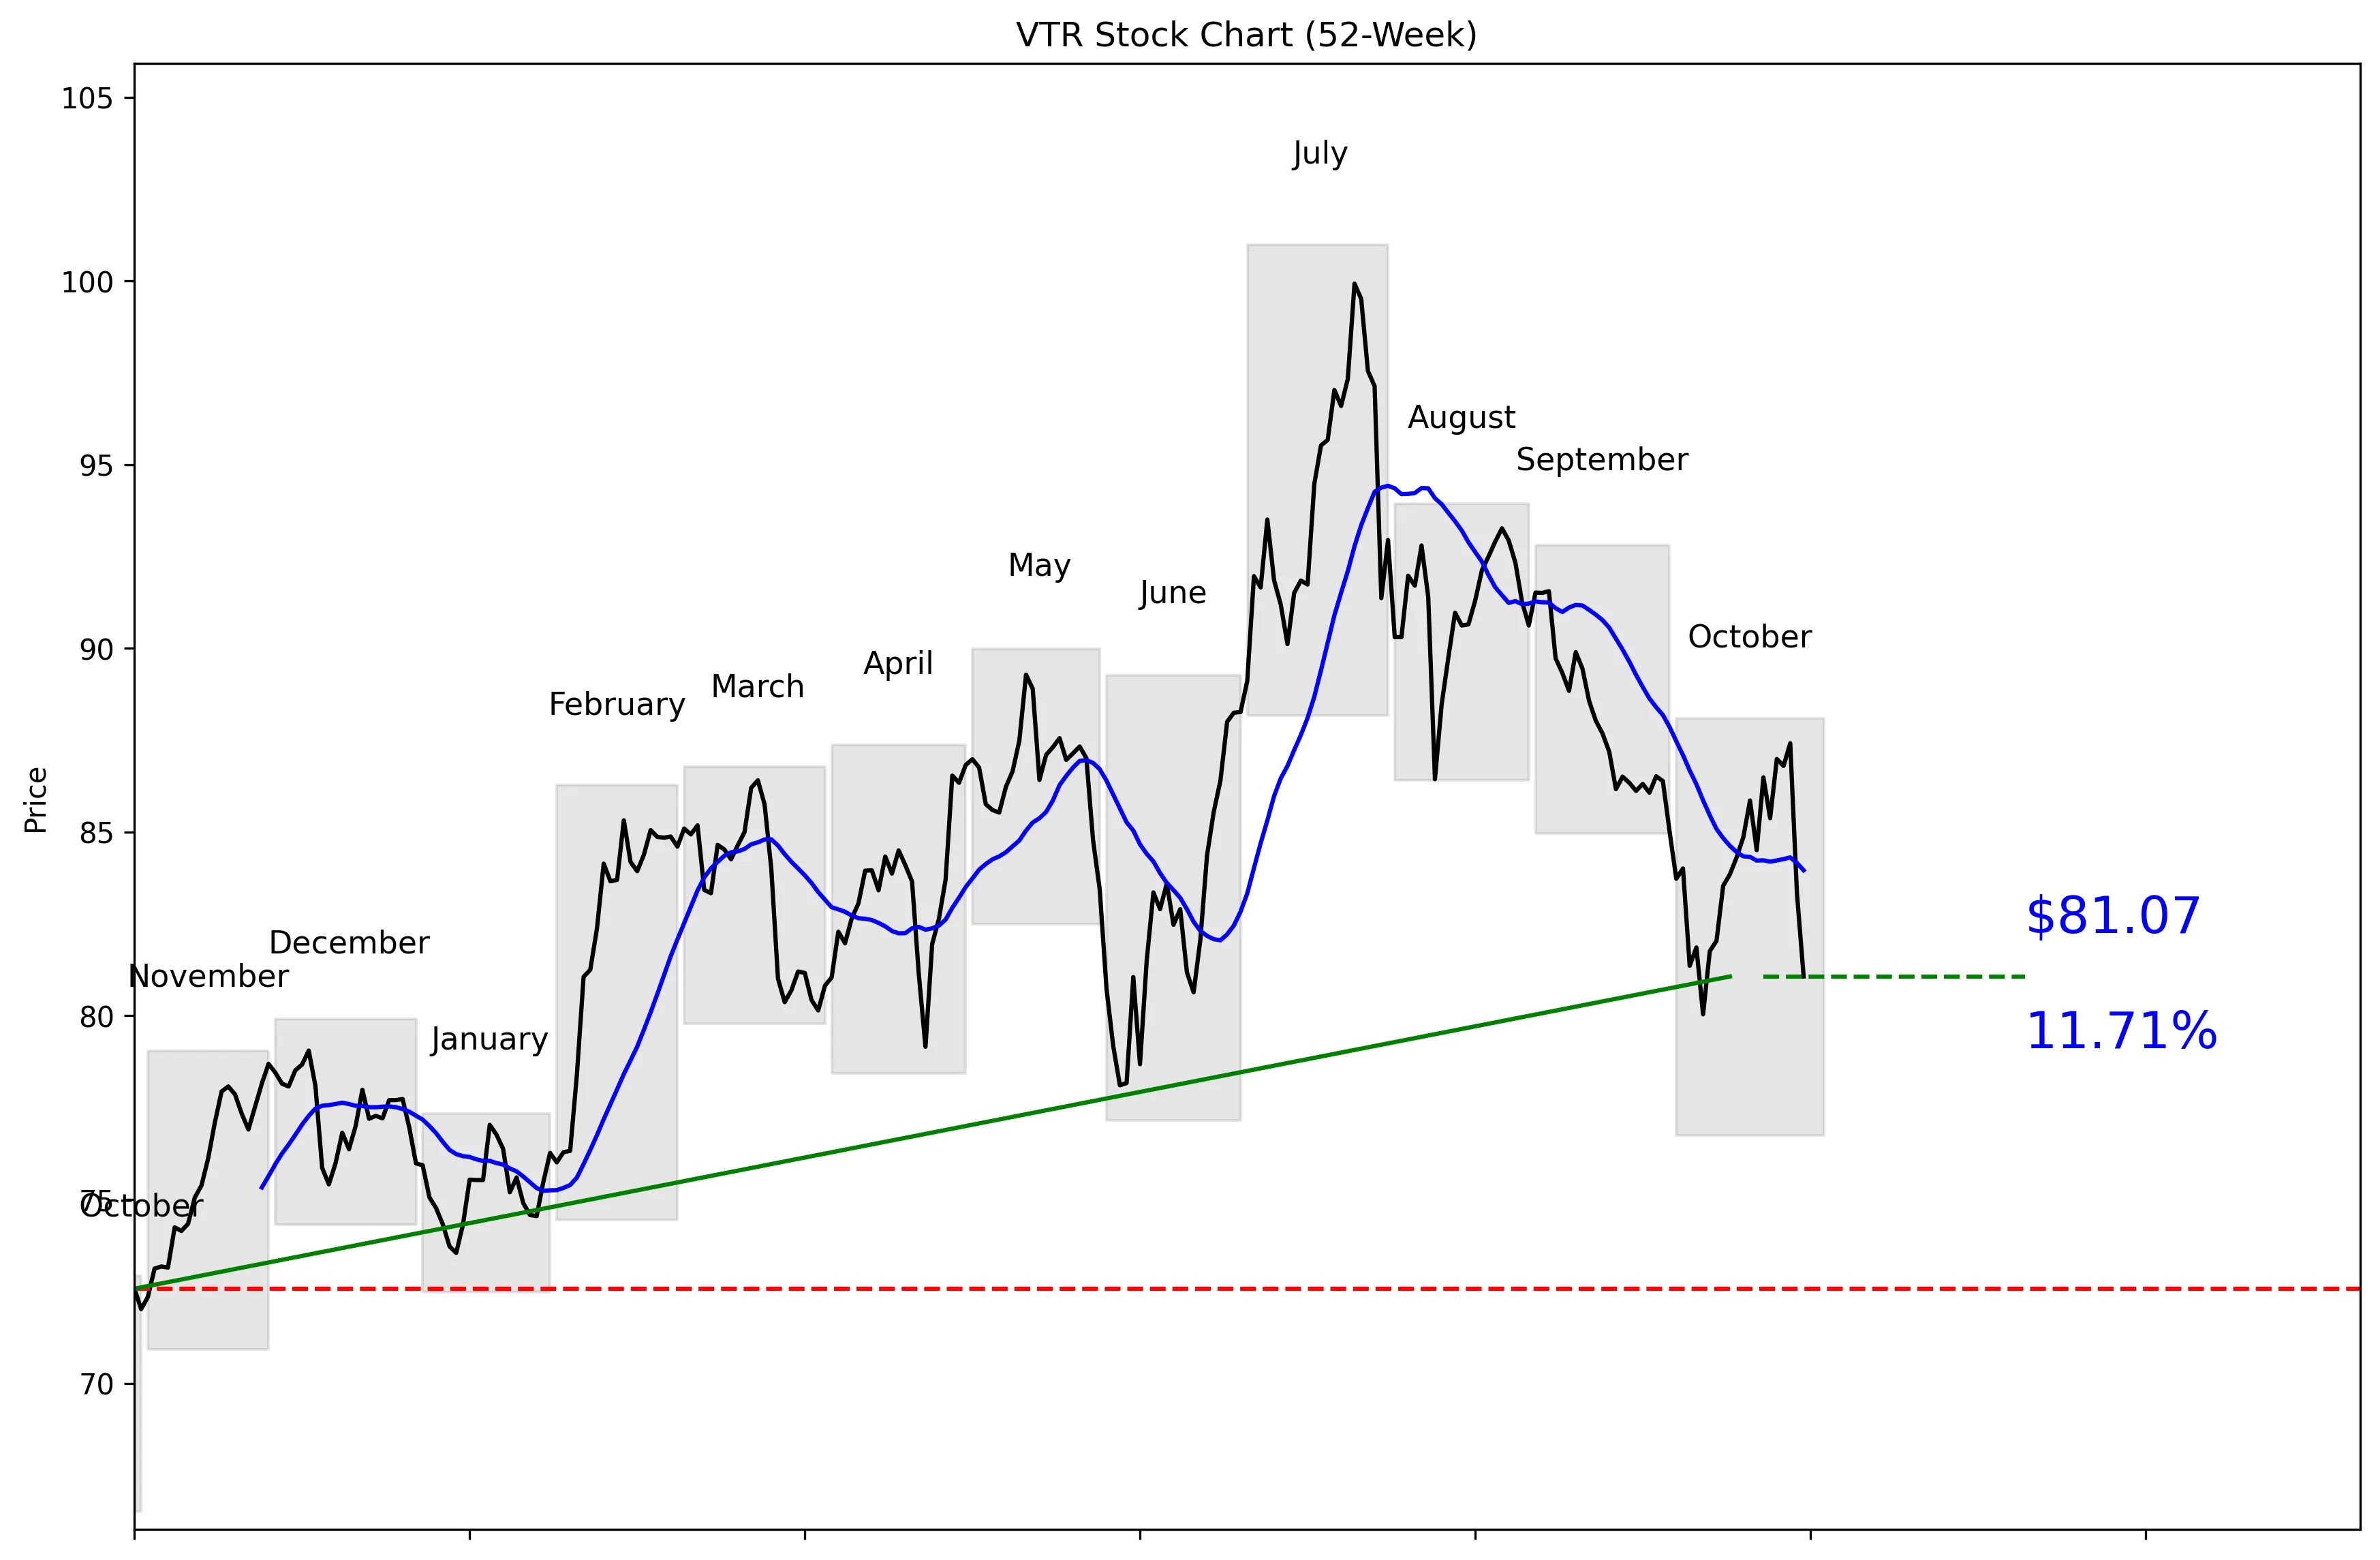
VTR 52-Week Stock Chart
Technical Analysis
VTR trades at $80.58, 42% of the way from its 52-week low of $66.51 to its 52-week high of $100.99. The stock is 19.73% below that high but remains 21.89% above the low. Price sits 3.44% below the 20-day moving average of $83.96, confirming weak short-term momentum. Shares have lost 5.05% over five trading days and 4.65% over 20 trading days. Near-term support is $80.04, while resistance sits at $87.42.


Recent News and Developments

Ventas lifts 2026 guidance after stronger Q3

Q3 normalized FFO rose 10% year over year to $0.99 per share, while attributable net income fell 7% to $0.13 per share. Ventas raised its 2026 normalized FFO range to $3.87-$3.90 per share and its net-income range to $0.64-$0.67. Source: Ventas Investor Relations

Senior housing NOI jumps as Ventas deploys $5.2 billion

Senior Housing Operating Portfolio same-store cash NOI increased 16% year over year, with U.S. NOI up 17% and average U.S. occupancy exceeding 90%. Ventas closed $1.2 billion of senior housing investments during Q3 and $5.2 billion year to date. Source: Ventas Investor Relations

Analysts keep bullish ratings but cut price targets

Cantor Fitzgerald reiterated Buy on October 29 but cut its Ventas target from $102 to $95. Wells Fargo maintained Buy while lowering its target from $104 to $96, while Evercore ISI kept Buy with a $100 target and Scotiabank maintained Hold at $95. Source: Stock Analysis


Market Sentiment and Analyst Recommendations

Bull Case
Ventas is growing revenue at 21.7%, with total revenue reaching $6.42 billion. Q3 normalized FFO increased 10% year over year to $0.99 per share, leading management to raise 2026 normalized FFO guidance to $3.87-$3.90. Senior Housing Operating Portfolio same-store cash NOI grew 16%, including 17% growth in the U.S. Average U.S. occupancy exceeded 90%, showing that demand and operating performance remain strong. Ventas also deployed $5.2 billion into senior housing investments year to date, including $1.2 billion during Q3. At $80.58, the stock is below the $99.73 analyst target, and all 22 analysts collectively rate it a buy. The bull case is straightforward: strong senior housing growth, higher guidance, and a meaningful gap between the current price and analyst expectations.
Bear Case
The valuation is difficult to defend at a P/E of 149.23. Ventas carries $12.92 billion in debt against just $198.96 million in cash, leaving little balance-sheet margin if operating momentum weakens. Attributable net income declined 7% in Q3 to $0.13 per share even as normalized FFO increased. Analysts remain bullish, but Cantor Fitzgerald cut its target from $102 to $95 and Wells Fargo lowered its target from $104 to $96. The stock is already down 19.73% from its 52-week high and remains below its $83.96 moving average. The biggest risk is that Ventas has deployed $5.2 billion while carrying substantial debt, so those investments need to generate durable income growth. At this valuation, solid execution is already expected; a slowdown in NOI, occupancy, or FFO would weaken the case quickly.
What to Watch
The next quarter needs to confirm that normalized FFO remains on track for the raised 2026 range of $3.87-$3.90 per share. Investors should also track whether attributable net income reaches the updated $0.64-$0.67 range after falling 7% in Q3. Senior housing same-store cash NOI growth is the key operating metric following the latest 16% increase. U.S. occupancy needs to remain above 90%, because that level supports the current senior housing growth thesis. Watch how the $5.2 billion deployed year to date translates into FFO and net-income growth rather than simply adding scale and debt exposure. On the chart, a break below $80.04 would weaken the setup, while a move through $87.42 would signal that buyers have regained control. Analyst revisions also matter after the October 29 target cuts to $95 and $96 despite continued Buy ratings.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$90.00
Mean Target
$99.73
High Target
$113.00


Earnings and Financial Data

Sector
Real Estate
Industry
REIT – Healthcare Facilities
Employees
542
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$0.54
Dividend Yield
238.0%
Payout Ratio
370.4%

Frequently Asked Questions

Is VTR a good stock to buy?
The consensus recommendation is buy based on 22 analysts, and the average target is $99.73 versus a current price of $80.58. Takeaway: Analysts are bullish, but the 149.23 P/E makes valuation a major consideration.
What is VTR’s price target?
The average analyst target is $99.73, with estimates ranging from $90.00 to $113.00. Takeaway: Every listed target is above the current $80.58 price.
What are VTR’s support and resistance levels?
Near-term support is the 30-day low of $80.04, while resistance is the 30-day high of $87.42. Takeaway: VTR is trading close to support at $80.58.
How is VTR stock performing technically?
VTR is 3.44% below its 20-day moving average of $83.96, with five-day momentum of negative 5.05% and 20-day momentum of negative 4.65%. Takeaway: The short-term technical trend is weak.
Does VTR pay a dividend?
The provided data does not include a dividend rate or dividend yield. Takeaway: Dividend income cannot be evaluated from the available figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 29, 2026.