ALTSTATION.IO

Waters Corporation (WAT) Stock Analysis

By Nova Skye | AltStation.io | Updated October 04, 2026

Price
$426.35
Change
+0.19%
Market Cap
$41.86B
Avg Volume
765.3K

Company Overview

Waters Corporation is a laboratory technology company founded in 1958 and headquartered in Milford, Massachusetts, operating in the Healthcare sector within Diagnostics & Research. The business operates through two segments, Waters and TA, manufacturing liquid chromatography tools, mass spectrometry instruments, thermal analysis devices, and lab informatics software. It pairs those hardware platforms with consumable products like chromatography columns that laboratories replace continuously. Its customer base spans pharmaceutical firms, clinical labs, industrial manufacturers, and government research bodies focused on drug development, quality control, and safety testing.

Waters is a market leader in analytical workflow systems, deriving roughly 59% of its business directly from the pharmaceutical industry. Its primary competitive advantage is a razor-and-blade model where recurring revenue from servicing and proprietary consumables makes up over 50% of total sales. Once a pharmaceutical lab standardizes its quality control methods on Waters software and hardware, switching to competitors like Agilent Technologies, Thermo Fisher Scientific, or Danaher is costly and operationally disruptive. The main risk is exposure to cyclical swings in biotech funding and big pharma capital expenditure cuts.

Waters is currently navigating a period of flat baseline growth, recording $2.958 billion in revenue for 2024 compared to $2.96 billion in 2023. To push into higher-margin large-molecule testing, the company completed a $1.36 billion buyout of Wyatt Technology in May 2023 to capture demand in cell and gene therapy quality assurance. While instrument sales faced headwinds across the industry, recurring revenue rose 9% in constant currency in the final quarter of 2024. My take is that Waters remains one of the highest-quality defensive plays in life sciences tools, using steady consumable cash flows to weather hardware slowdowns while expanding into biologics.

Key Financials
Market Cap
$41.86B
Revenue
$4.64B
EBITDA
$1.45B
Gross Margin
56.3%
Profit Margin
3.6%
Revenue Growth
113.4%
Total Cash
$539.00M
Total Debt
$5.48B
Free Cash Flow
-$142.07M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
107.66
Forward P/E
25.78
Beta
1.19
52-Week High
$448.21
52-Week Low
$282.77
EPS
$3.96
50-Day Avg
$409.33
200-Day Avg
$363.35
Price/Book
2.76
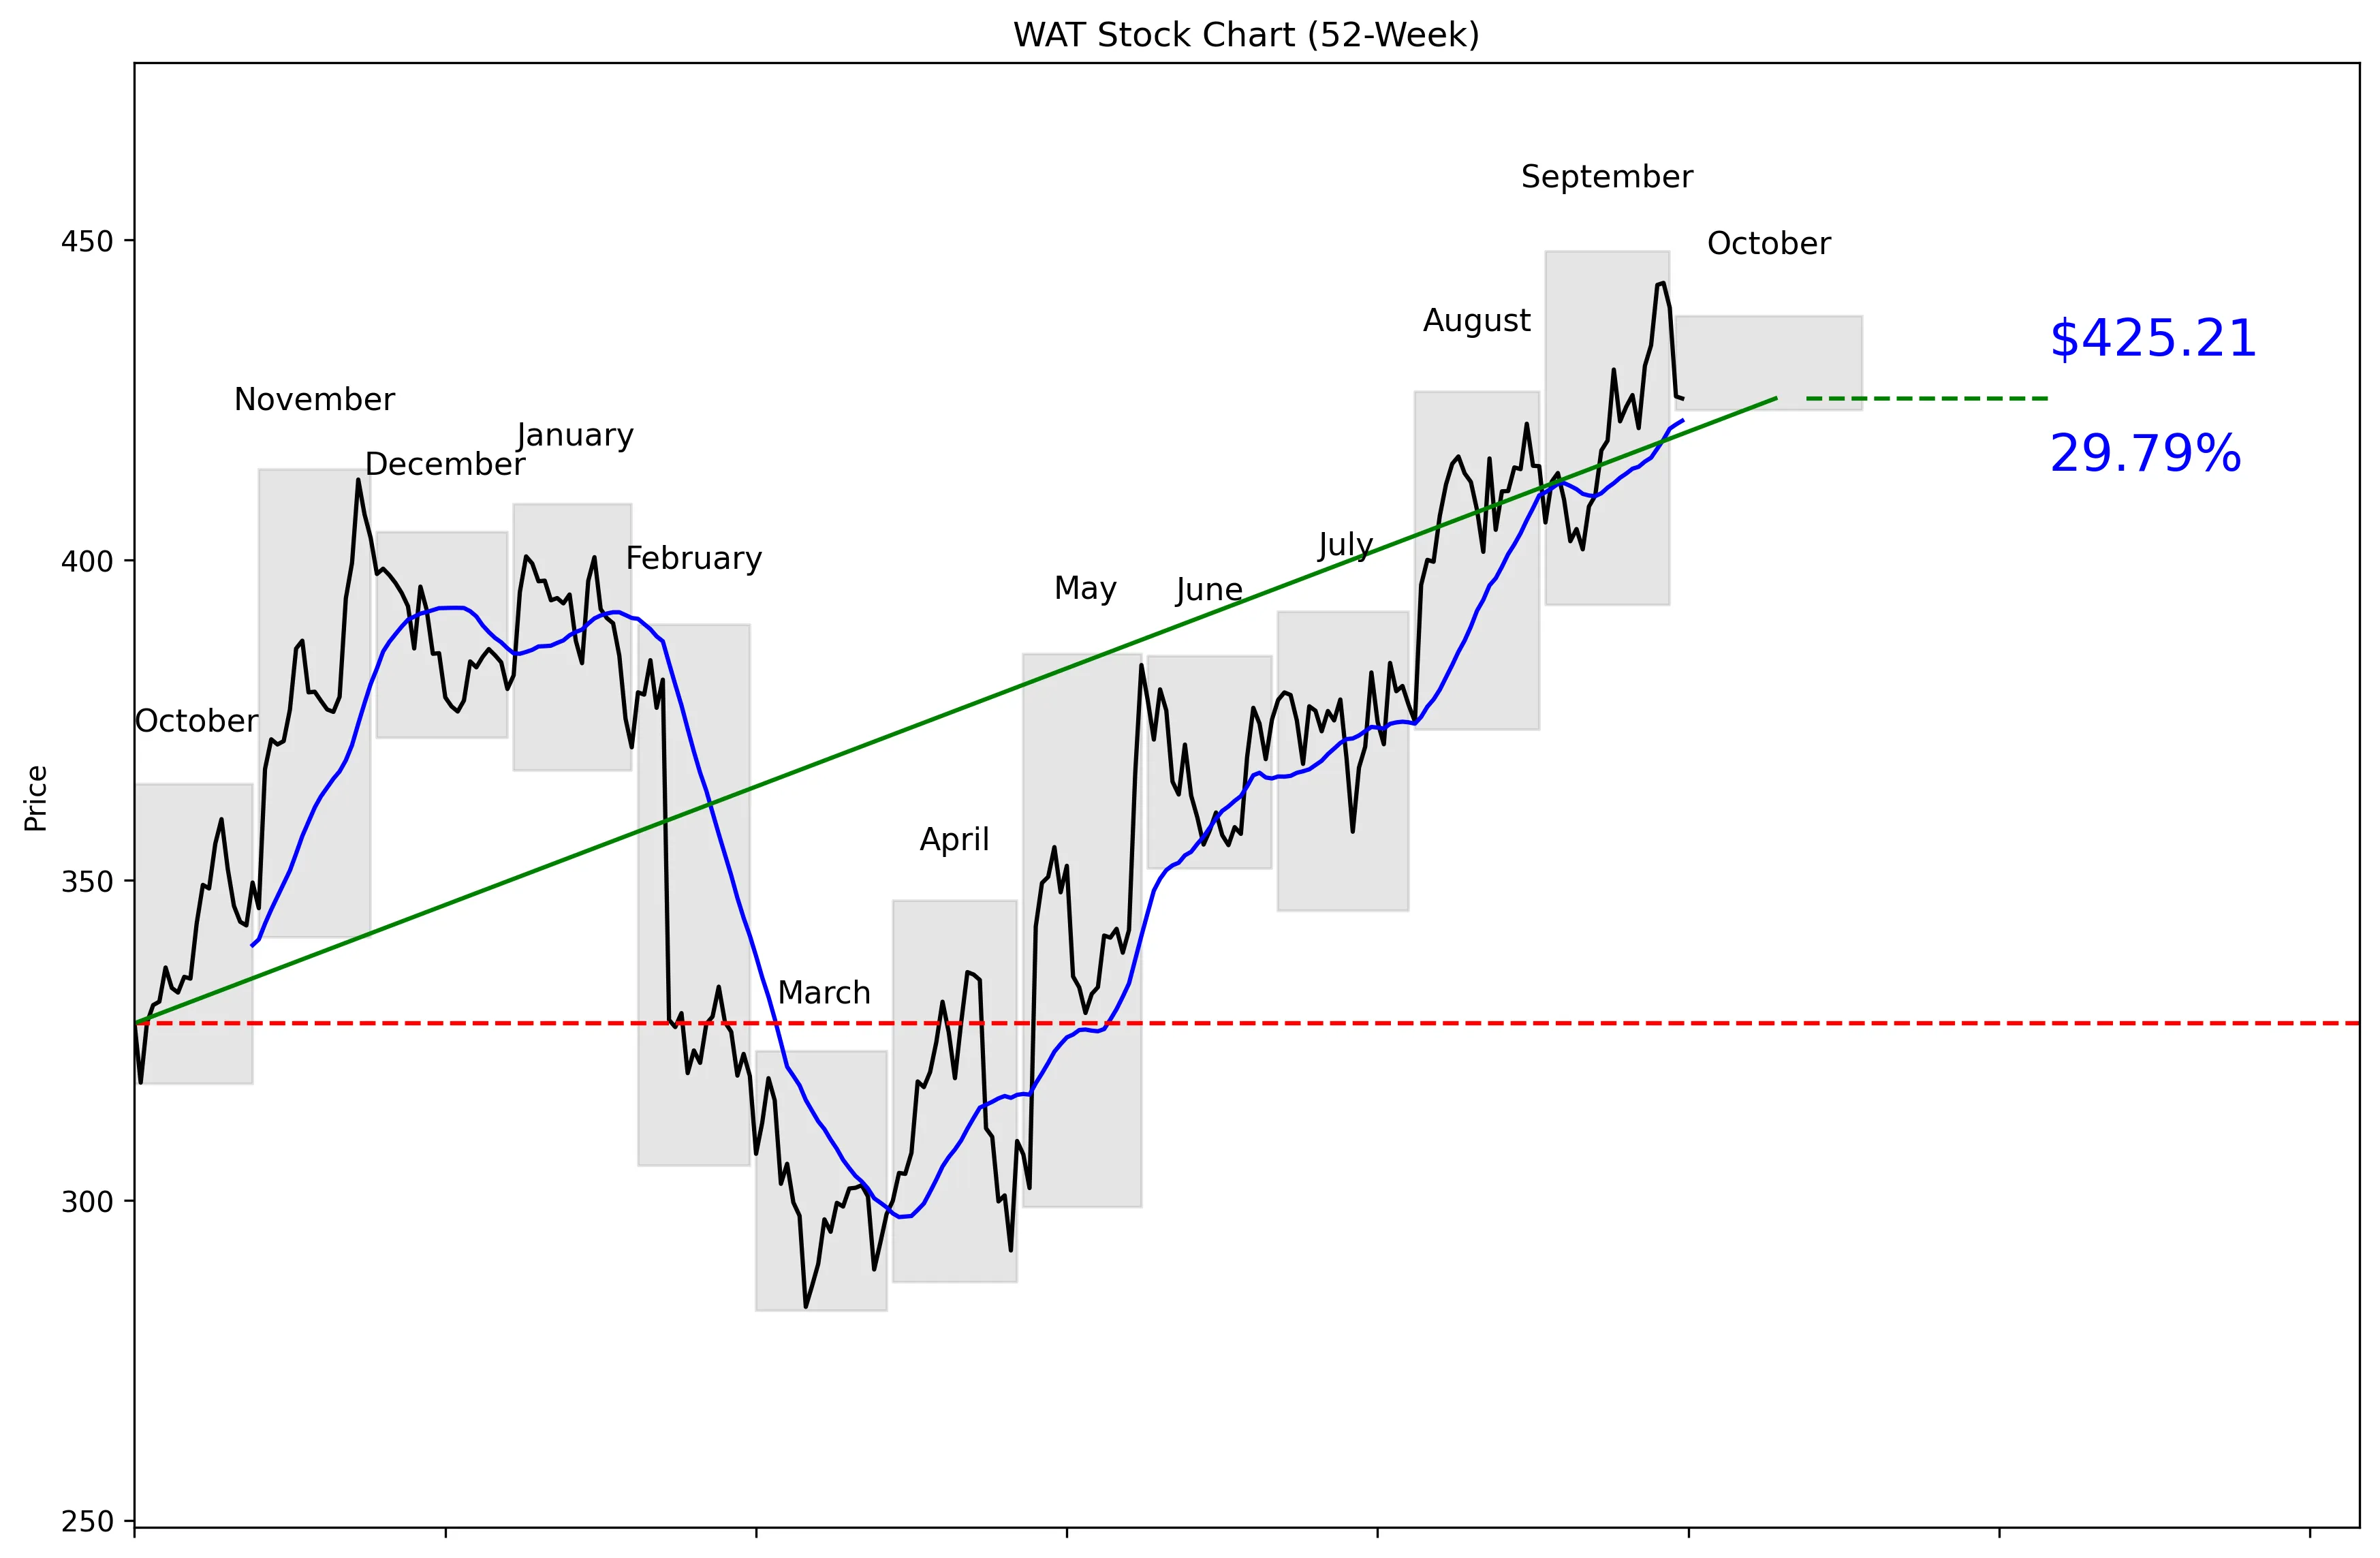
WAT 52-Week Stock Chart
Technical Analysis
WAT trades at $426.35, 86% of the way from its 52-week low of $282.77 to its high of $448.21. The stock is 5.13% below that high and 50.37% above the low, so the longer-term trend remains strong. Price is 0.83% above the 20-day moving average of $421.73, while 20-day momentum is positive at 2.82%. Short-term momentum has weakened, with WAT down 1.92% over the past five trading days. Near-term support is $401.64, while $443.26 is the resistance level to beat.


Recent News and Developments

Guggenheim lifts Waters target to $490

Guggenheim maintained its Buy rating on October 1 and raised its price target from $440 to $490, an 11.36% increase. The bullish target did not prevent WAT from falling 3.15% that day. Source: GuruFocus

Waters sets November 3 earnings call

Waters scheduled its third-quarter 2026 earnings call for November 3 at 8:00 a.m. Eastern Time. No new financial results or guidance accompanied the October 1 announcement. Source: PR Newswire

WAT ends a volatile week down 1.92%

WAT rose 2.17% to $442.94 on September 28, then fell 3.15% on October 1 and closed at $425.21 on October 2. That left the stock 1.92% below its September 25 close of $433.54. Source: Stock Analysis


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 113.4% is the strongest argument for owning WAT. Revenue stands at $4.64 billion, and investors are clearly paying for continued expansion. The analyst consensus is buy across 23 analysts, with a $448.91 target and a high estimate of $515. Guggenheim reinforced that bullish view on October 1 by maintaining its Buy rating and raising its target from $440 to $490. The stock remains above its $421.73 moving average despite recent volatility, and its 2.82% 20-day momentum is still positive. The bull case is straightforward: strong reported growth, positive analyst sentiment, and multiple targets above the current $426.35 price support further upside.
Bear Case
The valuation is demanding at 107.66 times earnings. That multiple leaves little room for weak growth, disappointing earnings, or softer guidance. Total debt of $5.48 billion is more than ten times the company’s $539 million in cash. WAT is also already 86% through its 52-week range and only 5.13% below the $448.21 high, so much of the optimism may already be reflected in the price. The stock fell 3.15% on October 1 despite Guggenheim raising its target to $490, showing that bullish analyst action is not enough to guarantee buying. A break below the $421.73 moving average would weaken the near-term setup, while a move toward $401.64 support would confirm that sellers have gained control.
What to Watch
The next major catalyst is Waters’ third-quarter 2026 earnings call on November 3 at 8:00 a.m. Eastern Time. The October 1 announcement included no new results or guidance, so the earnings release will carry the burden of validating the current valuation. Investors should focus on whether the reported 113.4% revenue growth remains strong enough to support a P/E of 107.66. Price action around the $443.26 resistance level will show whether buyers can challenge the $448.21 52-week high. On the downside, $421.73 is the first trend marker, followed by support at $401.64. The analyst target range of $349 to $515 shows wide disagreement, so updated targets after earnings could materially change the outlook. A sustained breakout above $443.26 would strengthen the bull case, while a loss of $401.64 would damage it.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$349.00
Mean Target
$448.91
High Target
$515.00


Earnings and Financial Data

Sector
Healthcare
Industry
Diagnostics & Research
Employees
16,000
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$3.96
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is WAT a good stock to buy?
The recommendation is buy based on 23 analysts, and revenue growth is 113.4%. The clear takeaway is that analysts are bullish, but the 107.66 P/E makes WAT an expensive stock.
What is WAT’s price target?
The analyst target is $448.91, with estimates ranging from $349 to $515. The takeaway is that the consensus target sits above the current $426.35 price, but analyst expectations vary widely.
What is WAT’s 52-week range?
WAT’s 52-week range is $282.77 to $448.21, and the stock is currently 86% of the way from the low to the high. The takeaway is that WAT trades much closer to its annual high than its annual low.
What are WAT’s support and resistance levels?
Near-term support is the 30-day low of $401.64, while near-term resistance is the 30-day high of $443.26. The takeaway is that these are the key levels for judging WAT’s next move.
Does WAT pay a dividend?
The provided data does not include dividend information. The takeaway is that no conclusion about WAT’s dividend can be made from these figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 04, 2026.