ALTSTATION.IO

Wells Fargo & Company (WFC) Stock Analysis

By Nova Skye | AltStation.io | Updated October 08, 2026

Price
$81.68
Change
+1.77%
Market Cap
$247.00B
Avg Volume
14.3M

Company Overview

Wells Fargo & Company is a financial powerhouse based in San Francisco, California, operating in the diversified banking industry within the financial services sector since its founding in 1852. The firm sells checking and savings accounts, credit cards, mortgages, auto loans, and wealth management to retail consumers and small businesses. On the institutional side, it provides commercial real estate loans, treasury management, and capital markets solutions to corporate, institutional, and municipal clients. All operations run through four core divisions: Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth and Investment Management.

Wells Fargo sits as a tier-one market leader in United States retail and commercial banking rather than a niche operator. Its primary competitive advantage is its broad domestic footprint across everyday banking and lending, which locks in sticky consumer deposits and loan volume. The key pressure comes from diversified mega-bank competitors like JPMorgan Chase and Bank of America, which hold aggressive market share in investment banking and capital markets. Outside of competitive pressure, heavy concentrations in personal lending, auto loans, and commercial real estate keep credit risk front and center.

The company is currently pivoting to strengthen its fee-generating businesses and rebalance its revenue mix away from purely spread-dependent lending. Growth priorities are focused on expanding its Corporate and Investment Banking unit alongside its Wealth and Investment Management division. Wells Fargo is aggressively pruning operational bloat while trying to extract higher returns from private, public, and municipal corporate banking clients. The bottom line is simple: if execution holds in commercial finance and capital markets, Wells Fargo solidifies its position as a streamlined cash-generation engine.

Key Financials
Market Cap
$247.00B
Revenue
$83.03B
EBITDA
N/A
Gross Margin
0.0%
Profit Margin
27.2%
Revenue Growth
9.5%
Total Cash
$496.41B
Total Debt
$478.47B
Free Cash Flow
N/A


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
11.87
Forward P/E
10.21
Beta
0.95
52-Week High
$97.76
52-Week Low
$72.78
EPS
$6.88
50-Day Avg
$85.83
200-Day Avg
$84.58
Price/Book
1.50
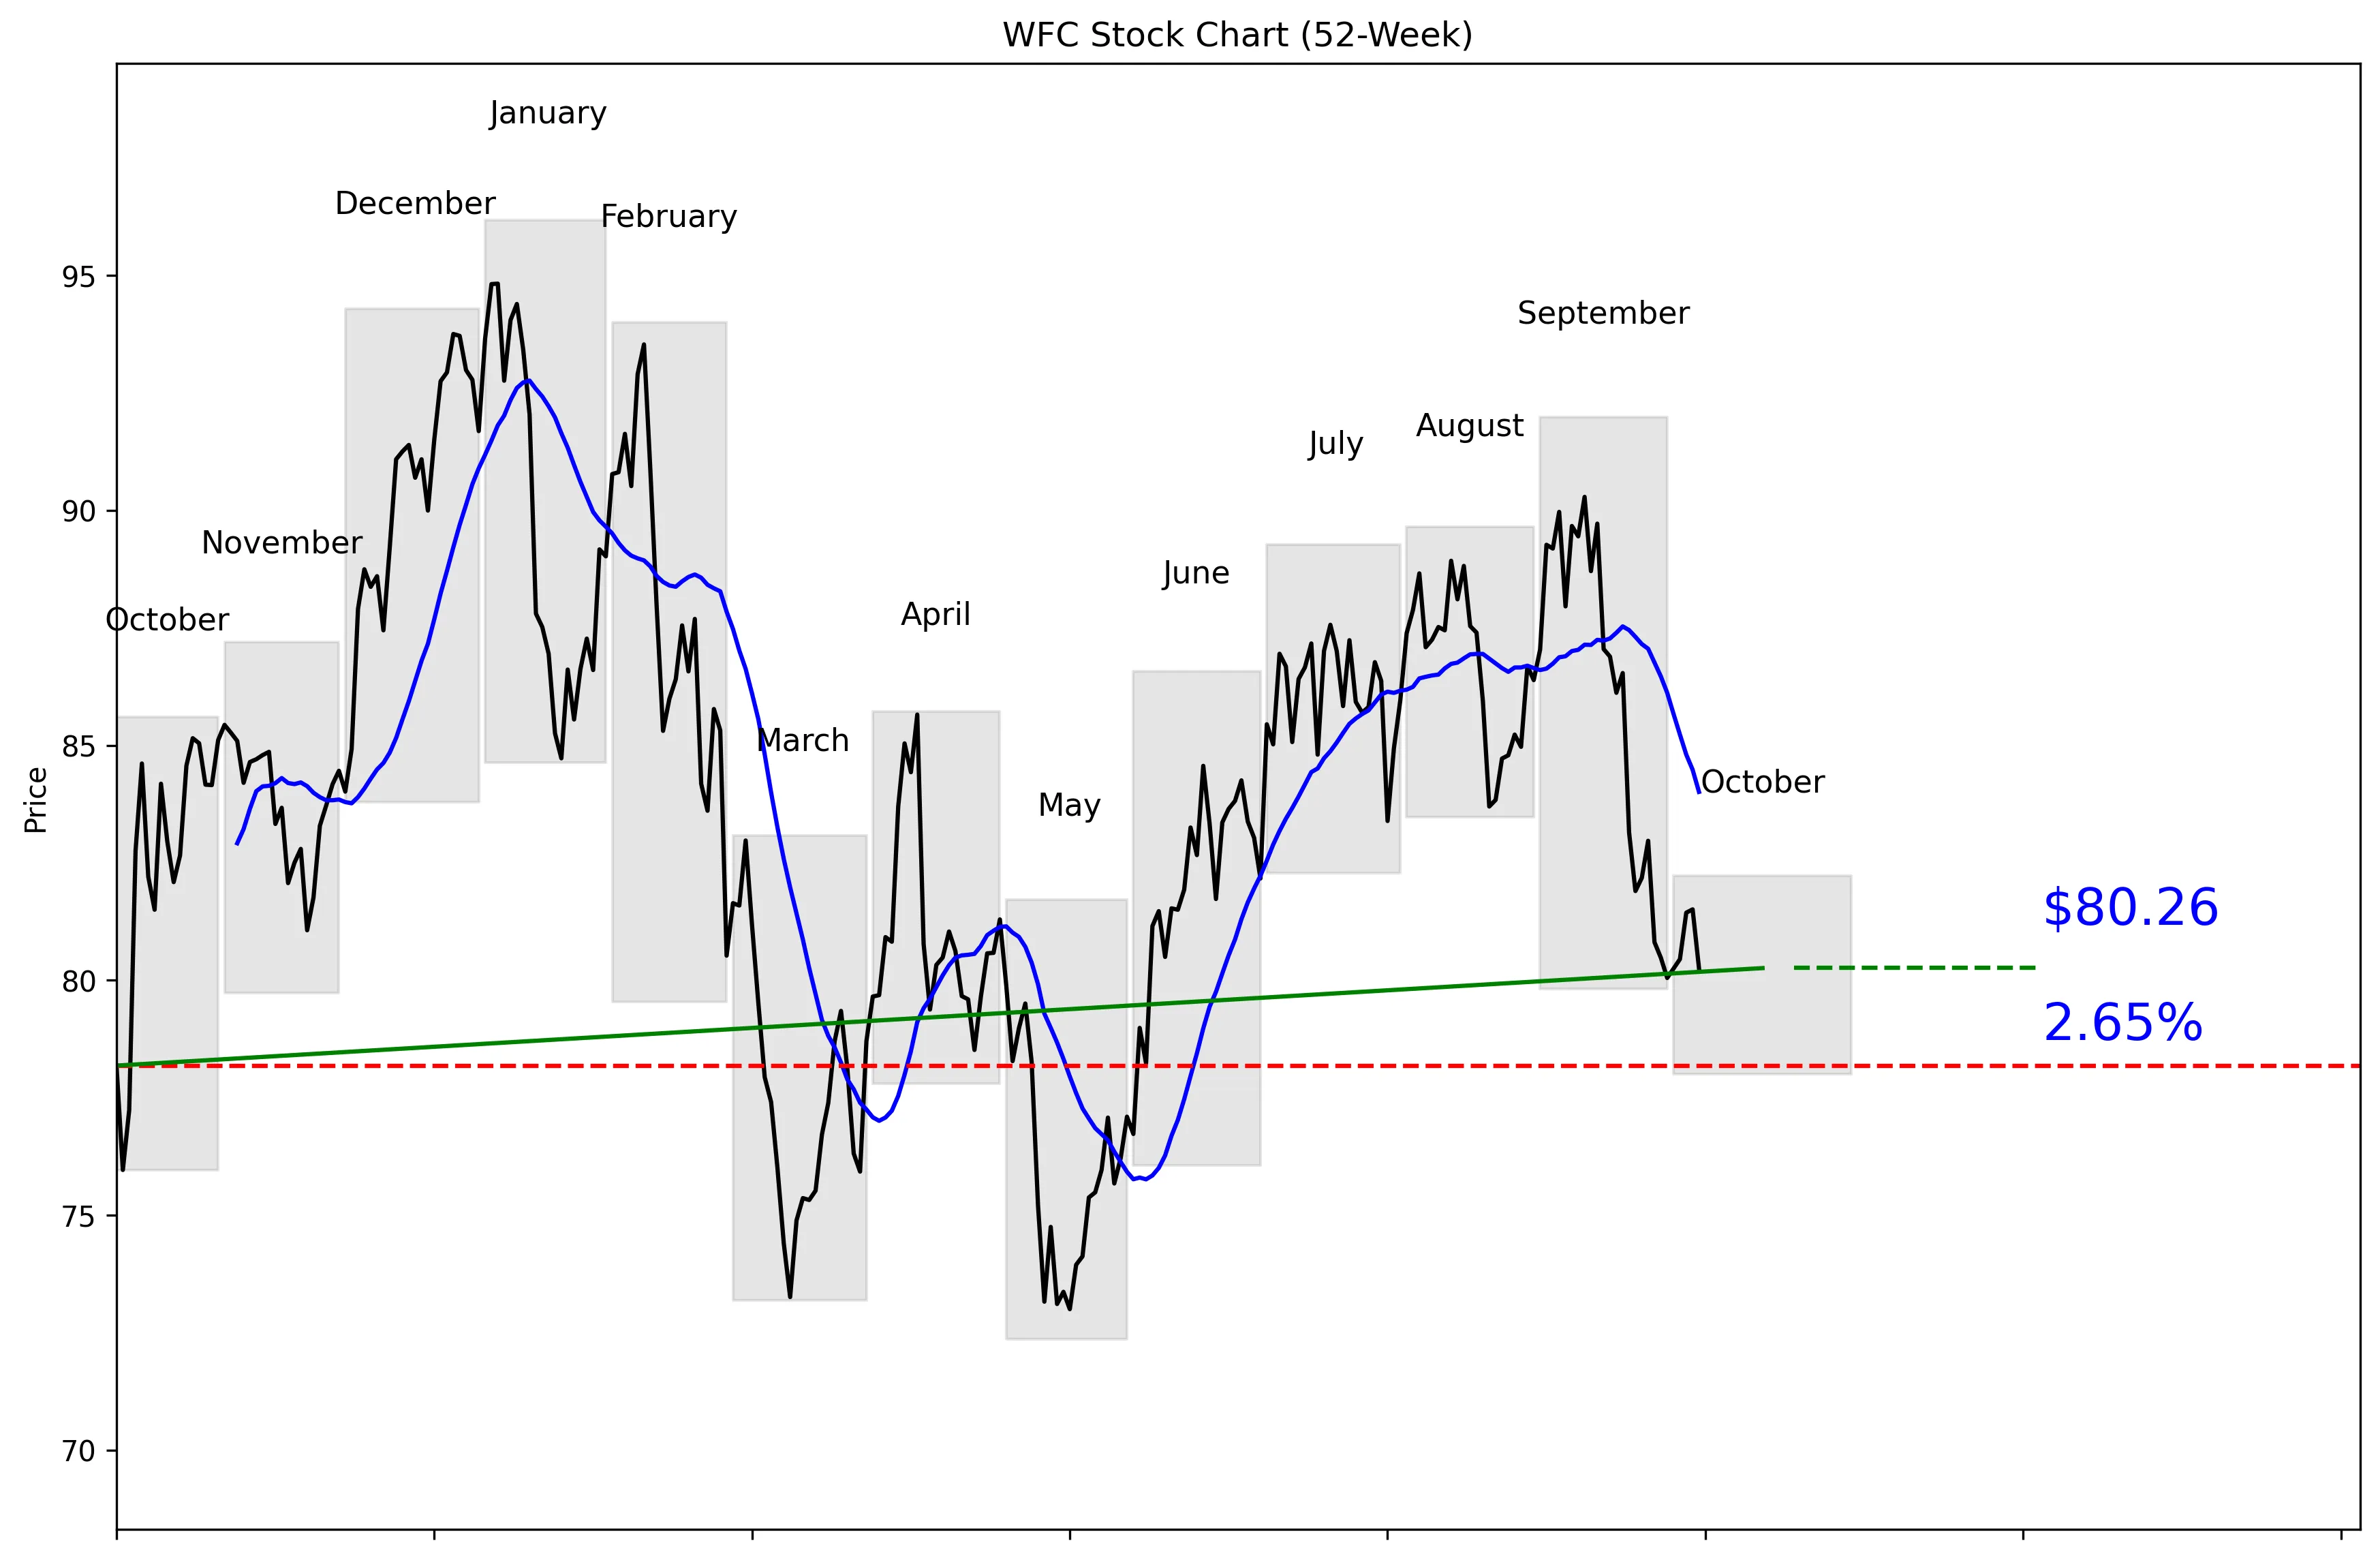
WFC 52-Week Stock Chart
Technical Analysis
WFC trades at $81.68, 33% of the way from its $72.36 52-week low to its $96.18 high. The stock is 16.55% below that high and 10.91% above the low. Price sits 4.46% below the 20-day moving average of $84.01, showing a weak short-term trend. Five-day momentum is positive at 0.26%, but 20-day momentum remains sharply negative at 10.49%. Near-term support is $80.05, while resistance is $90.29.


Recent News and Developments

HUD opens fair-lending probe into Wells Fargo

HUD is investigating whether Wells Fargo’s programs to increase Black homeownership violated the Fair Housing Act by favoring certain borrowers based on race. WFC fell 1.53% on October 7, making the probe the week’s clearest downside catalyst. Source: U.S. Department of Housing and Urban Development

Analysts split on WFC but keep a bullish tilt

Morgan Stanley upgraded WFC from Equal-Weight to Overweight with a $102 target, while TD Cowen reinstated coverage at Buy with a $95 target. Goldman Sachs cut its target from $107 to $96, UBS trimmed from $104 to $102, and JPMorgan lowered its target from $96 to $92. Source: Benzinga

Wells Fargo adds mobile debit-card personalization

Wells Fargo launched Mobile Card Design Studio, allowing customers to upload photos or select gallery designs for eligible debit cards through its mobile app. It is a useful customer-retention feature, but not a meaningful near-term earnings catalyst. Source: PYMNTS


Market Sentiment and Analyst Recommendations

Bull Case
Wells Fargo generated $83.03 billion in revenue, with revenue growth of 9.5%. The stock trades at 11.87 times earnings, which is not demanding if that growth continues. The analyst consensus is buy across 23 analysts, with an average target of $99.20. That target represents 21.45% upside from $81.68, while the high target of $115.00 implies 40.79% upside. Total cash of $496.41 billion exceeds total debt of $478.47 billion. Third-quarter results on October 13 are the next major catalyst, and a strong report could help close the gap between the current price and analyst targets.
Bear Case
WFC remains below its $84.01 20-day moving average, and 20-day momentum is negative 10.49%. The stock is also 16.55% below its 52-week high, so the recent trend is clearly weak. Near-term support at $80.05 is only $1.63 below the current price, leaving little room before a technical breakdown. HUD’s fair-lending probe creates regulatory risk and contributed to a 1.53% decline on October 7. Analyst revisions are mixed: Goldman Sachs cut its target to $96, UBS reduced its target to $102, and JPMorgan lowered its target to $92. Total debt of $478.47 billion is substantial, even against $496.41 billion in cash.
What to Watch
Third-quarter 2026 results arrive October 13 at approximately 7:00 a.m. Eastern, followed by management’s conference call at 10:00 a.m. Eastern. Investors should compare the report with the current $83.03 billion revenue base and 9.5% revenue growth rate. Holding above $80.05 would preserve near-term support, while a break below it would weaken the technical setup. A move back above the $84.01 20-day moving average would be the first sign that momentum is improving. The next meaningful upside test is $90.29, the 30-day high. Investors should also track the HUD investigation and whether analyst targets continue moving lower from the current $99.20 consensus.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$90.00
Mean Target
$99.20
High Target
$115.00


Earnings and Financial Data

Sector
Financial Services
Industry
Banks – Diversified
Employees
197,466
Earnings & Dividends
Next Earnings
Oct 13, 2026
EPS (Trailing)
$6.88
Dividend Yield
249.0%
Payout Ratio
26.2%

Frequently Asked Questions

Is WFC a good stock to buy?
WFC has a buy recommendation from 23 analysts and trades at a P/E of 11.87. The 9.5% revenue growth rate supports the bullish case, but negative 20-day momentum makes the current setup mixed.
What is WFC’s price target?
The average analyst target is $99.20, with estimates ranging from $90.00 to $115.00. From the current $81.68 price, the consensus target implies 21.45% upside.
Is WFC stock undervalued?
WFC trades at 11.87 times earnings and has an analyst target of $99.20 versus its current $81.68 price. The valuation suggests upside if the company maintains its 9.5% revenue growth.
What are WFC’s support and resistance levels?
Near-term support is $80.05, and near-term resistance is $90.29. The takeaway is that WFC is trading much closer to support than resistance at $81.68.
Is WFC stock gaining momentum?
Five-day momentum is positive at 0.26%, but 20-day momentum is negative 10.49%, and the price is 4.46% below its $84.01 moving average. The takeaway is that the brief rebound has not reversed the broader short-term weakness.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 08, 2026.