ALTSTATION.IO

Waste Management, Inc. (WM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 09, 2026

Price
$207.73
Change
-1.13%
Market Cap
$83.03B
Avg Volume
2.1M

Company Overview

Waste Management, based in Houston, Texas, operates as the core disposal, recycling, and environmental services backbone within the Industrials sector. The company collects solid waste and recyclable materials from residential, commercial, industrial, and municipal clients across the United States, Canada, and international markets. Beyond regular curbside hauling, it controls the entire disposal chain through company-owned transfer stations, recovery facilities, and landfills. It also processes and resells reclaimed commodities like cardboard, plastics, metals, and glass, alongside commercial composting and industrial remediation services.

WM operates as an undisputed market leader, shielded by the massive barriers to entry inherent to physical waste infrastructure. Permitting new landfills or transfer stations faces severe regulatory and geographic hurdles, which gives existing disposal network owners durable pricing leverage and steady recurring contract revenue. Its main operational risks center on recycling commodity price swings, capital-intensive fleet operations, and strict environmental compliance standards. While local haulers compete for collection routes, they frequently have to pay disposal fees to use WM’s proprietary facilities.

The company is actively turning its waste footprint into higher-value revenue streams rather than relying solely on basic tipping fees. WM continues to build out landfill gas-to-energy projects that capture methane emissions to generate renewable electricity and renewable natural gas. At the same time, it has expanded into specialized, higher-margin sectors, including Regulated Waste and Compliance Services for medical and hazardous materials, along with secure information destruction. This focus on resource recovery and compliance broadens its revenue base while cementing its role in essential infrastructure.

Key Financials
Market Cap
$83.03B
Revenue
$25.67B
EBITDA
$7.77B
Gross Margin
40.6%
Profit Margin
11.1%
Revenue Growth
4.0%
Total Cash
$557.00M
Total Debt
$23.36B
Free Cash Flow
$2.35B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
29.42
Forward P/E
22.87
Beta
0.43
52-Week High
$248.13
52-Week Low
$194.11
EPS
$7.06
50-Day Avg
$217.45
200-Day Avg
$224.64
Price/Book
8.37
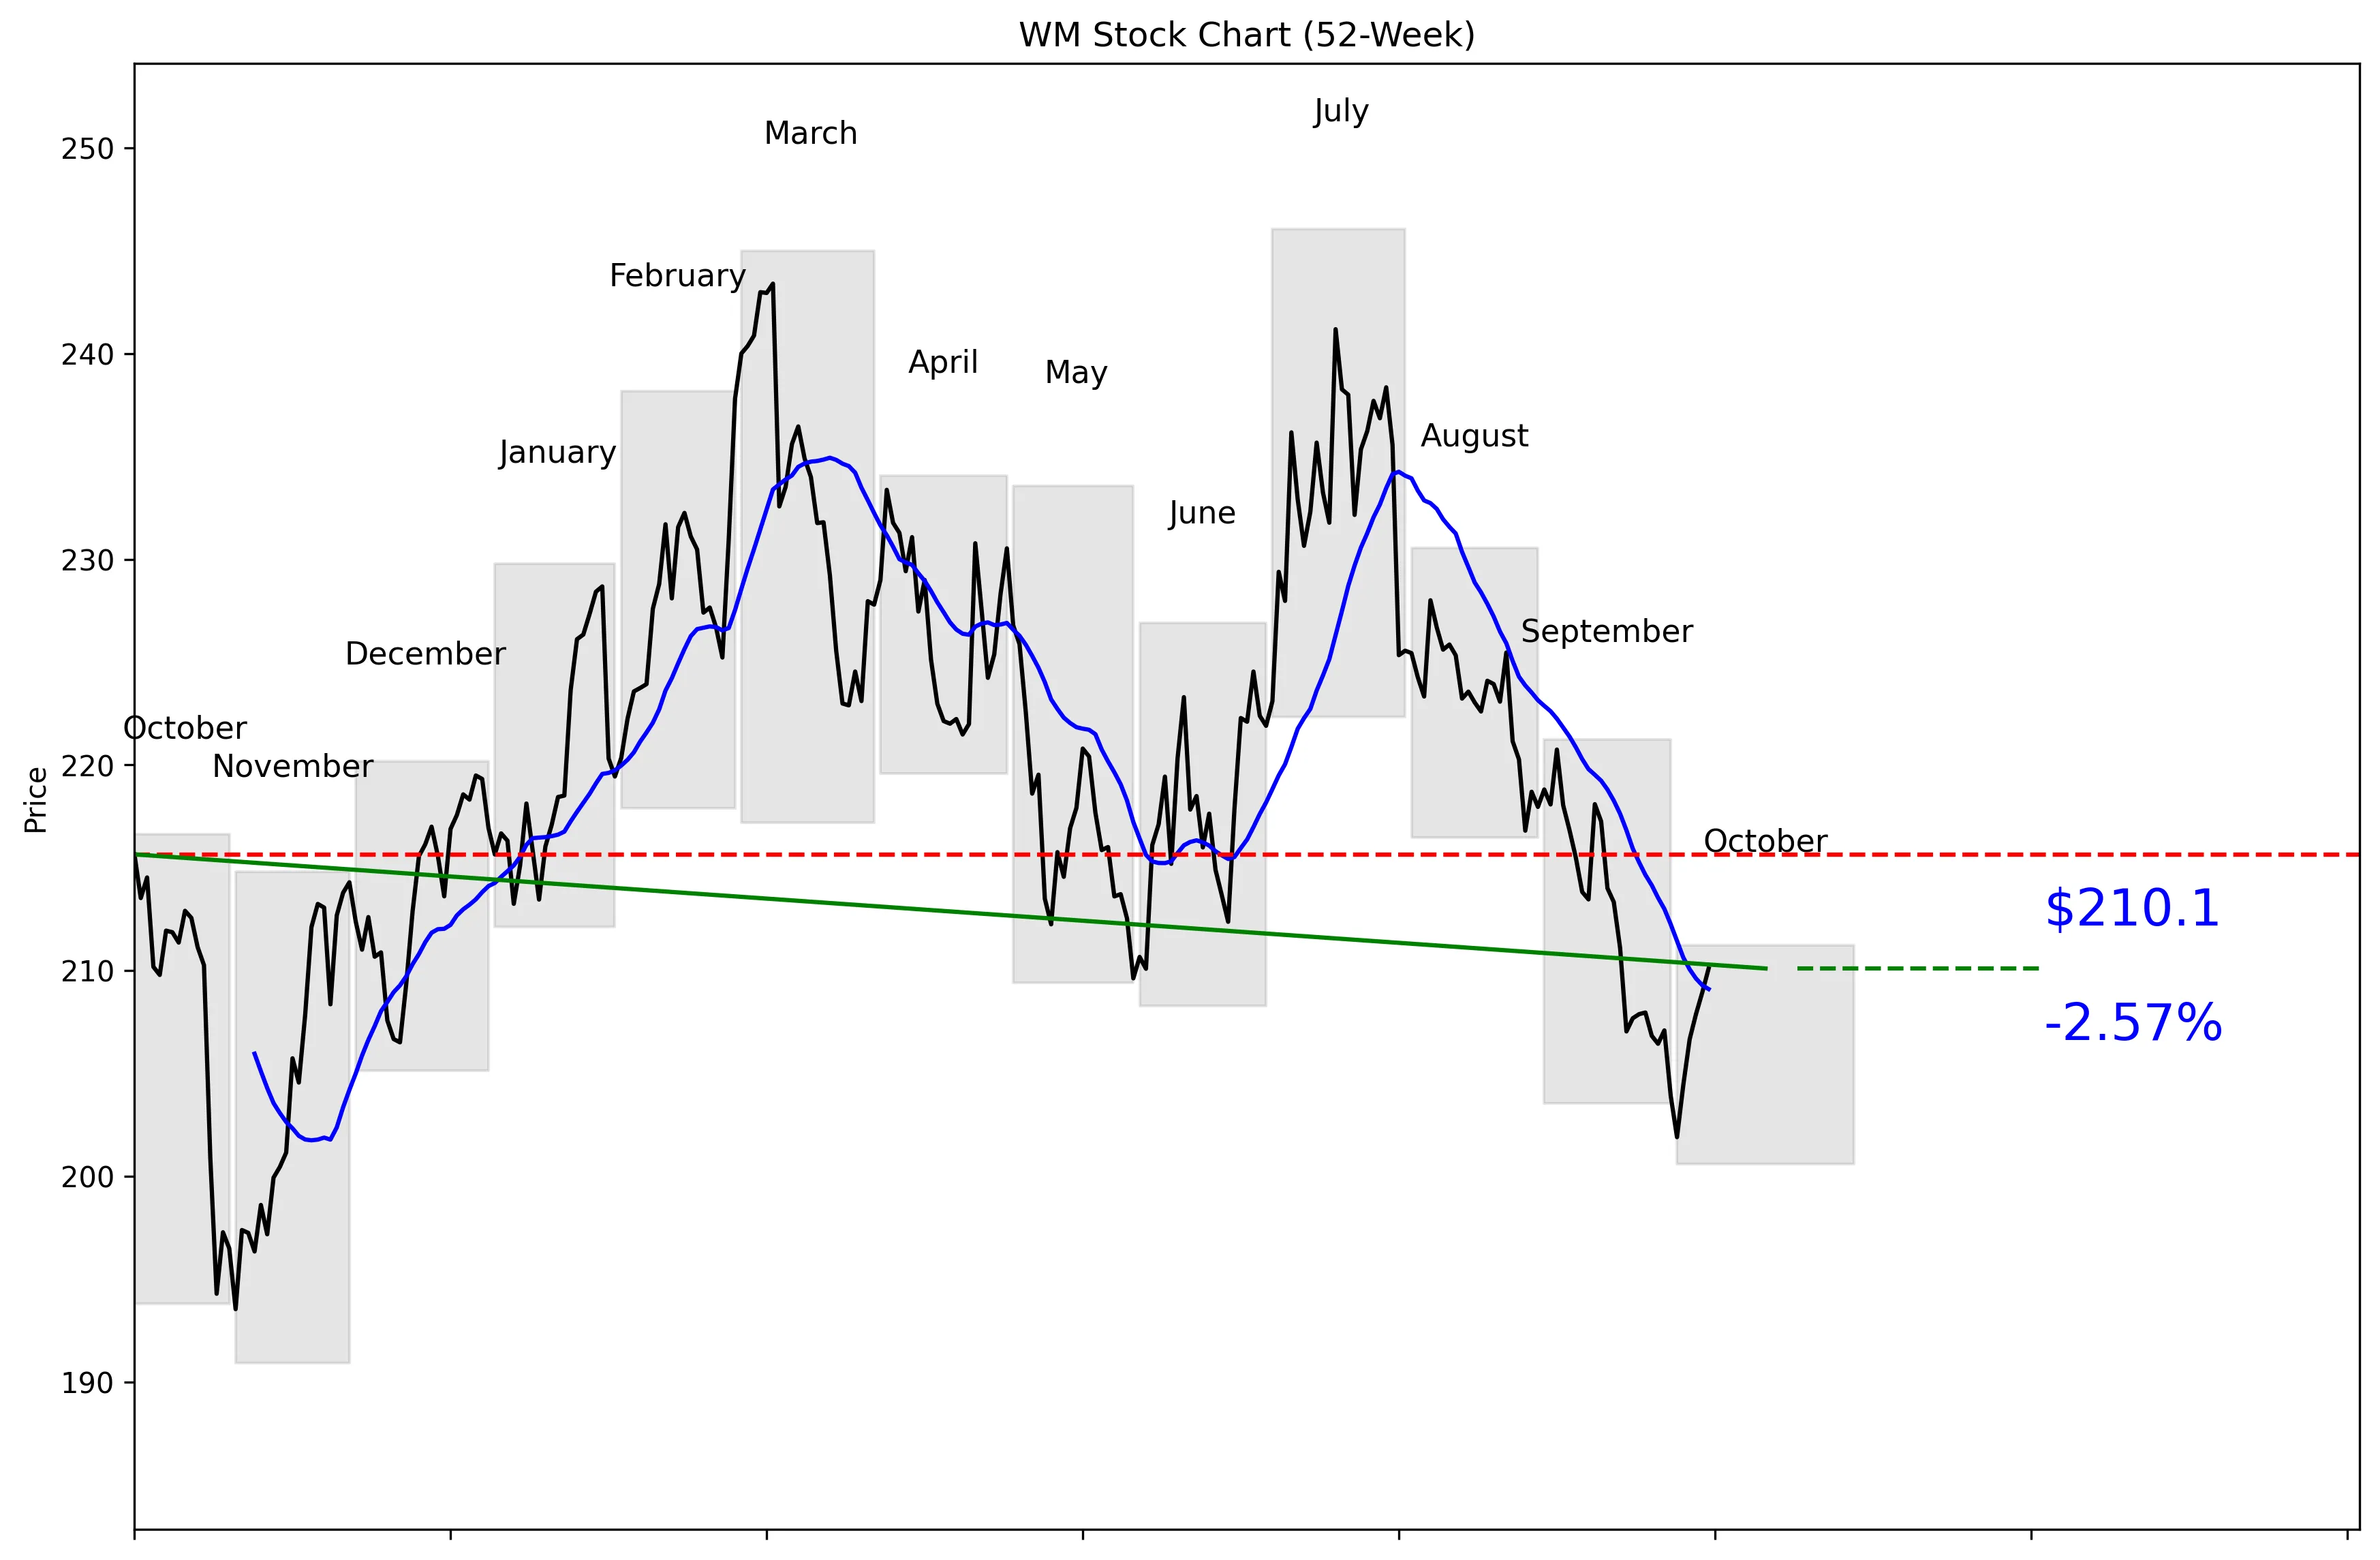
WM 52-Week Stock Chart
Technical Analysis
WM trades at $207.73, 35% of the way from its $190.92 52-week low to its $246.06 high. The stock is 14.62% below that high and 10.05% above the low. Five-day momentum is positive at 4.06%, but 20-day momentum remains negative at 1.74%. The supplied technical data places the stock 0.48% versus its $209.10 20-day moving average. Near-term support is $201.90, while resistance sits at $220.74.


Recent News and Developments

Raymond James cuts WM price target to $254

Raymond James kept its Buy rating on WM on October 9 but lowered its price target from $262 to $254. The rating remains bullish, but the cut signals cooler expectations. Source: Stock Analysis

Wells Fargo holds its $268 target on WM

Wells Fargo maintained its Buy rating and $268 price target on October 9. That was the most bullish target among the firm updates reported during the week. Source: Stock Analysis

CIBC slashes WM target by 10%

CIBC maintained its Hold rating on October 8 while cutting its price target from $250 to $225. That is a $25 reduction, or 10%, and the sharpest target cut among the week’s listed analyst actions. Source: Stock Analysis


Market Sentiment and Analyst Recommendations

Bull Case
WM generated $25.67 billion in revenue and is still growing, with revenue up 4.0%. Its $83.03 billion market cap reflects a large, established business rather than a speculative growth story. The analyst consensus is Buy across 25 analysts. Their average target is $255.56, with estimates ranging from $220.00 to $277.00. Wells Fargo maintained its Buy rating and $268 target on October 9, while Raymond James kept its Buy rating with a reduced $254 target. The bull case is straightforward: steady revenue growth, broad analyst support, and targets that remain above the current $207.73 price.
Bear Case
WM is not cheap at 29.42 times earnings. Revenue growth of 4.0% may not be enough to justify that multiple if growth slows. The balance sheet carries $23.36 billion in debt against only $557.00 million in cash. Recent analyst revisions also weakened the upside case: JPMorgan cut its target from $270 to $235, while CIBC reduced its target from $250 to $225. CIBC’s 10% cut came with a Hold rating, and JPMorgan’s 12.96% reduction undercut its maintained Buy rating. The supplied data does not identify specific competitive or macro threats, but the combination of high debt, a premium valuation, and falling targets is enough reason for caution.
What to Watch
The first technical test is whether WM can hold the $201.90 near-term support level. A move above $220.74 resistance would strengthen the short-term setup, while a break below support would weaken it. Investors should track whether the current 4.06% five-day momentum can reverse the negative 1.74% 20-day trend. Revenue growth needs to hold at or above the reported 4.0% rate to support a 29.42 P/E. Analyst revisions matter after the October 8 and October 9 cuts, particularly whether targets continue moving toward CIBC’s $225 and JPMorgan’s $235 or recover toward Wells Fargo’s $268. No scheduled earnings date or company catalyst was provided, so the next-quarter thesis rests on price action, revenue growth, debt, cash, and further analyst changes.
Analyst Consensus
BUY

Based on 25 analyst opinions
Low Target
$220.00
Mean Target
$255.56
High Target
$277.00


Earnings and Financial Data

Sector
Industrials
Industry
Waste Management
Employees
60,500
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$7.06
Dividend Yield
180.0%
Payout Ratio
50.1%

Frequently Asked Questions

Is WM a good stock to buy?
The consensus recommendation is Buy based on 25 analysts, but WM trades at a 29.42 P/E. The takeaway is that analysts are bullish, but the valuation demands continued execution.
What is WM’s price target?
The average analyst target is $255.56, with a range from $220.00 to $277.00. The takeaway is that every supplied target is above the current $207.73 price.
Where is WM trading within its 52-week range?
WM is 35% of the way from its $190.92 technical low to its $246.06 technical high. The takeaway is that the stock remains closer to its low than its high.
What are WM’s support and resistance levels?
Near-term support is $201.90, and near-term resistance is $220.74. The takeaway is that these are the key levels to watch around the current $207.73 price.
How strong are WM’s fundamentals?
WM reports $25.67 billion in revenue, 4.0% revenue growth, $557.00 million in cash, and $23.36 billion in debt. The takeaway is that the company is growing, but its debt load is substantial relative to cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 09, 2026.