ALTSTATION.IO

Halliburton Company (HAL) Stock Analysis

By Nova Skye | AltStation.io | Updated October 22, 2026

Price
$33.60
Change
+0.04%
Market Cap
$28.00B
Avg Volume
10.8M

Company Overview

Founded in 1919 and headquartered in Houston, Texas, Halliburton Company is an oil and gas equipment and services giant operating in the energy sector. The company sells specialized hardware, chemical solutions, and field engineering services directly to upstream oil and gas exploration and production companies worldwide. Its operations run through two core divisions: Completion and Production, which handles well cementing, hydraulic fracturing stimulation, artificial lift, and downhole completion tools; and Drilling and Evaluation, which delivers drill bits, drilling fluids, wireline logging, and pipeline testing. They also sell cloud-based digital platforms and artificial intelligence software for subsurface reservoir modeling and automated well construction.

Halliburton is an established market leader, occupying a permanent seat in the Big Three global oilfield services tier alongside SLB and Baker Hughes. Its primary operational moat lies in downhole technology and well completions, where its cementing and stimulation capabilities give it strong pricing leverage. However, Halliburton remains structurally exposed to the cyclical swings of North American shale drilling, where domestic operator budget cuts quickly compress service margins. Competitors like SLB outmuscle them across deepwater and international markets, while nimble domestic players like Liberty Energy consistently pressure their market share in US pressure pumping.

Halliburton generated 22.94 billion dollars in revenue for 2024, essentially flat compared to 23.02 billion dollars in 2023. The Completion and Production segment drove 13.25 billion dollars, or 57.8 percent of total revenue, while Drilling and Evaluation generated 9.69 billion dollars, representing 42.2 percent. The company is actively executing a necessary geographic pivot: North American revenue dropped 8 percent in 2024 to 9.6 billion dollars (42 percent of total sales), while international revenue grew 6 percent to capture 58 percent of the business. By prioritizing higher-margin international contracts and digital subsurface software over discounted domestic drilling volume, Halliburton is managing to protect its margins in a slowing North American cycle.

Key Financials
Market Cap
$28.00B
Revenue
$22.37B
EBITDA
$4.14B
Gross Margin
15.1%
Profit Margin
7.2%
Revenue Growth
3.7%
Total Cash
$2.05B
Total Debt
$8.20B
Free Cash Flow
$2.05B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
17.69
Forward P/E
11.45
Beta
0.84
52-Week High
$43.59
52-Week Low
$24.92
EPS
$1.90
50-Day Avg
$34.13
200-Day Avg
$35.71
Price/Book
2.68
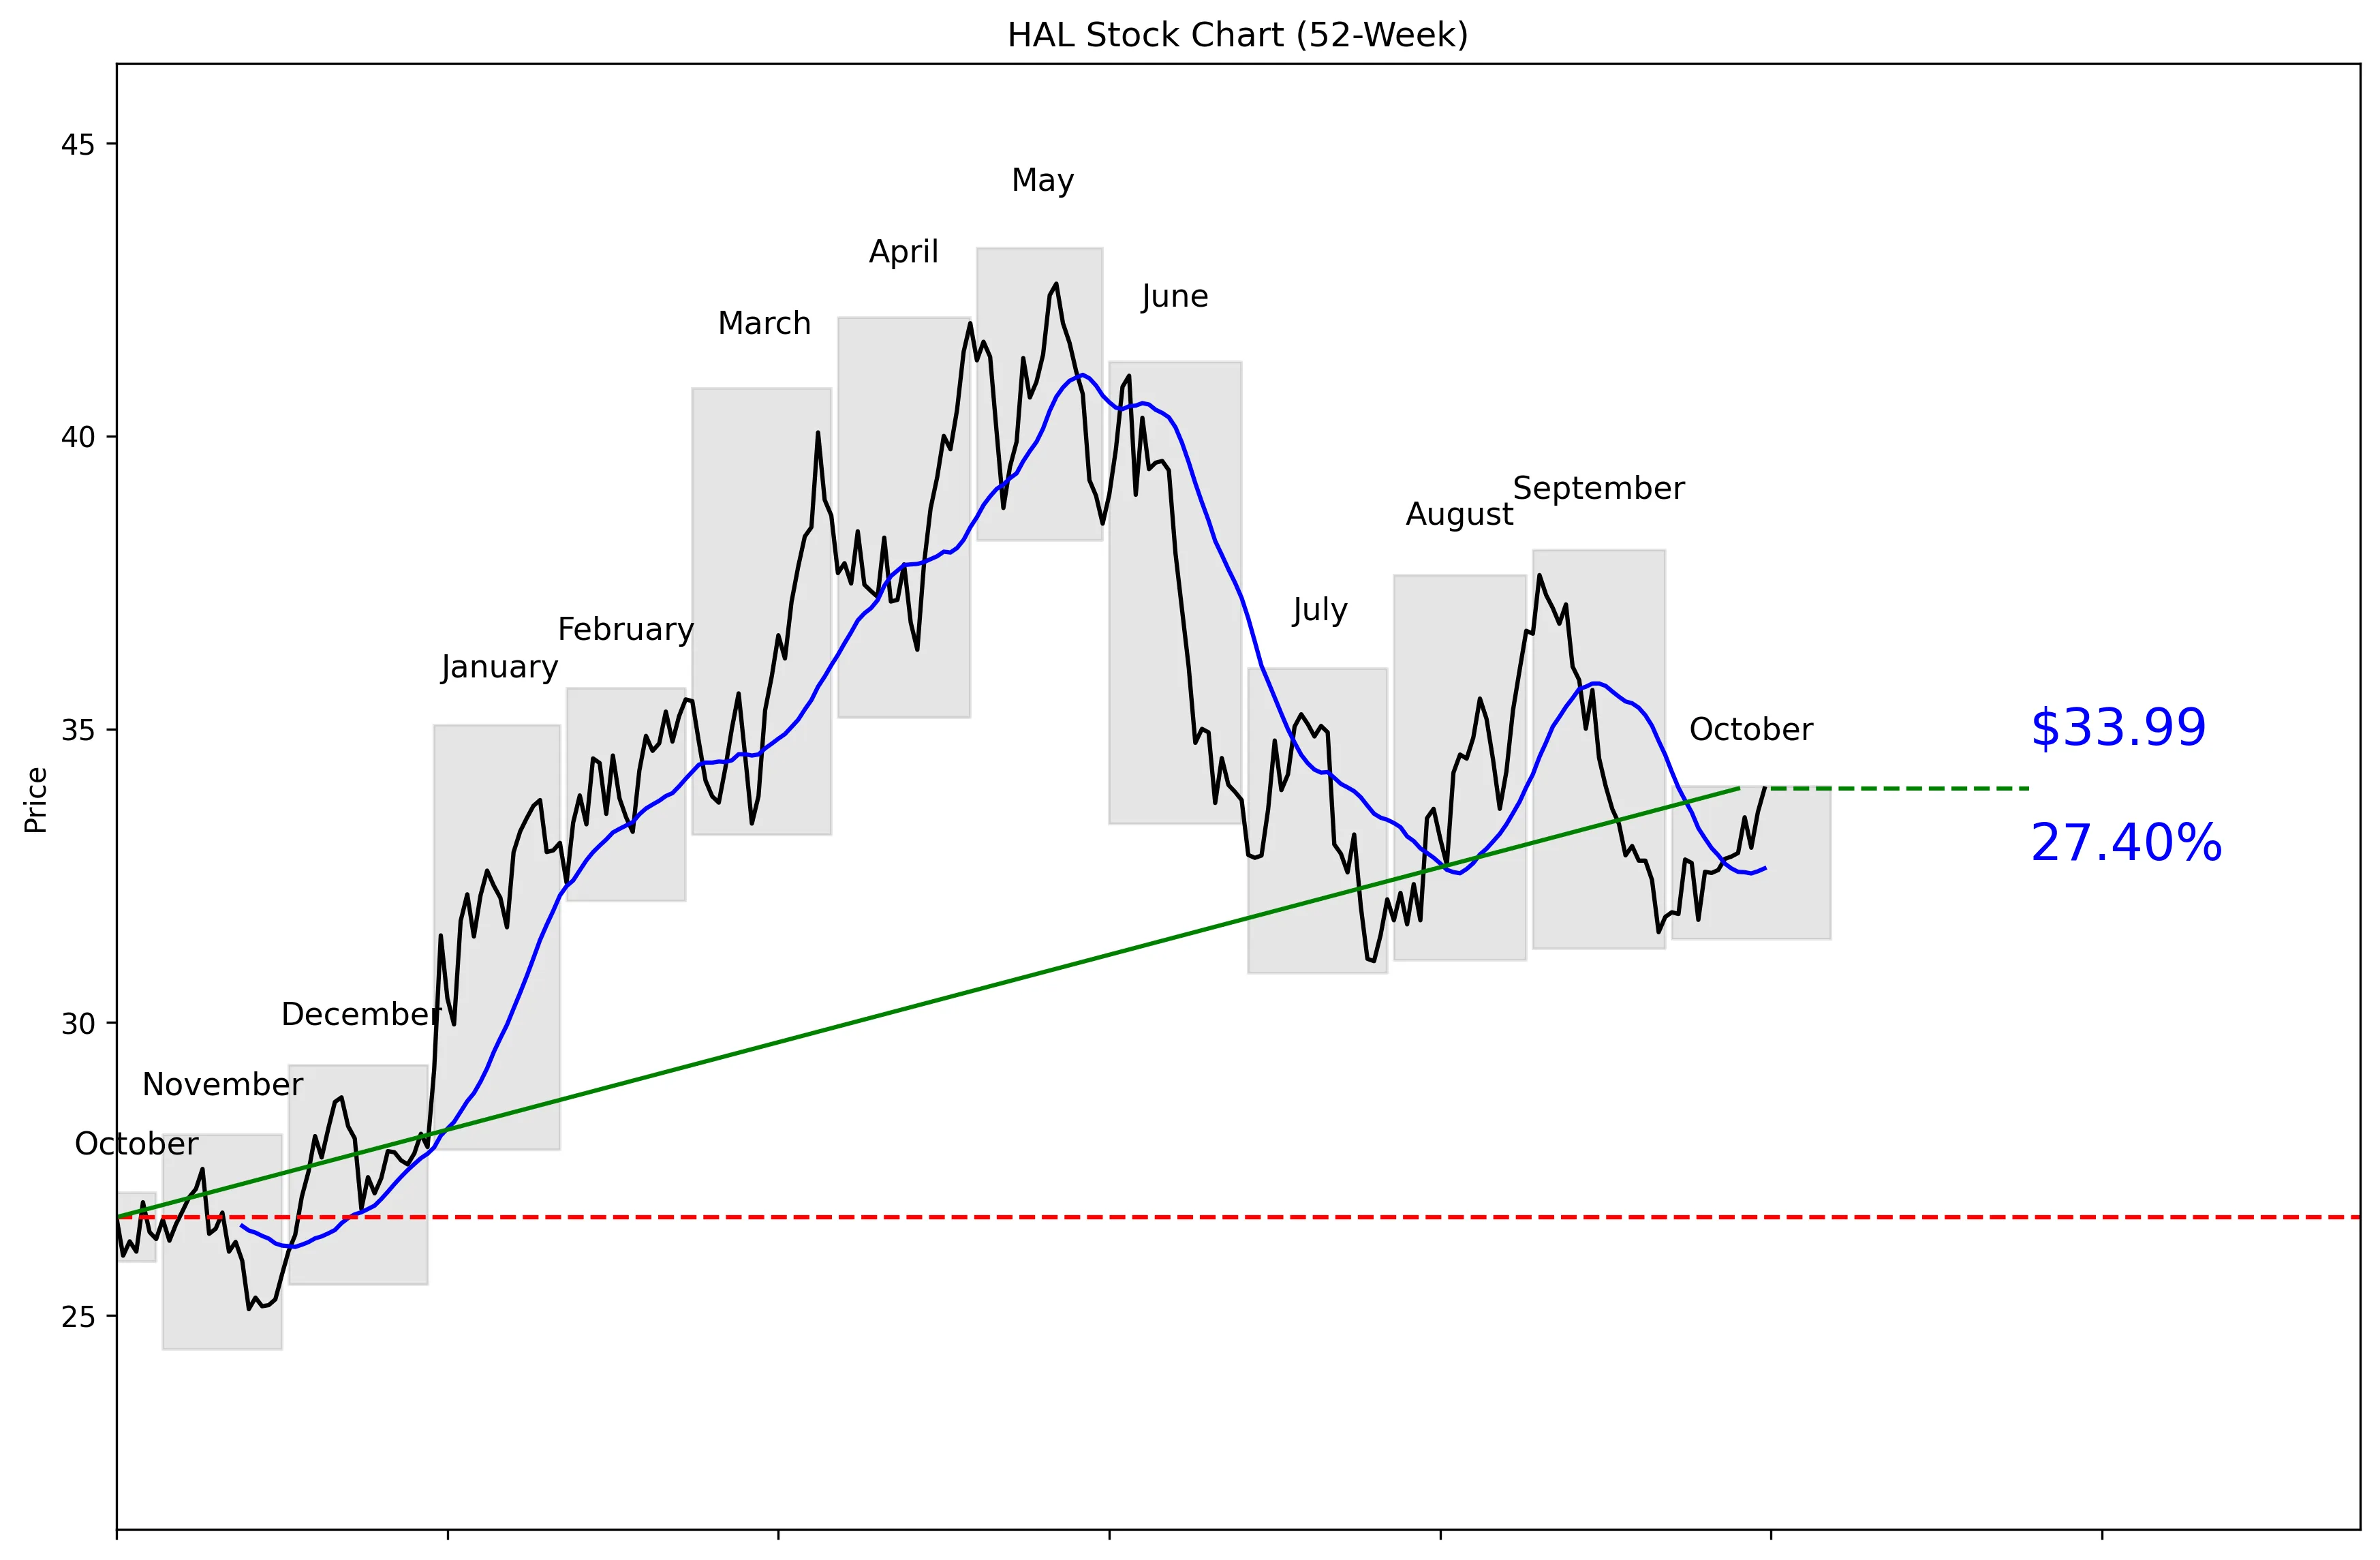
HAL 52-Week Stock Chart
Technical Analysis
HAL trades at $33.60, 51% of the way from its technical 52-week low of $24.43 to its high of $43.20. The stock is 21.33% below that high but 39.16% above the low. Price is 4.17% above the 20-day moving average of $32.63, with gains of 3.53% over five trading days and 2.97% over 20 days. Near-term support is $31.54, while resistance sits at $36.07. The trend is positive, but HAL still needs to clear $36.07 to strengthen the technical case.


Recent News and Developments

Halliburton posts $5.7 billion quarter

Halliburton reported third-quarter revenue of $5.7 billion, net income of $417 million and adjusted earnings of $0.60 per share. Free cash flow reached $156 million, and the company repurchased roughly $250 million of stock. Source: Halliburton

HAL jumps after earnings beat

Halliburton shares rose 3.4% in premarket trading after adjusted earnings beat consensus by $0.02 per share. Revenue of $5.7 billion also topped the $5.58 billion forecast. Source: Investing.com

Jefferies and RBC raise Halliburton targets

Jefferies kept its Buy rating and raised its Halliburton price target from $47 to $48. RBC Capital maintained Outperform and increased its target from $45 to $46. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
Halliburton generated $22.37 billion in revenue, with revenue growth of 3.7%. Third-quarter revenue reached $5.7 billion, beating the $5.58 billion forecast. Adjusted earnings of $0.60 per share beat consensus by $0.02, sending the stock up 3.4% in premarket trading. The quarter also produced $156 million in free cash flow, while Halliburton repurchased roughly $250 million of stock. Analysts are bullish: 24 rate HAL a buy, with a $43.25 average target versus the current $33.60 price. Jefferies raised its target from $47 to $48, while RBC Capital increased its target from $45 to $46. The buy case is straightforward: improving momentum, an earnings beat, share repurchases and analyst targets well above the current price.
Bear Case
Halliburton carries $8.20 billion in total debt against $2.05 billion in cash, leaving debt four times larger than cash. That balance-sheet gap matters because the company used roughly $250 million for share repurchases while generating $156 million in quarterly free cash flow. Revenue growth is positive but modest at 3.7%, so HAL is not delivering rapid expansion. The stock trades at 17.69 times earnings, which leaves less room for operational disappointment than a lower valuation would. HAL is already 39.16% above its technical 52-week low, meaning part of the recovery has happened. The analyst target range runs from $29 to $51, showing substantial disagreement about fair value. A break below $31.54 would weaken the near-term setup, while failure at $36.07 would show buyers still lack control.
What to Watch
Watch whether HAL can hold above its 20-day moving average of $32.63 and near-term support at $31.54. A move through the $36.07 resistance level would confirm that the recent 3.53% five-day momentum has more room to run. On the business side, the next quarterly update needs to show whether revenue can improve from $5.7 billion and remain above the latest $5.58 billion forecast benchmark. Adjusted earnings should be measured against the latest $0.60 per share result and the $0.02 consensus beat. Free cash flow is another key test after reaching $156 million, especially with total debt at $8.20 billion. Investors should also track whether future share repurchases continue near the latest roughly $250 million level. David Hernandez’s board appointment runs through Halliburton’s 2027 annual shareholder meeting, but financial execution will matter more than the board change.
Analyst Consensus
BUY

Based on 24 analyst opinions
Low Target
$29.00
Mean Target
$43.25
High Target
$51.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas Equipment & Services
Employees
46,000
Earnings & Dividends
Next Earnings
Jan 20, 2027
EPS (Trailing)
$1.90
Dividend Yield
206.0%
Payout Ratio
35.8%

Frequently Asked Questions

Is HAL a good stock to buy?
HAL has a buy recommendation from 24 analysts and trades at $33.60 versus an average analyst target of $43.25. The positive rating supports the bull case, but investors should weigh it against $8.20 billion in debt. Takeaway: analysts favor buying HAL, but the balance sheet deserves attention.
What is HAL’s price target?
The average analyst target is $43.25, with estimates ranging from $29 to $51. That range is wide relative to the current $33.60 price. Takeaway: Wall Street sees upside on average, but analyst expectations vary significantly.
What are HAL’s support and resistance levels?
Near-term support is the 30-day low of $31.54, while resistance is the 30-day high of $36.07. HAL currently trades at $33.60 between those levels. Takeaway: $31.54 and $36.07 define the immediate trading range.
Is HAL stock gaining momentum?
HAL gained 3.53% over the last five trading days and 2.97% over the last 20 trading days. The price is also 4.17% above its 20-day moving average of $32.63. Takeaway: near-term momentum is positive.
Does HAL pay a dividend?
The provided data does not include a dividend amount or yield. No dividend conclusion can be made from these figures. Takeaway: verify Halliburton’s current dividend information separately before investing for income.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 22, 2026.