ALTSTATION.IO

Baker Hughes Company (BKR) Stock Analysis

By Nova Skye | AltStation.io | Updated November 02, 2026

Price
$55.23
Change
+1.32%
Market Cap
$54.85B
Avg Volume
7.3M

Company Overview

Baker Hughes Company is a Houston, Texas-based energy services firm operating in the Oil & Gas Equipment & Services sector. The company builds and sells heavy-duty drilling equipment, subsea production systems, turbomachinery, and specialized chemicals for oilfield operations. Its customer base spans global and state-owned oil producers, independent exploration companies, engineering contractors, and geothermal developers. In plain terms, whenever energy producers need to drill, extract, compress, or monitor hydrocarbons and clean energy assets, Baker Hughes sells them the hardware and technical field services to do it.

Baker Hughes holds a top-three global position, commanding roughly 11% to 12% of the $200 billion oilfield services market. It trails market leader SLB at approximately 24.5% share and Halliburton at 16.8% share, making it a formidable challenger with real scale. Its primary competitive advantage over traditional drillers is its industrial technology footprint, specifically gas compression equipment and proprietary monitoring hardware like Bently Nevada. The main threat is the recurring cyclicality of upstream exploration budgets alongside fierce pricing competition from SLB in deepwater projects.

Since shedding its GE ownership in October 2019 to stand on its own, Baker Hughes has been executing a strategic pivot toward industrial and energy technology. Rather than betting solely on volatile rig counts, the company is pushing hard into liquefied natural gas infrastructure, electric-drive compression, and asset optimization software like Cordant. It is also establishing footholds in climate technology, hydrogen, and geothermal systems to capture long-term energy transition capital. This repositioning gives the business a sturdier earnings floor than pure-play oilfield peers while keeping it exposed to ongoing global gas demand.

Key Financials
Market Cap
$54.85B
Revenue
$28.74B
EBITDA
$5.02B
Gross Margin
23.7%
Profit Margin
10.1%
Revenue Growth
14.5%
Total Cash
$5.38B
Total Debt
$18.26B
Free Cash Flow
$5.08B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
18.98
Forward P/E
19.03
Beta
1.03
52-Week High
$70.41
52-Week Low
$44.26
EPS
$2.91
50-Day Avg
$58.13
200-Day Avg
$60.24
Price/Book
2.67
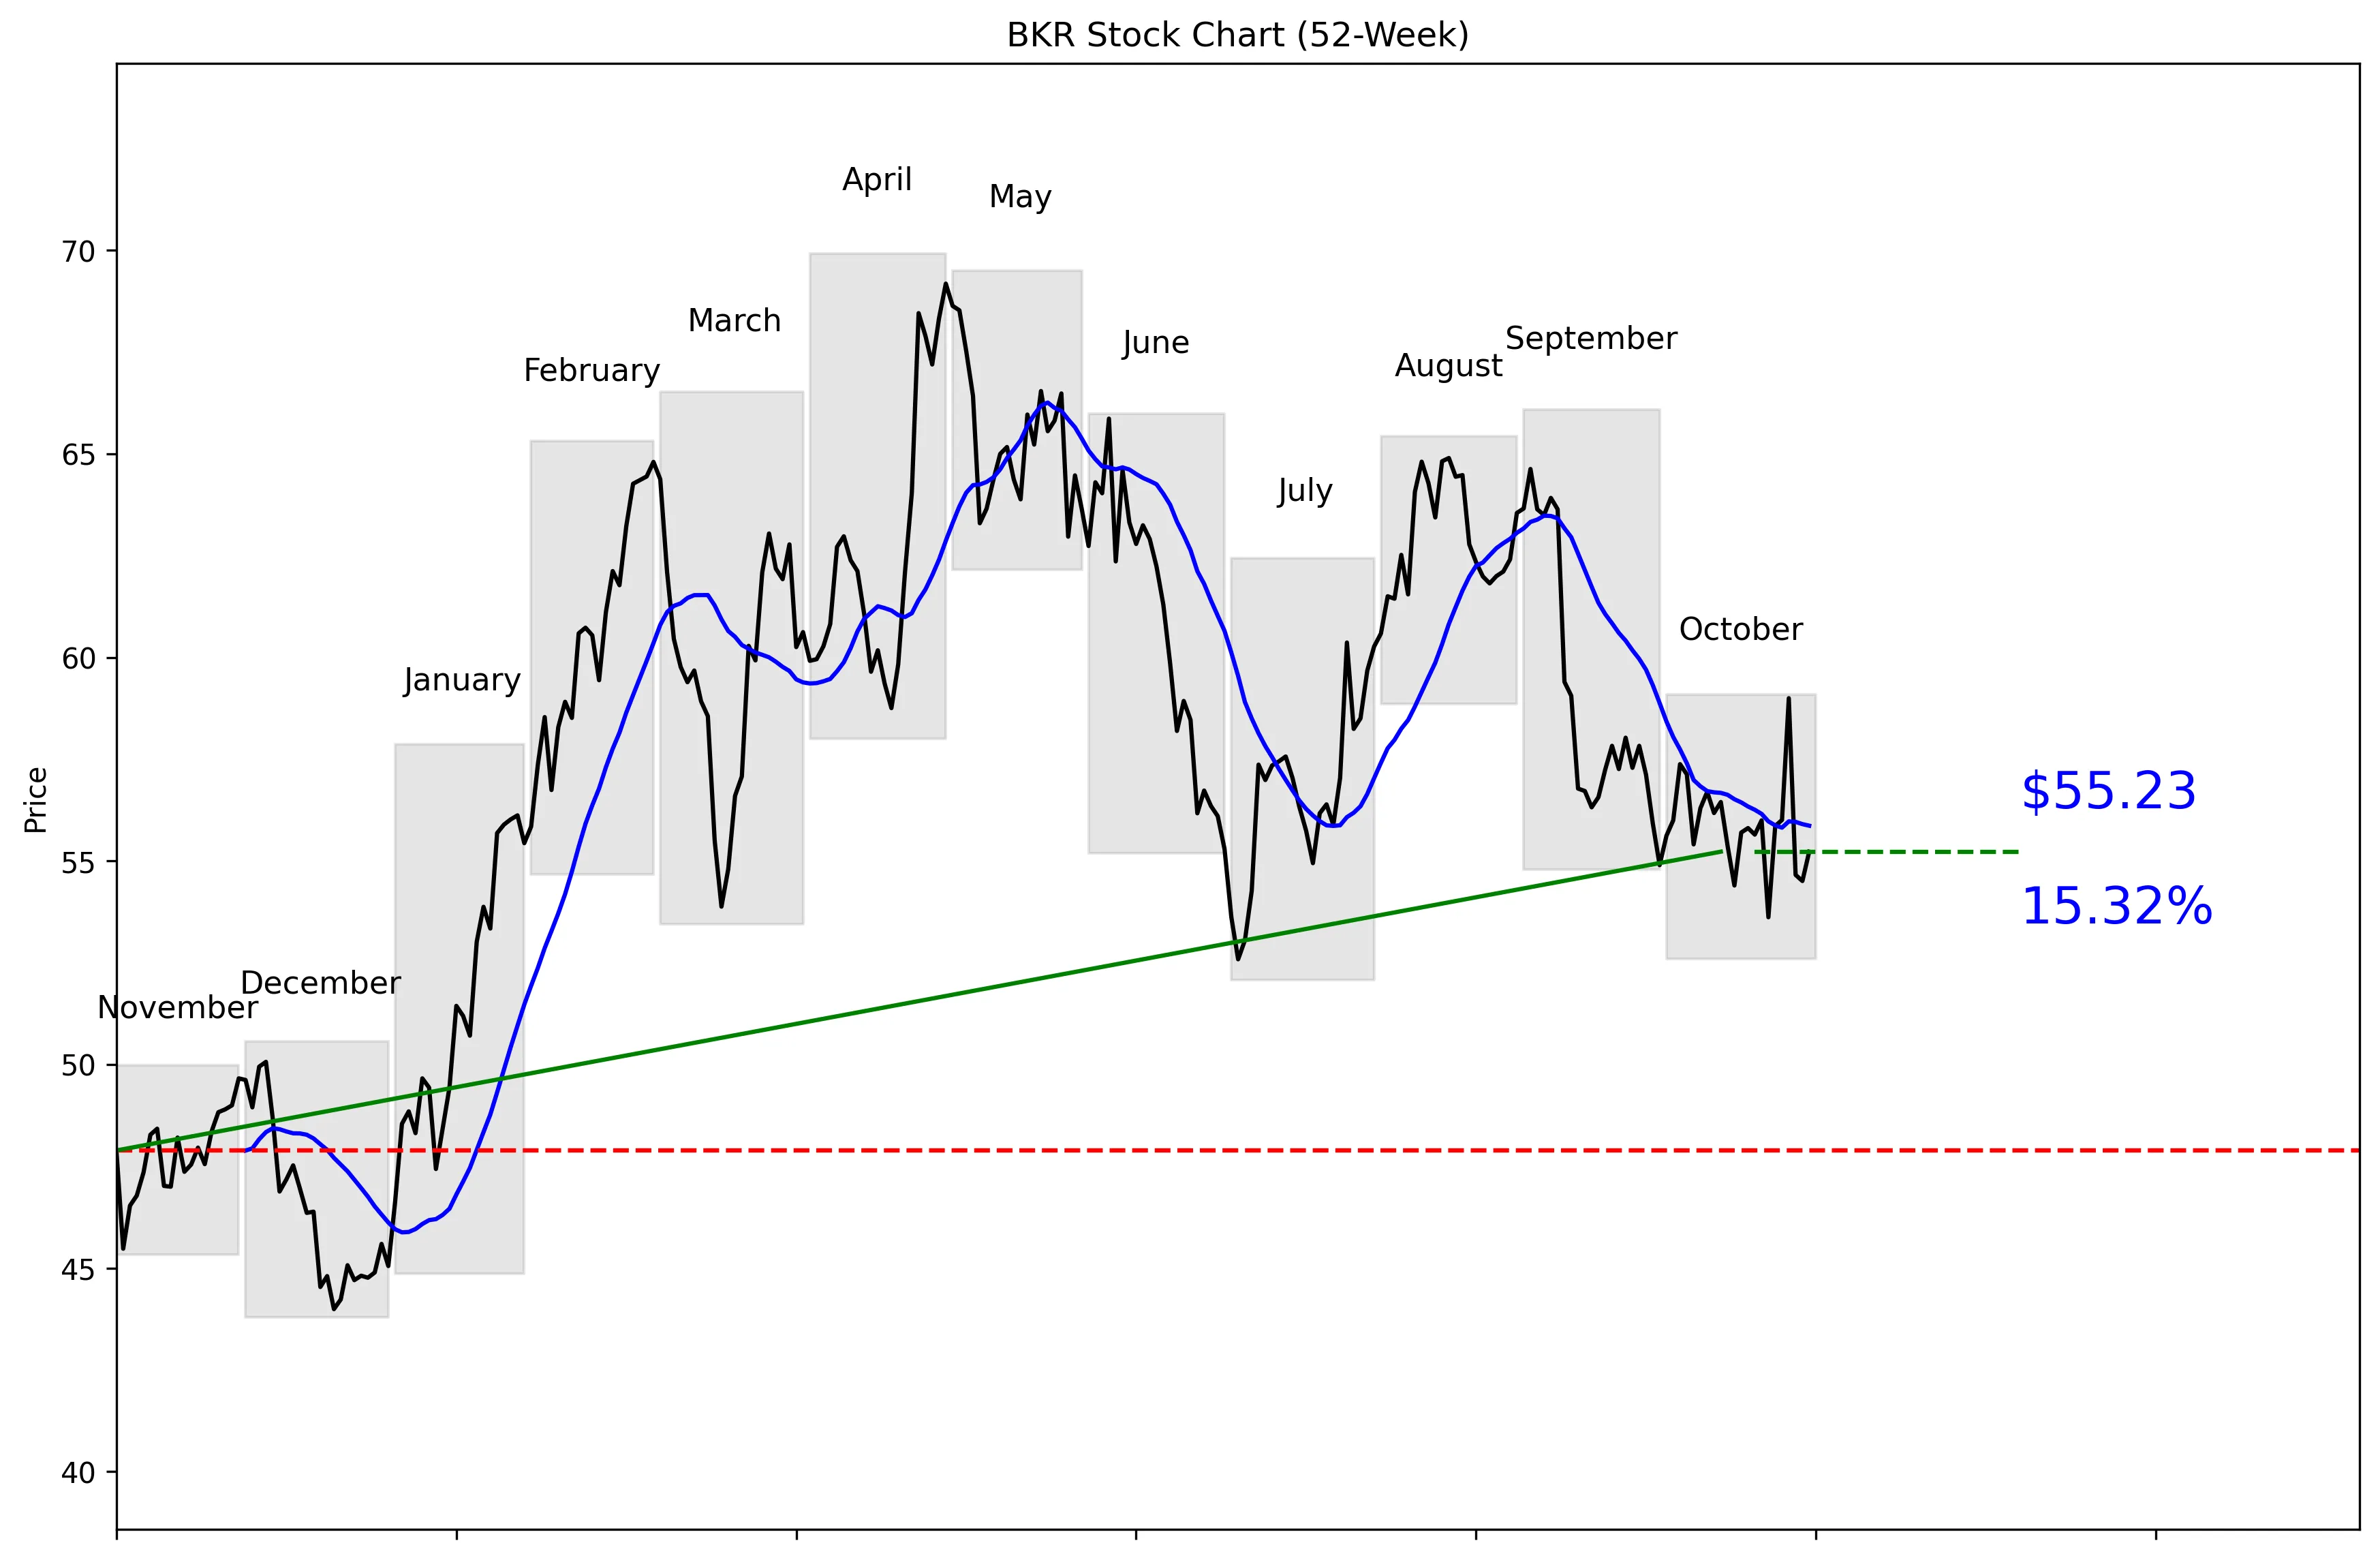
BKR 52-Week Stock Chart
Technical Analysis
BKR trades at $55.23, 44% of the way from its $43.79 52-week low to its $69.92 high. The stock is 21.01% below that high but remains 26.14% above the low. Price sits 1.14% below the 20-day moving average of $55.87. Momentum is negative, with declines of 1.13% over five trading days and 1.38% over 20 trading days. Near-term support is $53.62, while resistance is $59.00.


Recent News and Developments

Baker Hughes sells Waygate Technologies for $1.45 billion

Baker Hughes completed the all-cash sale of Waygate Technologies to Hexagon for approximately $1.45 billion before closing adjustments. The deal transfers Waygate’s inspection and imaging portfolio, intellectual property, facilities and other assets while giving Baker Hughes a meaningful balance-sheet boost. Source: GlobeNewswire

Third-quarter orders reach $10.8 billion

Baker Hughes reported third-quarter revenue of $8.0 billion, attributable net income of $411 million and adjusted diluted EPS of $0.70. Orders reached $10.8 billion, remaining performance obligations totaled $46.4 billion and free cash flow was $769 million. Source: Baker Hughes

Baker Hughes wins Eni subsea contract

Eni awarded Baker Hughes a contract for subsea production systems and services at the Cronos gas development offshore Cyprus. The award was booked during the third quarter, and initial equipment deliveries are expected in the first half of 2027; the contract value was not disclosed. Source: GlobeNewswire


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 14.5%, giving Baker Hughes a solid operating foundation. Third-quarter orders reached $10.8 billion against $8.0 billion in revenue, while remaining performance obligations totaled $46.4 billion. The quarter also produced $769 million in free cash flow, adjusted diluted EPS of $0.70 and attributable net income of $411 million. The $1.45 billion all-cash Waygate Technologies sale provides a meaningful balance-sheet boost. The Eni subsea contract adds future work, with initial equipment deliveries expected in the first half of 2027. At $55.23, the stock sits $14.85 below the $70.08 average analyst target, and 24 analysts collectively rate it a buy.
Bear Case
Baker Hughes carries $18.26 billion in debt against $5.38 billion in cash, leaving a $12.88 billion gap. That balance-sheet pressure matters because analysts have already flagged higher debt and interest expense following the Chart Industries acquisition. The 18.98 P/E is not extreme, but it leaves less room for execution problems. The market’s reaction after earnings was harsh: BKR gained 5.34% to $59.00 on October 27, then dropped 7.36% to $54.66 on October 28. Analyst revisions were also mixed, with Morgan Stanley cutting its target to $68, Piper Sandler to $70 and Barclays to $62. The lowest analyst target is $51.00, below both the current $55.23 price and the $53.62 near-term support level.
What to Watch
The first test is whether BKR can hold the $53.62 30-day low and reclaim its $55.87 20-day moving average. A move above $59.00 would clear near-term resistance, while a break below $53.62 would weaken the technical setup. Investors should compare the next quarter’s orders and revenue with the third quarter’s $10.8 billion and $8.0 billion. Free cash flow should also be measured against the latest $769 million result. Watch how the $1.45 billion Waygate sale affects cash, debt and interest expense after closing adjustments. The Eni project becomes more important as initial equipment deliveries approach in the first half of 2027, although the contract value remains undisclosed.
Analyst Consensus
BUY

Based on 24 analyst opinions
Low Target
$51.00
Mean Target
$70.08
High Target
$85.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas Equipment & Services
Employees
65,600
Earnings & Dividends
Next Earnings
Jan 25, 2027
EPS (Trailing)
$2.91
Dividend Yield
167.0%
Payout Ratio
31.6%

Frequently Asked Questions

Is BKR a good stock to buy?
BKR has a buy recommendation from 24 analysts, revenue growth of 14.5% and an average analyst target of $70.08 versus a current price of $55.23. The takeaway is that the available data supports a bullish view, but it does not remove the stock’s balance-sheet and price risks.
What is BKR’s price target?
The average analyst target is $70.08, with estimates ranging from $51.00 to $85.00. The takeaway is that analyst expectations vary widely despite the consensus buy recommendation.
What is BKR’s 52-week range?
The listed 52-week range is $44.26 to $70.41, while the technical price series shows an exact low of $43.79 and high of $69.92. At $55.23, BKR is 44% of the way from the technical low to the technical high, so the takeaway is that the stock sits below the midpoint of that range.
How much debt does Baker Hughes have?
Baker Hughes has $18.26 billion in total debt and $5.38 billion in total cash. The takeaway is that debt exceeds cash by $12.88 billion.
Does BKR pay a dividend?
The provided key and technical data do not include dividend information. The takeaway is that no dividend conclusion can be made from these figures alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 02, 2026.