ALTSTATION.IO

Royal Caribbean Cruises Ltd. (RCL) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$330.64
Change
+5.58%
Market Cap
$88.44B
Avg Volume
2.3M

Company Overview

Royal Caribbean Cruises Ltd. is a global vacation provider headquartered in Miami, Florida, operating in the Consumer Cyclical sector under the Travel Services industry. Founded in 1968, the company sells ocean cruise vacations and onboard experiences to leisure travelers worldwide. Its business runs through three core brands: Royal Caribbean International for mass-market family vacations, Celebrity Cruises for premium travelers, and Silversea Cruises for ultra-luxury clients. Customers buy travel itineraries ranging from short regional sailings to multi-week international voyages.

Royal Caribbean is an industry heavyweight, controlling roughly 31% of global cruise capacity and sitting alongside Carnival Corporation in a market oligopoly. Its primary edge comes from massive ship scale and tiered branding, which allows the company to extract higher onboard spending across all income demographics. The main risks are straightforward: high capital expenditure requirements, balance-sheet leverage from shipbuilding, and direct pricing pressure from rivals like Carnival and Norwegian Cruise Line. Because travel services are discretionary, any pullback in consumer spending directly hits ticket yields.

The company is in an active growth phase, operating a global fleet of 69 ships as of December 31, 2025, and deploying new flagship builds like the Icon class to push yields higher. Booking volumes and pricing power have remained solid, allowing the operator to convert high vessel utilization into serious cash flow. The key operational focus right now is using that cash generation to manage long-term fleet debt while maintaining high occupancy rates across global itineraries. If consumer travel budgets soften, Royal Caribbean’s heavy fixed costs will squeeze margins, but its scale gives it a much stronger defensive moat than smaller peers.

Key Financials
Market Cap
$88.44B
Revenue
$19.14B
EBITDA
$7.16B
Gross Margin
50.2%
Profit Margin
23.8%
Revenue Growth
8.8%
Total Cash
$851.00M
Total Debt
$23.17B
Free Cash Flow
-$50.00M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
19.56
Forward P/E
16.14
Beta
1.86
52-Week High
$356.39
52-Week Low
$222.22
EPS
$16.90
50-Day Avg
$272.81
200-Day Avg
$286.82
Price/Book
7.55
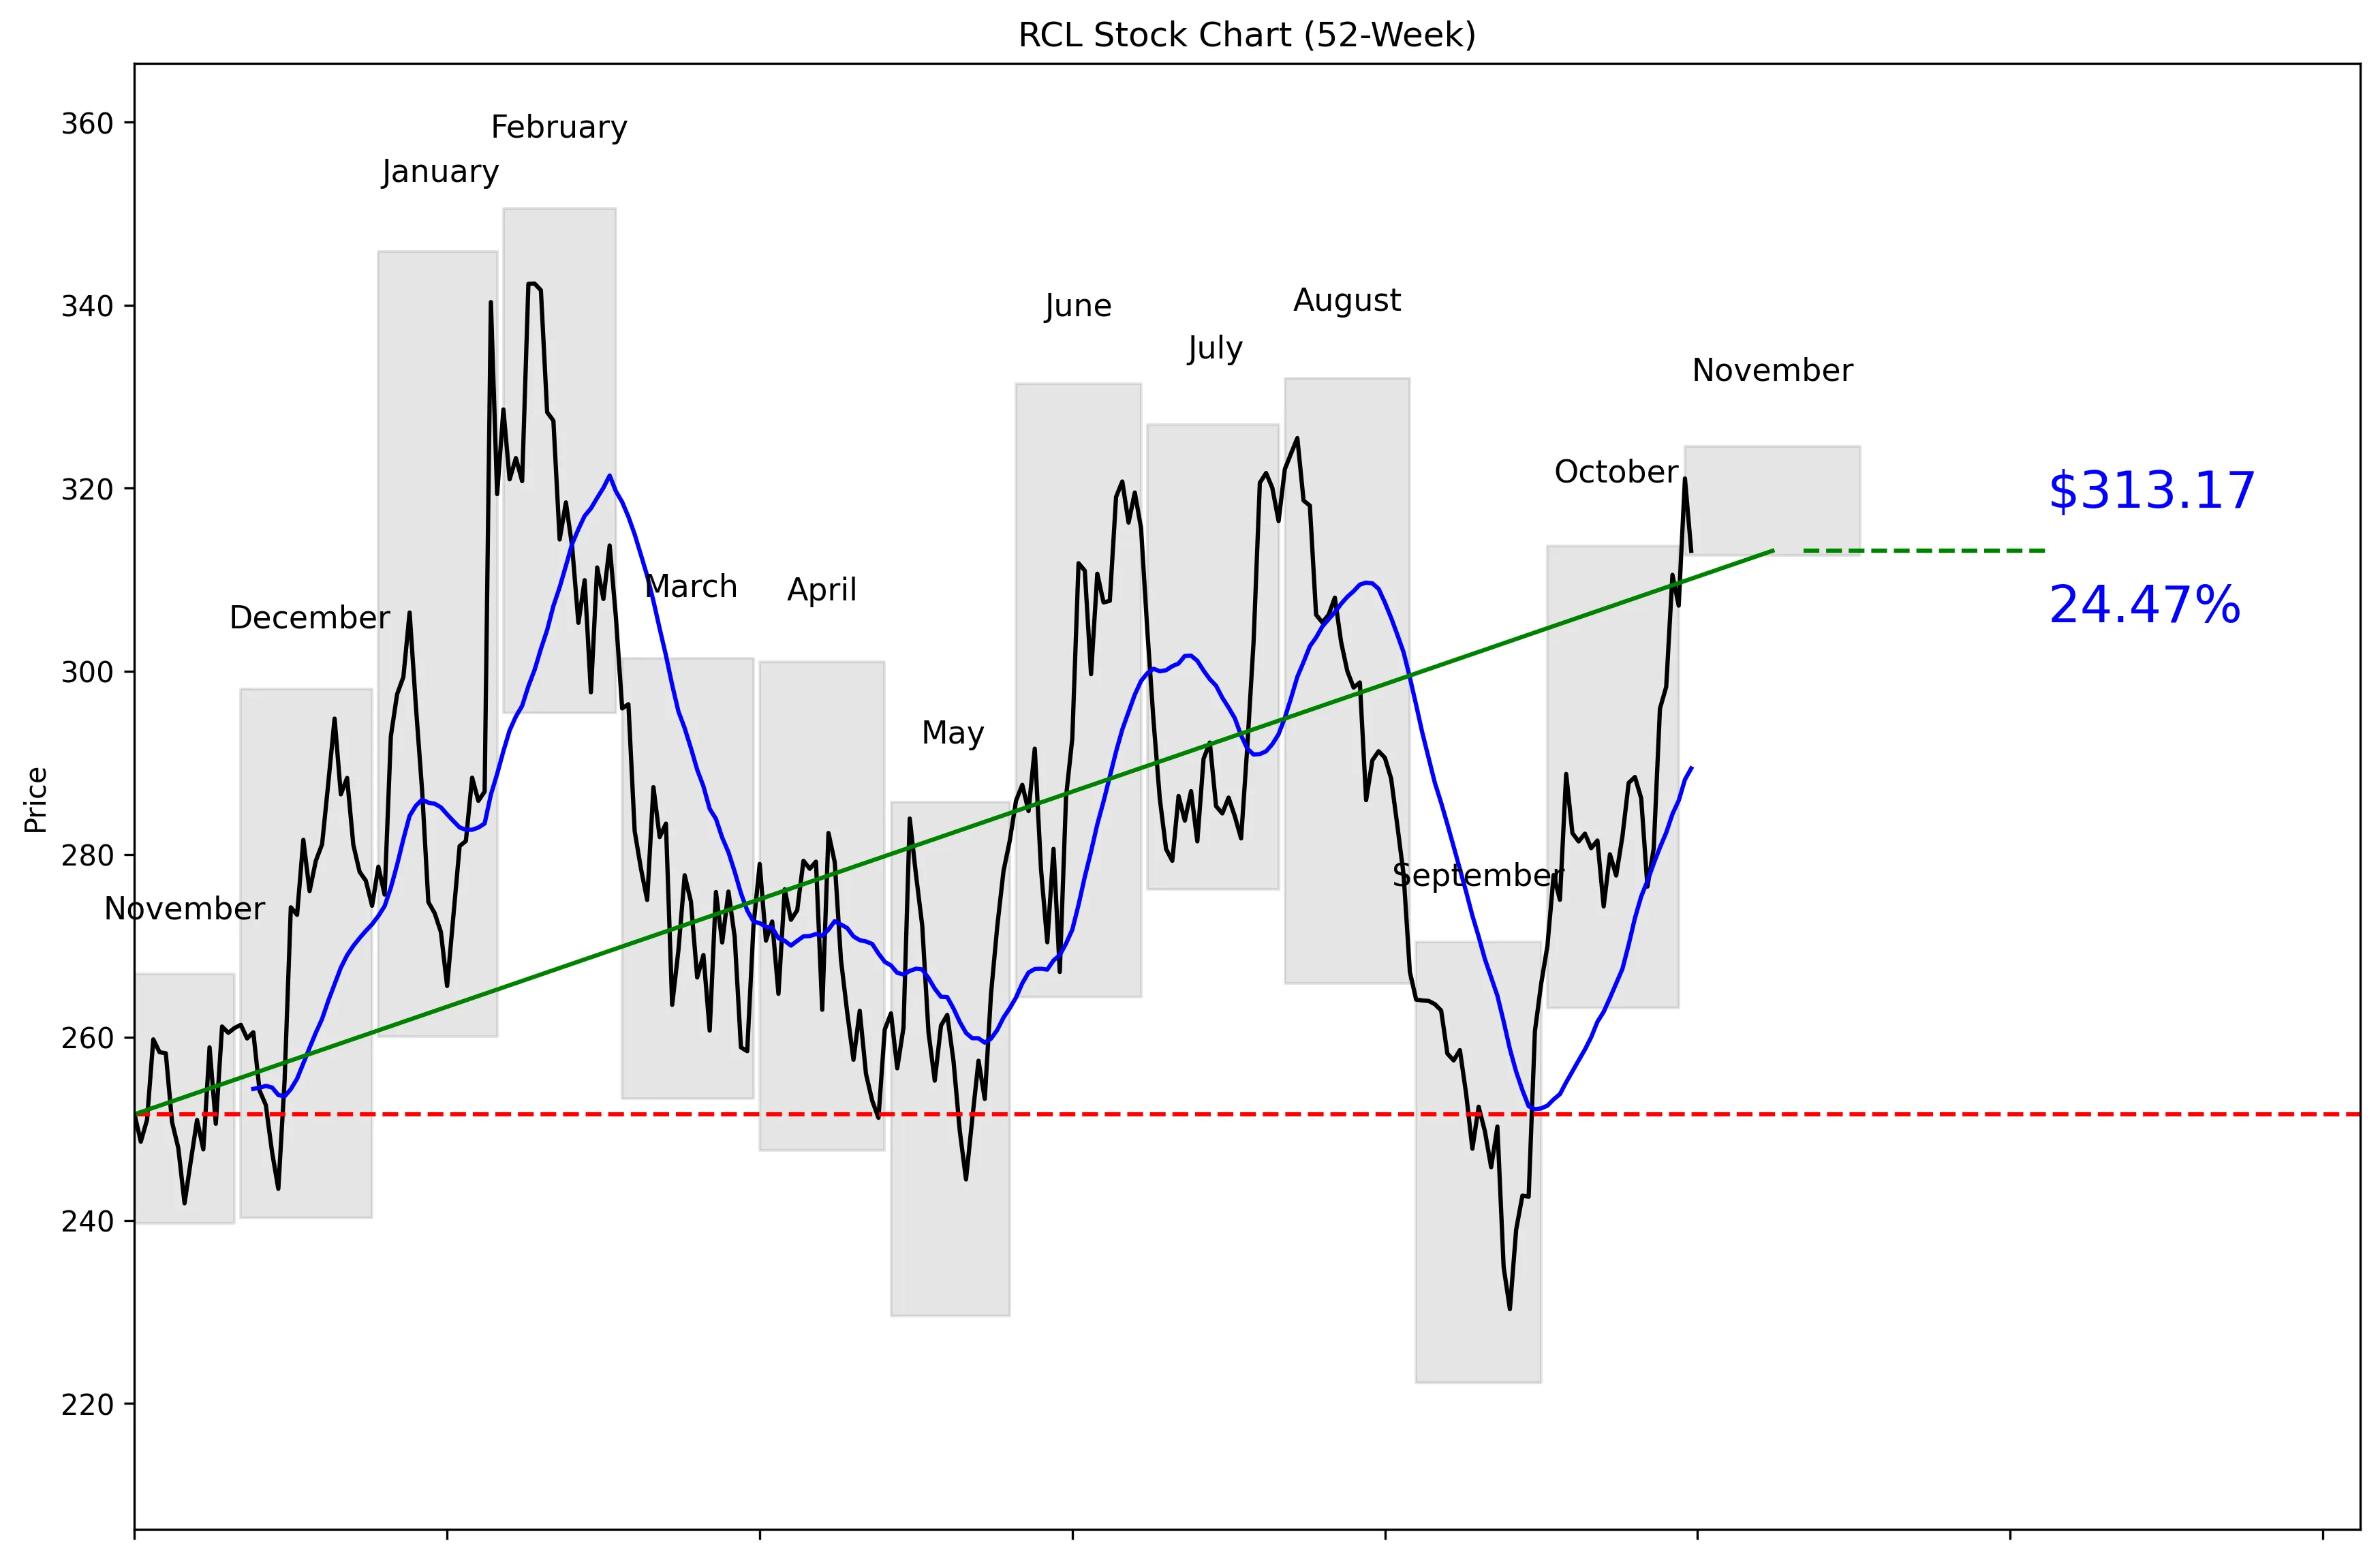
RCL 52-Week Stock Chart
Technical Analysis
RCL trades at $330.64, 71% of the way from its $222.22 low to its $350.59 high. The stock is 10.67% below that high and 40.93% above the low. It sits 8.22% above its 20-day moving average of $289.39. Momentum is positive at 5.83% over five trading days and 8.45% over 20 trading days. Near-term support is $230.30, while the stated 30-day resistance is $321.07, which the current price has already exceeded.


Recent News and Developments

Freedom Capital upgrades RCL to Buy

Freedom Capital Markets upgraded Royal Caribbean from Hold to Buy on October 28. The firm raised its price target from $351 to $379. Source: StockAnalysis

Citi lifts RCL target to $364

Citi maintained its Buy rating on Royal Caribbean on October 29. The firm raised its price target from $362 to $364. Source: Investing.com

Royal Caribbean deploys connected controls across 8,400 cabins

Honeywell said its cabin automation system now powers more than 8,400 staterooms across Royal Caribbean’s three operating Icon Class ships. Passengers can control climate, lighting and other cabin features through the Royal Caribbean app. Source: Honeywell


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $19.14 billion and is growing 8.8%, giving RCL a solid operating growth story. The analyst consensus is strong buy across 26 analysts. The average analyst target is $353.12, above the current $330.64 price, while the most bullish target reaches $425. Freedom Capital Markets upgraded RCL from Hold to Buy on October 28 and raised its target from $351 to $379. Citi maintained its Buy rating on October 29 and lifted its target from $362 to $364. Positive momentum, continued revenue growth and broad analyst support make RCL attractive for investors who believe the current strength can continue.
Bear Case
RCL carries $23.17 billion in total debt against only $851 million in cash. That balance-sheet gap is the clearest fundamental risk in the data. The stock also trades at 19.56 times earnings, so investors are already paying for continued execution and growth. At $330.64, RCL is well above its $222.22 52-week low and has already exceeded the stated $321.07 near-term resistance level. The lowest analyst target is $270, showing that professional expectations are not uniformly bullish. Chief Legal Officer Robert Alexander Lake sold 1,000 shares at $315 on November 2, and the filing did not report that the sale was made under a Rule 10b5-1 plan.
What to Watch
Watch whether RCL can hold above the stated $321.07 near-term resistance after moving through it. A drop below the 20-day moving average of $289.39 would weaken the current momentum picture. Investors should track whether five-day momentum of 5.83% and 20-day momentum of 8.45% remain positive. Revenue growth needs to hold near or above the reported 8.8% to support a 19.56 P/E. Balance-sheet progress matters because the company has $23.17 billion in debt and $851 million in cash. Also watch whether more firms follow the October 28 Freedom Capital upgrade and October 29 Citi target increase, or move closer to the bearish end of the $270 to $425 analyst range.
Analyst Consensus
STRONG BUY

Based on 26 analyst opinions
Low Target
$270.00
Mean Target
$353.12
High Target
$425.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Travel Services
Employees
107,950
Earnings & Dividends
Next Earnings
Jan 26, 2027
EPS (Trailing)
$16.90
Dividend Yield
192.0%
Payout Ratio
32.5%

Frequently Asked Questions

Is RCL a good stock to buy?
RCL has a strong buy recommendation from 26 analysts, 8.8% revenue growth and positive five-day and 20-day momentum. The takeaway is that the data is bullish, but the $23.17 billion debt load remains a major risk.
What is RCL’s price target?
The average analyst target is $353.12, with estimates ranging from $270 to $425. The takeaway is that analysts see potential above the current $330.64 price, but the target range is wide.
What is RCL’s 52-week range?
The key data lists a 52-week range of $222.22 to $356.39, while the technical price series records a high of $350.59 and the same $222.22 low. The takeaway is that RCL trades much closer to its annual high than its low.
Is RCL stock overvalued?
RCL trades at a P/E ratio of 19.56 and has revenue growth of 8.8%. The takeaway is that the valuation requires continued growth, but the provided data does not establish that the stock is definitively overvalued.
How strong is Royal Caribbean’s balance sheet?
Royal Caribbean has $851 million in total cash and $23.17 billion in total debt. The takeaway is that debt is the biggest balance-sheet concern for RCL investors.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.