ALTSTATION.IO

Valero Energy Corporation (VLO) Stock Analysis

By Nova Skye | AltStation.io | Updated October 22, 2026

Price
$420.43
Change
-3.74%
Market Cap
$121.05B
Avg Volume
2.9M

Company Overview

San Antonio-based Valero Energy Corporation operates in the oil and gas refining and marketing sector, processing crude oil and agricultural feedstocks into liquid transportation fuels and petrochemicals. The business runs across three core segments: Refining, Renewable Diesel, and Ethanol. It manufactures gasolines, diesel, jet fuel, heating oil, and asphalt, distributing them through wholesale bulk channels and retail outlets under brands like Valero, Beacon, Diamond Shamrock, and Texaco. The company also sells animal feed co-products like distillers grains from its ethanol operations, while supplying renewable diesel and neat sustainable aviation fuel under the Diamond Green Diesel brand.

Valero is a dominant market leader among independent refiners, operating 14 petroleum refineries with a total throughput capacity of approximately 3.2 million barrels per day across the United States, Canada, and the United Kingdom. Its main competitive edge lies in its high-complexity refining system, which processes cheaper heavy and sour crude oils into premium refined products at lower costs than simpler rivals. Direct competitors like Marathon Petroleum and Phillips 66 compete heavily on volume, but Valero holds an advantage with its heavy Gulf Coast export infrastructure. The primary operational risk is refining margin volatility, where rapid shifts in crack spreads and crude supply differentials directly dictate profitability.

Valero is not shrinking its legacy operations; instead, it is leveraging strong cash flows from refining to fund a profitable pivot into low-carbon liquid fuels. Through its Diamond Green Diesel joint venture, the company produces 1.2 billion gallons of renewable diesel and up to 235 million gallons of sustainable aviation fuel annually, alongside 12 ethanol plants generating 1.7 billion gallons per year. These renewable fuels cut lifecycle greenhouse gas emissions by up to 80%, positioning the company to capture valuable credits in premium regulatory markets like California, Canada, and Europe. This dual strategy gives Valero the flexibility to harvest cash from conventional fuel demand while establishing a structural lead in cleaner replacements.

Key Financials
Market Cap
$121.05B
Revenue
$132.43B
EBITDA
$13.38B
Gross Margin
16.1%
Profit Margin
5.4%
Revenue Growth
51.7%
Total Cash
$7.87B
Total Debt
$11.35B
Free Cash Flow
$8.42B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
17.53
Forward P/E
8.54
Beta
0.59
52-Week High
$461.52
52-Week Low
$159.90
EPS
$23.99
50-Day Avg
$388.96
200-Day Avg
$277.98
Price/Book
4.84
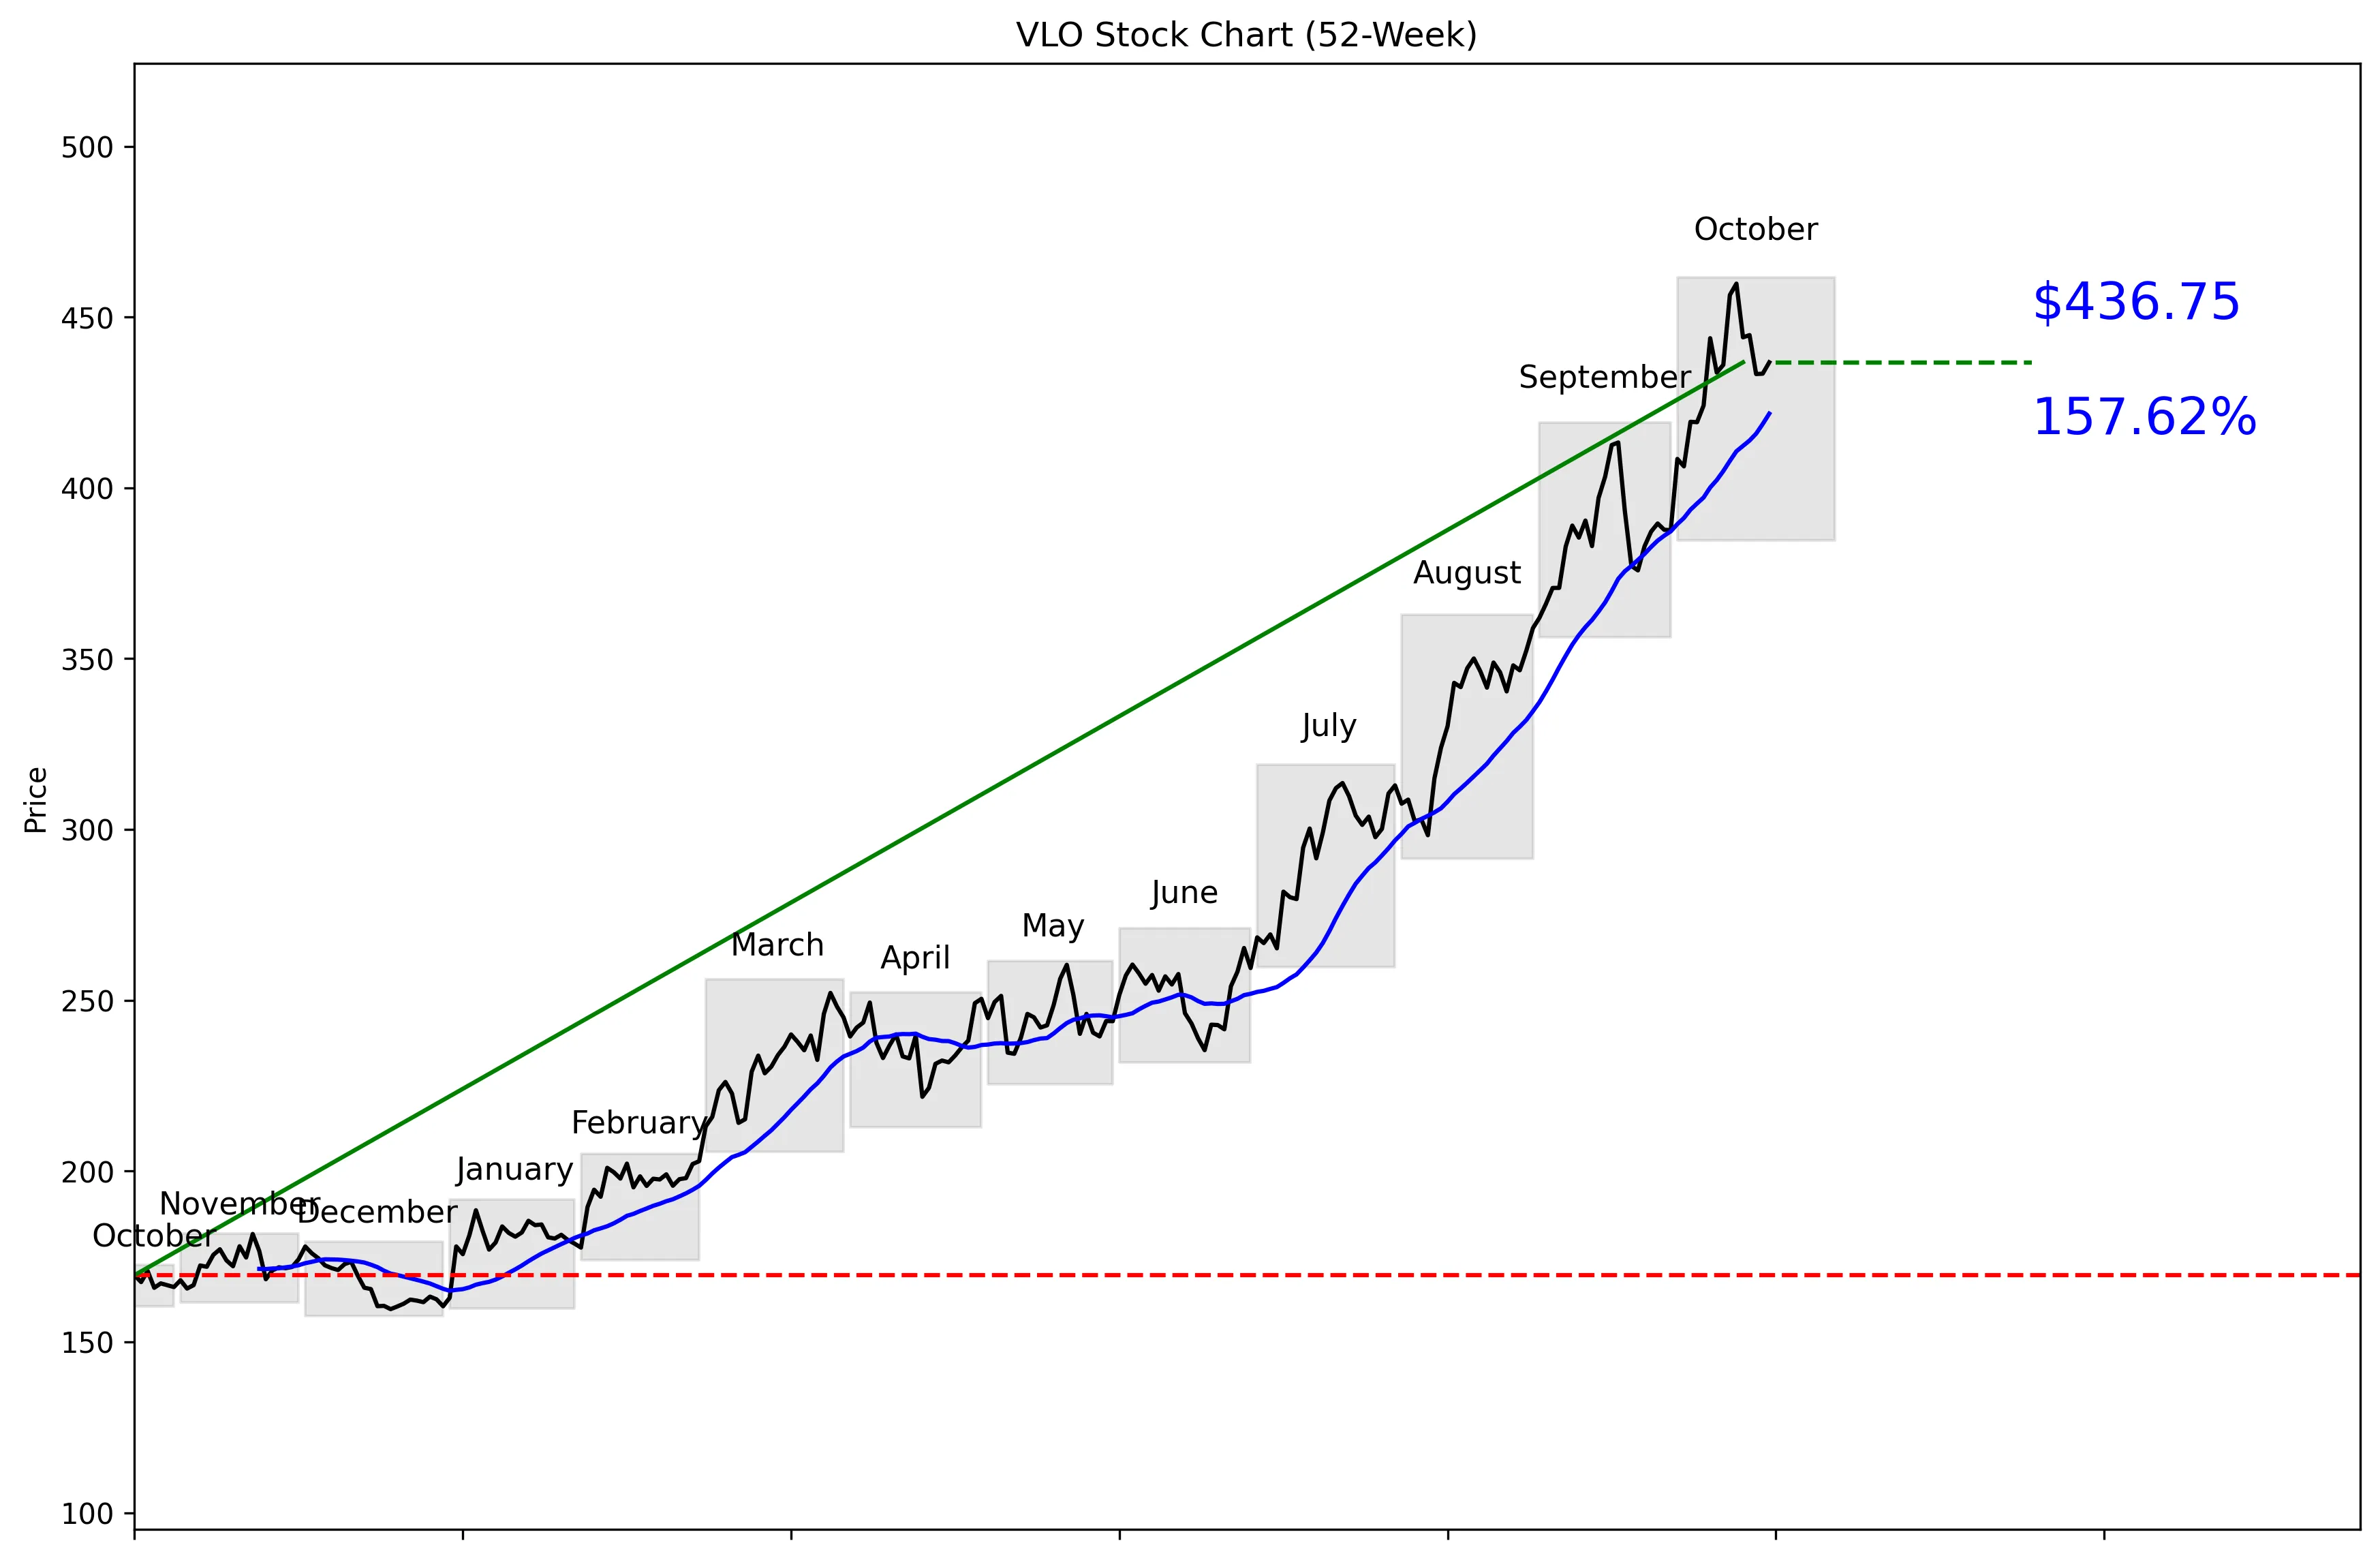
VLO 52-Week Stock Chart
Technical Analysis
VLO trades at $420.43, 92% of the way from its $157.57 52-week low to its $461.52 high. The stock is 5.37% below that high and 177.18% above the low. It sits near its 20-day moving average of $421.72, with the technical data reporting a 3.56% difference versus that average. Momentum is mixed: VLO gained 16.21% over 20 trading days but lost 5.01% over the last five. Near-term support is $375.84, while resistance is $459.78.


Recent News and Developments

Valero profit jumps as shares fall 2.4%

Valero reported third-quarter sales of $46.098 billion, up from $32.168 billion a year earlier, while net income rose to $6.828 billion from $1.095 billion. Diluted earnings reached $23.89 per share versus $3.53, but VLO closed October 22 at $426.28, down 2.4%. Source: S&P Capital IQ

DBS downgrades Valero to Hold

DBS downgraded Valero to Hold on October 19 and set a $436 price target. Valero shares fell following the downgrade. Source: MT Newswires

Raymond James lifts Valero target to $530

Raymond James raised its Valero price target to $530 from $450 on October 19. That was the highest new target among the analyst actions found this week. Source: MT Newswires


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 51.7% is the clearest reason to own VLO. Third-quarter sales increased to $46.098 billion from $32.168 billion, while net income surged to $6.828 billion from $1.095 billion. Diluted earnings climbed to $23.89 per share from $3.53. The stock still trades at 17.53 times earnings despite those gains. Raymond James raised its target to $530 from $450, BMO lifted its target to $505 from $455, and Citigroup moved to $490 from $485. With 19 analysts rating VLO a buy, the bull case rests on strong reported growth and targets well above the current $420.43 price.
Bear Case
VLO is already near the top of its yearly range, leaving less room for error. The stock sits 92% of the way from its 52-week low to high, and the average analyst target of $420.74 is only $0.31 above the $420.43 price. Short-term momentum has weakened by 5.01% over five trading days. Shares also closed October 22 at $426.28, down 2.4%, despite sharply higher third-quarter sales and earnings. DBS downgraded VLO to Hold on October 19 with a $436 target, showing that analysts do not agree on how much upside remains. Total debt of $11.35 billion exceeds total cash of $7.87 billion by $3.48 billion, adding balance-sheet risk if operating results weaken.
What to Watch
The first test is whether VLO can regain its $421.72 20-day moving average and reverse the five-day momentum decline of 5.01%. A move toward the $459.78 near-term resistance would put the stock close to its $461.52 52-week high. A decline toward $375.84 would test near-term support and weaken the current trend. Investors should track whether revenue growth can remain near the reported 51.7% rate after third-quarter sales reached $46.098 billion. Net income and diluted earnings also matter after rising to $6.828 billion and $23.89 per share. Analyst revisions are another catalyst because current targets range from $238 to $530, an unusually wide split around the $420.43 stock price.
Analyst Consensus
BUY

Based on 19 analyst opinions
Low Target
$238.00
Mean Target
$420.74
High Target
$530.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas Refining & Marketing
Employees
9,785
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$23.99
Dividend Yield
110.0%
Payout Ratio
19.4%

Frequently Asked Questions

Is VLO a good stock to buy?
The current recommendation is buy based on 19 analysts, and revenue growth is 51.7%. The takeaway is that analysts are positive, but the stock already sits near the top of its 52-week range.
What is VLO’s price target?
The average analyst target is $420.74, with estimates ranging from $238 to $530. The takeaway is that the average target offers almost no upside from the current $420.43 price.
What is VLO’s 52-week high and low?
The technical data lists a 52-week high of $461.52 and a low of $157.57. The takeaway is that VLO trades 92% of the way from that low to the high.
What are VLO’s support and resistance levels?
Near-term support is the 30-day low of $375.84, while near-term resistance is the 30-day high of $459.78. The takeaway is that these are the key technical thresholds to monitor.
Does VLO pay a dividend?
The provided data does not include a dividend amount or yield. The takeaway is that no dividend conclusion can be made from this data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 22, 2026.