ALTSTATION.IO

Phillips 66 (PSX) Stock Analysis

By Nova Skye | AltStation.io | Updated October 30, 2026

Price
$280.67
Change
+2.58%
Market Cap
$109.48B
Avg Volume
2.8M

Company Overview

Houston-based Phillips 66 is an integrated downstream energy provider operating in the Oil & Gas Refining & Marketing space across 5 segments: Midstream, Chemicals, Refining, Marketing and Specialties, and Renewable Fuels. Founded in 1875, the company processes crude oil, natural gas, and renewable feedstocks into everyday fuels, petrochemicals, plastics, and specialty lubricants. It sells these finished products to commercial airlines, industrial manufacturers, and retail motorists through established brands including Phillips 66, Conoco, 76, JET, Kendall, and Red Line.

Phillips 66 stands as a tier-one market leader in the downstream sector, competing directly with heavyweights like Marathon Petroleum and Valero Energy. Its distinct advantage over pure-play refiners is heavy structural diversification into midstream logistics, gas processing, and chemicals. That extensive network provides dependable fee-based revenue and feedstock flexibility when refining crack spreads collapse. The main headwind facing the firm is margin pressure from cyclical global energy demand and commodity price volatility.

Today, the company is actively pivoting toward higher-value logistics and lower-carbon fuels while running its legacy cash-cow refining operations. A key focus is scaling its Renewable Fuels segment to supply renewable diesel and sustainable aviation fuel while capturing valuable regulatory credits. It is a disciplined, low-hype transition strategy designed to modernize product mix without sacrificing strong core cash generation.

Key Financials
Market Cap
$109.48B
Revenue
$168.19B
EBITDA
$14.65B
Gross Margin
15.1%
Profit Margin
7.5%
Revenue Growth
46.4%
Total Cash
$4.10B
Total Debt
$20.57B
Free Cash Flow
N/A


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
9.00
Forward P/E
9.13
Beta
0.70
52-Week High
$299.39
52-Week Low
$127.16
EPS
$31.18
50-Day Avg
$265.39
200-Day Avg
$198.21
Price/Book
3.55
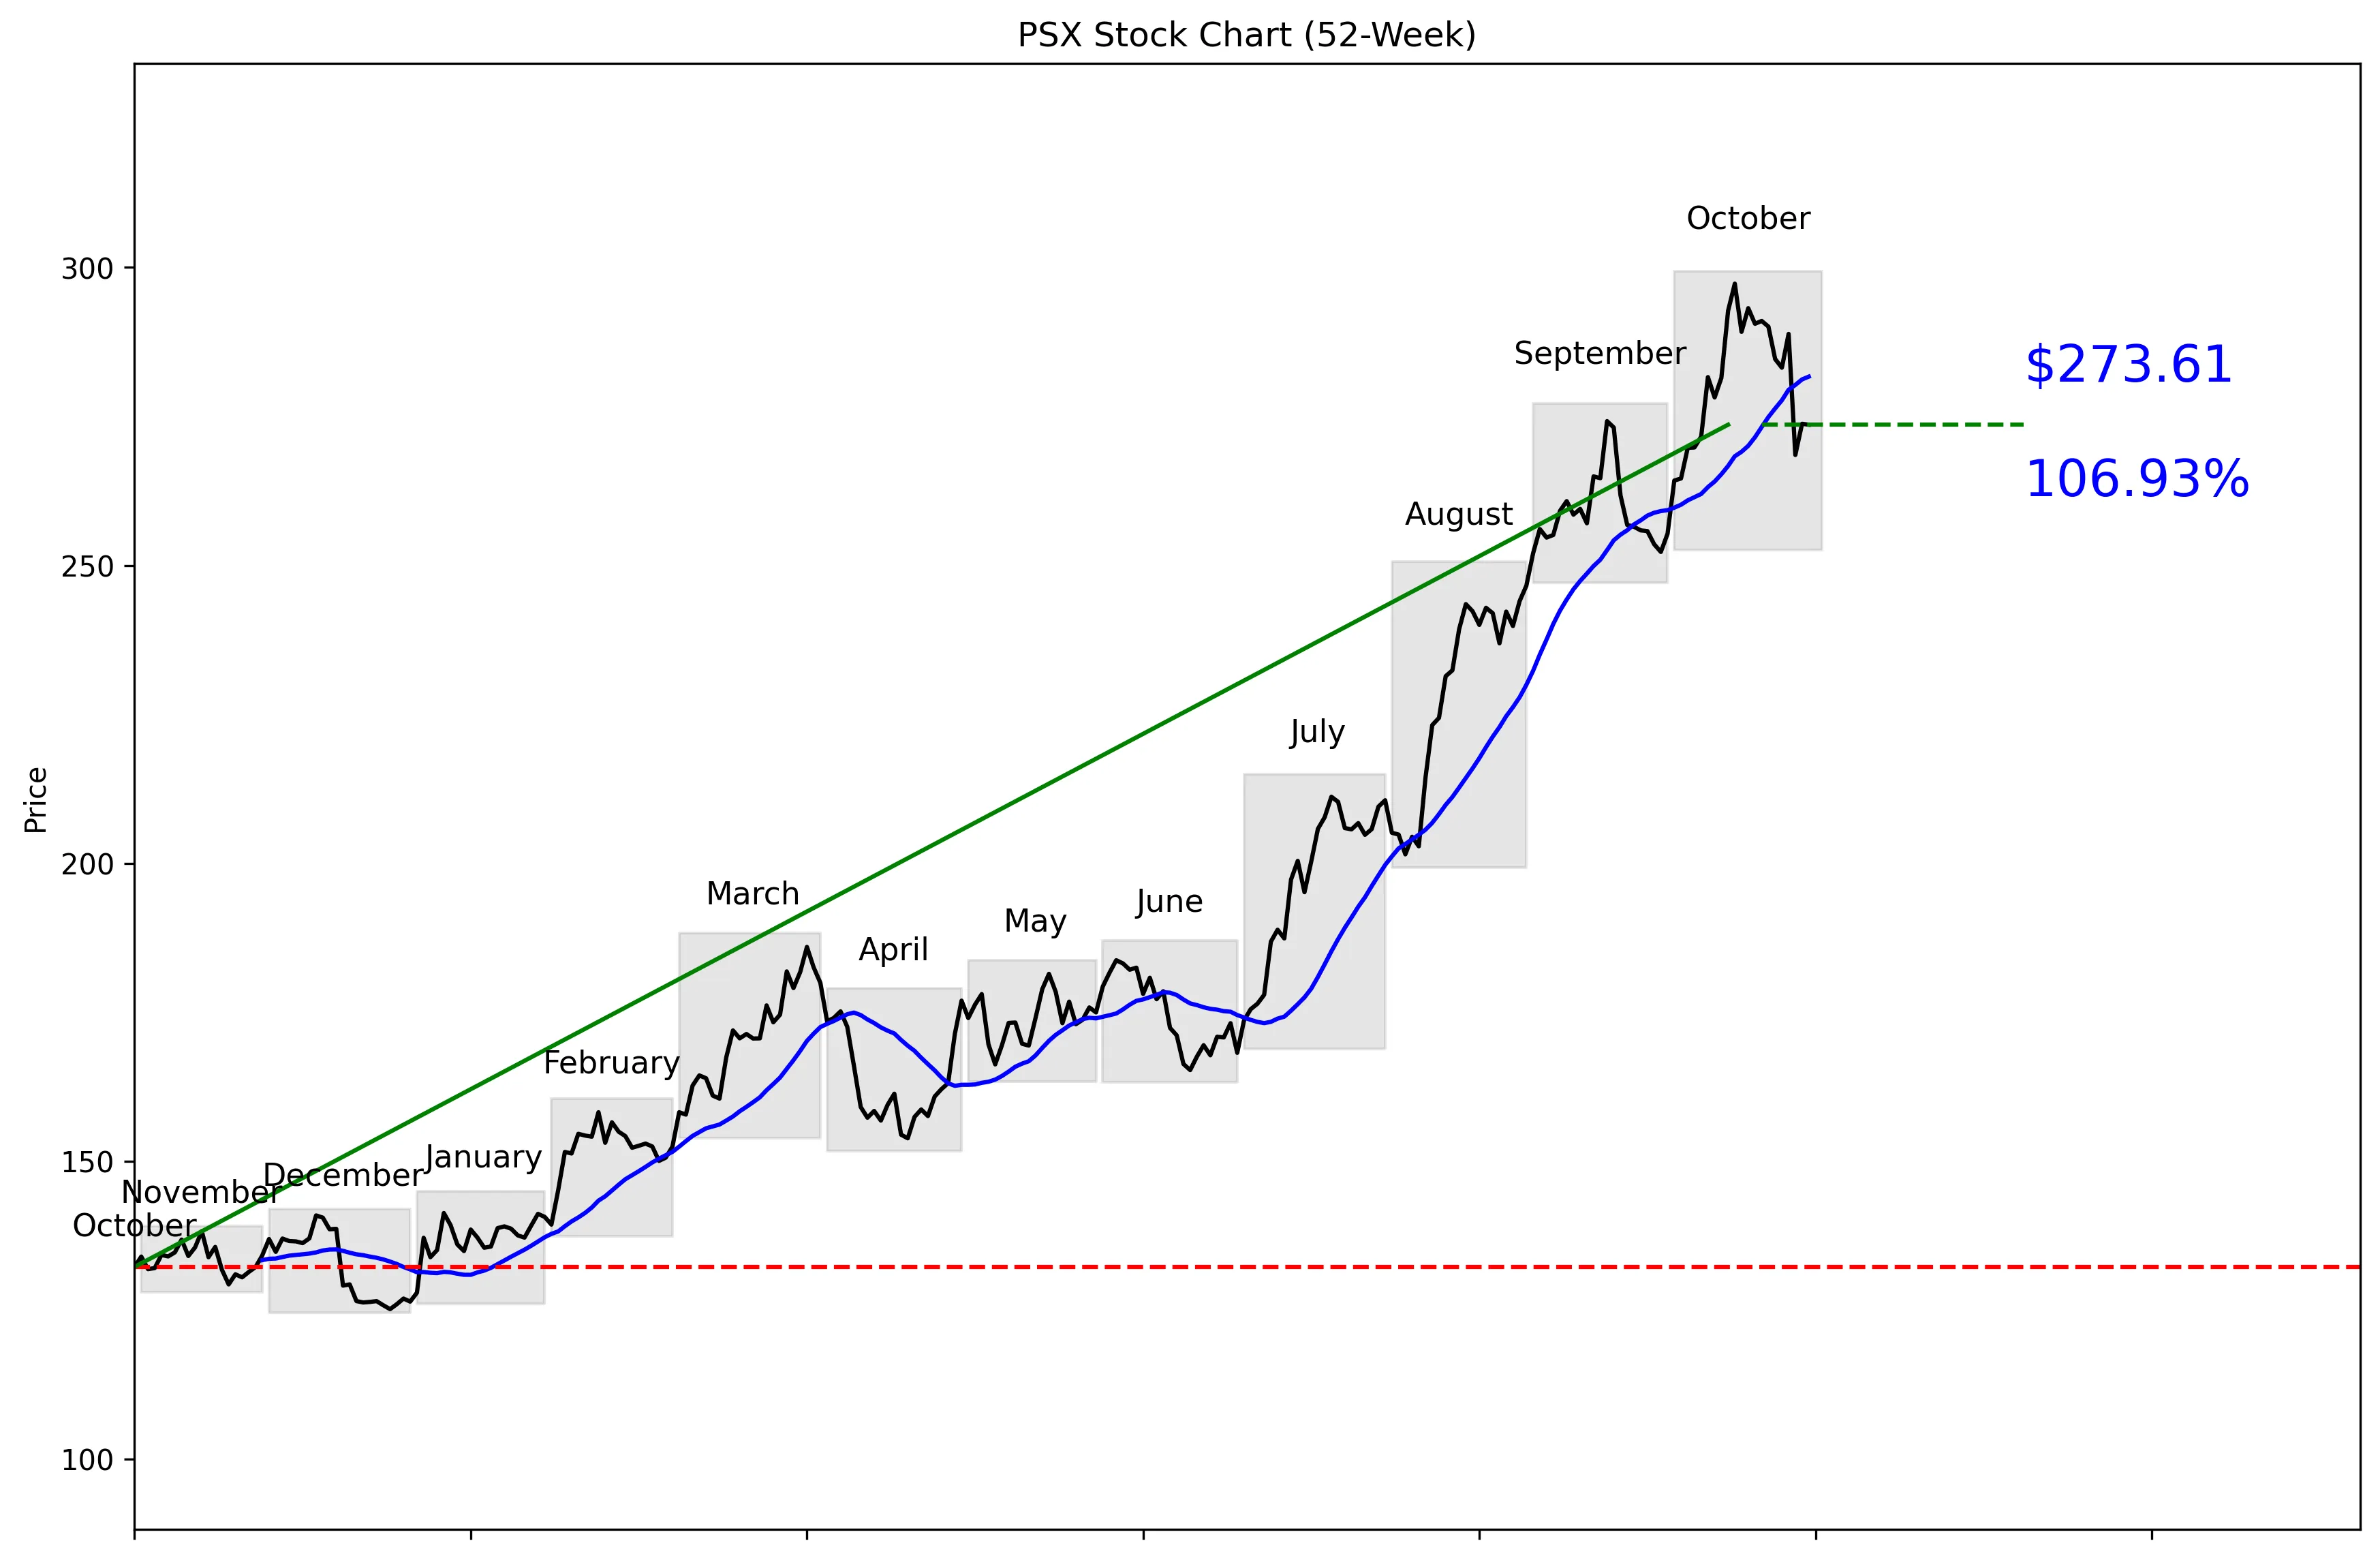
PSX 52-Week Stock Chart
Technical Analysis
PSX trades at $280.67, placing it 85% of the way from its $124.55 52-week low to its $299.39 high. The stock is 8.61% below that high and 119.67% above the low. Price is 2.86% below the 20-day moving average of $281.68, while five-day momentum is negative 3.87%. The 20-day trend remains positive at 3.55%, so the broader move has not broken. Near-term support is $252.25, while resistance sits at $297.29.


Recent News and Developments

Phillips 66 posts $5.6 billion quarter

Phillips 66 reported third-quarter earnings and adjusted earnings of $5.6 billion, or $14.08 per diluted share. Refining utilization reached 98%, the company returned $2.8 billion to shareholders and cut total debt by $2.0 billion to $18.5 billion. Source: Phillips 66

New environmental liabilities disclosed

Phillips 66 disclosed that New Mexico regulators proposed a civil penalty and injunctive terms over alleged DCP violations from 2019 through 2021. The company also expects potential Clean Air Act settlements involving four refineries to include a civil penalty, although no consent decree has been finalized. Source: StockTitan

Freedom Broker drops its Sell rating

Freedom Broker upgraded Phillips 66 from Sell to Hold and raised its price target from $173 to $258. The firm cited record quarterly earnings and wider refining margins, but a Hold rating is still not a bullish call. Source: TipRanks


Market Sentiment and Analyst Recommendations

Bull Case
Phillips 66 just reported third-quarter earnings and adjusted earnings of $5.6 billion, equal to $14.08 per diluted share. Refining utilization reached 98%, showing the company is running its core assets hard and efficiently. Revenue growth of 46.4% adds real weight to the earnings story. Management returned $2.8 billion to shareholders and reduced total debt by $2.0 billion to $18.5 billion during the quarter. At $280.67, PSX trades at 9.00 times earnings, which is not demanding given the reported growth and profitability. The consensus analyst target is $285.95, with the high estimate reaching $350.00, and the overall recommendation is buy from 19 analysts. The reason to own PSX is straightforward: strong refining performance, aggressive capital returns and a low earnings multiple.
Bear Case
PSX is already 85% of the way through its 52-week range, so buyers are entering after a 119.67% climb from the low. The $285.95 consensus target is only $5.28 above the current $280.67 price, leaving limited upside to the average analyst estimate. Near-term momentum is weak, with a 3.87% decline over five trading days and price sitting 2.86% below its 20-day moving average. The stock also fell 7.03% on October 27, showing how quickly strong earnings expectations can reverse. Total debt of $20.57 billion materially exceeds total cash of $4.10 billion, despite the recent debt reduction reported by the company. New Mexico regulators have proposed a civil penalty over alleged violations, and potential Clean Air Act settlements involving four refineries could also include a penalty. The earnings are strong, but the stock price already reflects much of that strength while regulatory liabilities remain unresolved.
What to Watch
The first test is whether PSX can reclaim its $281.68 20-day moving average after the recent 3.87% five-day decline. A move through the $297.29 near-term resistance level would put the $299.39 52-week high back in play. A break below $252.25 support would weaken the current trend and challenge the positive 3.55% 20-day momentum reading. Investors should monitor whether refining utilization can remain near the reported 98% level next quarter. Debt reduction also matters: the company reported cutting total debt by $2.0 billion to $18.5 billion, while Piper Sandler cited net debt below $13 billion. Watch how management allocates excess cash after returning $2.8 billion to shareholders. The regulatory outcome in New Mexico and any finalized Clean Air Act settlement involving the four refineries could change the risk profile.
Analyst Consensus
BUY

Based on 19 analyst opinions
Low Target
$173.00
Mean Target
$285.95
High Target
$350.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas Refining & Marketing
Employees
12,600
Earnings & Dividends
Next Earnings
Oct 28, 2026
EPS (Trailing)
$31.18
Dividend Yield
194.0%
Payout Ratio
16.1%

Frequently Asked Questions

Is PSX a good stock to buy?
The current recommendation is buy based on 19 analysts, and PSX trades at a P/E ratio of 9.00. The takeaway is that analysts are bullish, but the stock is already near the upper end of its 52-week range.
What is the analyst price target for PSX?
The average analyst target is $285.95, with estimates ranging from $173.00 to $350.00. The takeaway is that the average target offers limited upside from the current $280.67 price.
What are PSX stock’s support and resistance levels?
Near-term support is the 30-day low of $252.25, while resistance is the 30-day high of $297.29. The takeaway is that these are the key levels defining the current trading range.
Is PSX stock overvalued?
PSX trades at 9.00 times earnings and sits 85% of the way from its $124.55 52-week low to its $299.39 high. The takeaway is that the earnings multiple is low, but the stock price is already near the top of its annual range.
Does PSX pay a dividend?
The provided data does not include a dividend amount or yield. The takeaway is that investors should not make a dividend decision from this data alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 30, 2026.