ALTSTATION.IO

Akamai Technologies, Inc. (AKAM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$88.51
Change
+0.80%
Market Cap
$12.72B
Avg Volume
4.5M

Company Overview

Akamai Technologies is a Software – Infrastructure provider headquartered in Cambridge, Massachusetts, that sells cybersecurity, cloud computing, and content delivery solutions. The company sells API and web application firewalls, bot defense, media streaming infrastructure, and distributed cloud computing to enterprise clients. Global corporations, media networks, and web platforms buy Akamai to accelerate web traffic, mitigate cyberattacks, and deploy containerized workloads closer to end users.

Akamai is the incumbent giant in content delivery, but legacy CDN bandwidth has become a commoditized, low-margin drag on growth under pressure from competitors like Cloudflare and Fastly. The company’s primary edge is its massive distributed edge architecture, which gives its cybersecurity suite elite positioning in stopping distributed denial-of-service attacks, credential stuffing, and bot scraping. In cloud infrastructure, Akamai is a challenger against hyperscalers, using its edge footprint and the Akamai App Platform to target cost-conscious Kubernetes deployments.

The company is in the middle of a deliberate pivot toward high-margin security and distributed compute. In 2024, Akamai pulled in $3.991 billion in revenue, up 5% year-over-year, with security and compute driving 67% of total sales compared to 60% in 2023. Security revenue rose 16% to top $2 billion, while compute jumped 25% to $630 million, offsetting structural declines in delivery. Strategic moves, such as their alliance with Deloitte Canada to counter AI-driven cyberthreats, show management is doubling down on enterprise resilience rather than fighting a CDN price war.

Key Financials
Market Cap
$12.72B
Revenue
$4.32B
EBITDA
$1.08B
Gross Margin
57.5%
Profit Margin
9.5%
Revenue Growth
5.4%
Total Cash
$3.36B
Total Debt
$9.34B
Free Cash Flow
$710.06M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
32.07
Forward P/E
12.92
Beta
0.62
52-Week High
$165.45
52-Week Low
$70.82
EPS
$2.76
50-Day Avg
$108.75
200-Day Avg
$112.26
Price/Book
2.68
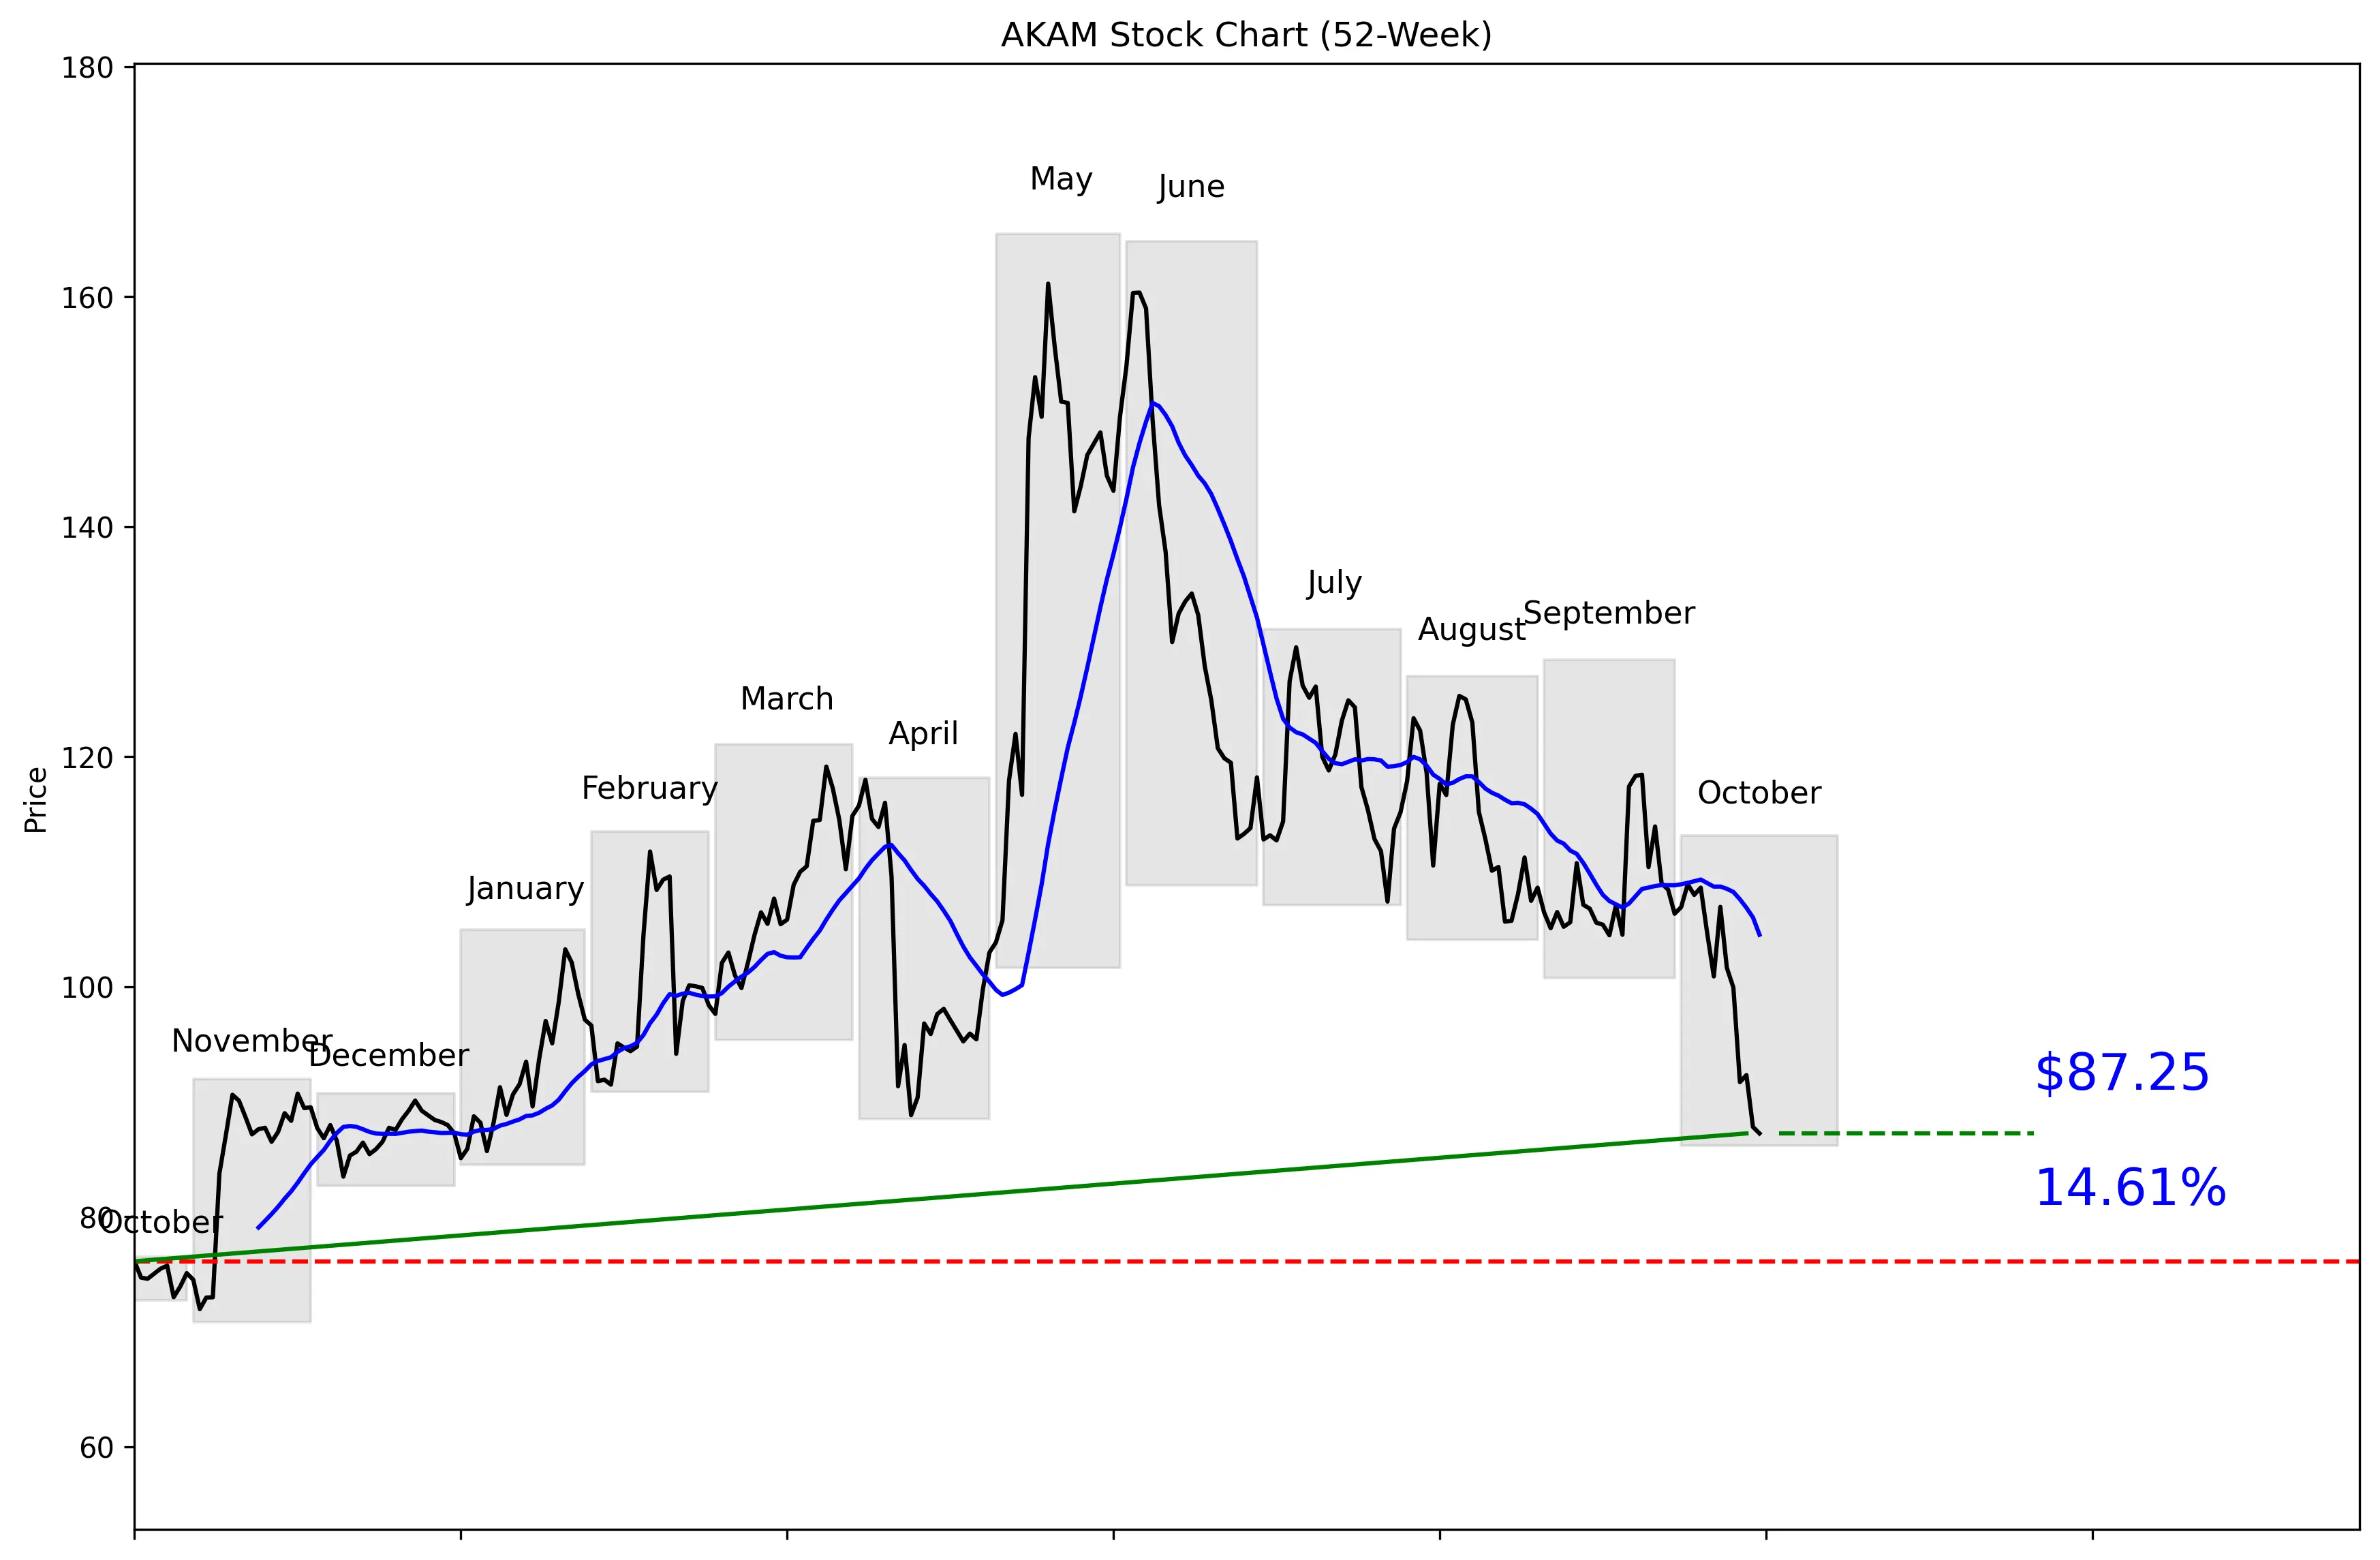
AKAM 52-Week Stock Chart
Technical Analysis
AKAM trades at $88.51, just 17% of the way from its 52-week low of $70.82 to its high of $165.45. The stock is 47.27% below that high but remains 23.20% above the low. Price sits 16.53% below the 20-day moving average of $104.53, confirming a weak short-term trend. Momentum is negative, with declines of 14.17% over five trading days and 25.69% over 20 trading days. Near-term support is $87.25, while resistance is $118.44.


Recent News and Developments

Cyera integration sharpens Guardicore data protection

Akamai detailed an integration that imports Cyera’s data-sensitivity labels into Guardicore Segmentation as dynamic asset tags. Security teams can use those tags to isolate regulated data and enforce controls tied to GDPR, HIPAA, and 23 NYCRR 500. Source: Akamai

Akamai reports stronger cloud and GPU adoption

Akamai said software and SaaS companies represented the overwhelming majority of new cloud customers, while Asia-Pacific, Japan, and Europe accounted for most additions. Demand included NVIDIA RTX PRO 6000 Blackwell Server Edition GPU instances and a developer platform running nearly 1,500 microservices. Source: Akamai

RBC holds Akamai at $135 target

RBC Capital analyst Rishi Jaluria maintained a Hold rating and $135 price target on October 15. This was a reiteration, not an upgrade or downgrade. Source: Stock Analysis


Market Sentiment and Analyst Recommendations

Bull Case
Akamai generated $4.32 billion in revenue, with revenue growth of 5.4%. Cloud demand is expanding among software and SaaS companies, with most new customer additions coming from Asia-Pacific, Japan, and Europe. Adoption includes NVIDIA RTX PRO 6000 Blackwell Server Edition GPU instances and a developer platform operating nearly 1,500 microservices. The Cyera integration strengthens Guardicore Segmentation by letting customers isolate regulated data using dynamic sensitivity tags. Akamai also holds $3.36 billion in cash, giving it meaningful financial resources despite its debt load. The strongest reason to buy is valuation upside: 22 analysts rate the stock a buy, and their $158.87 consensus target sits well above the current $88.51 price.
Bear Case
The chart is broken until proven otherwise, with AKAM down 25.69% over 20 trading days and trading 16.53% below its 20-day moving average. The stock also dropped 8.23% on October 14, falling from $99.93 to $91.71 in one session. Revenue growth of 5.4% is modest for a company trading at 32.07 times earnings. Total debt is $9.34 billion, far above the company’s $3.36 billion in cash. The wide analyst target range of $93.00 to $225.00 shows substantial disagreement about what the business is worth. At $88.51, the stock is only $1.26 above near-term support at $87.25, so another weak session could push it below that level.
What to Watch
The first threshold is $87.25, the 30-day low and immediate support level. A sustained move back above the $104.53 20-day moving average would be the first evidence that the recent decline is losing control. The next major test is $118.44, the 30-day high and stated near-term resistance. Investors should track whether revenue growth improves from 5.4%, because that rate does not comfortably support a P/E of 32.07. Cloud customer additions, regional demand, GPU adoption, and usage of large developer workloads should show whether Akamai’s cloud momentum is translating into broader growth. Investors should also watch whether analysts move closer to RBC’s $135 target or the $158.87 consensus, because the current $93.00 to $225.00 range reflects an unusually wide spread of expectations.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$93.00
Mean Target
$158.87
High Target
$225.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Infrastructure
Employees
11,000
Earnings & Dividends
Next Earnings
Nov 05, 2026
EPS (Trailing)
$2.76
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is AKAM a good stock to buy?
The analyst recommendation is buy based on 22 analysts, with a consensus target of $158.87 versus the current $88.51 price. However, the stock has lost 25.69% over 20 trading days and remains below its 20-day moving average. The takeaway: analysts see upside, but the technical trend is still weak.
What is AKAM’s price target?
The consensus analyst target is $158.87, with estimates ranging from $93.00 to $225.00. That range is well above and unusually wide relative to the current $88.51 price. The takeaway: Wall Street expects upside, but there is substantial disagreement about its size.
Is AKAM undervalued?
AKAM trades at a P/E of 32.07 while revenue is growing 5.4%. The stock is 47.27% below its 52-week high, but a lower share price does not automatically make the valuation cheap. The takeaway: AKAM is depressed relative to its high, but its earnings multiple remains demanding.
What are AKAM’s support and resistance levels?
Near-term support is the 30-day low of $87.25, and near-term resistance is the 30-day high of $118.44. The current price of $88.51 is close to support. The takeaway: $87.25 is the immediate downside level to watch.
Does AKAM pay a dividend?
The provided data does not include dividend information, so a dividend payment or yield cannot be confirmed. The available investment case rests on revenue growth, valuation, analyst targets, and price momentum. The takeaway: do not assume AKAM provides dividend income from this data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.