ALTSTATION.IO

Brown & Brown, Inc. (BRO) Stock Analysis

By Nova Skye | AltStation.io | Updated October 06, 2026

Price
$60.29
Change
+0.63%
Market Cap
$20.17B
Avg Volume
2.3M

Company Overview

Founded in 1939 and headquartered in Daytona Beach, Florida, Brown & Brown, Inc. (BRO) is an insurance broker in the financial services sector operating across the United States, the United Kingdom, and international markets. The business model splits cleanly into two core operating segments: Retail and Specialty Distribution. On the retail side, they sell property and casualty policies, employee benefits, and claims processing services to commercial clients, public entities, and individual consumers. Through Specialty Distribution, which includes their Arrowhead Programs, they underwrite and distribute wholesale coverage, excess and surplus lines, and tailored professional liability policies for medical, legal, and financial specialists.

Brown & Brown functions as a top-tier specialty challenger that avoids commodity pricing pressure by owning high-margin niche markets. Their main competitive edge is the Arrowhead franchise and wholesale network, which manages programs directly for insurance carriers and locks in independent agents across the country. The biggest operational threat in brokerage distribution is the exposure to volatile risk classes like cyber liability and complex excess lines, alongside competition from larger institutional brokerages. Still, their dual-segment setup and broad product spread—from dental malpractice to auto dealer services—insulates them from single-market downturns.

Since rebranding from Poe & Brown, Inc. in April 1999, the company has methodically scaled from a domestic player into an international brokerage platform. Right now, Brown & Brown is actively driving growth by expanding both fee-based risk consulting in Retail and program management in Specialty Distribution. Diversifying into non-insurance dealer products and high-demand liability programs gives them consistent cross-selling opportunities across economic cycles. This is a disciplined specialty distributor built to generate steady cash flow, not a bloated middleman chasing low-margin volume.

Key Financials
Market Cap
$20.17B
Revenue
$6.66B
EBITDA
$2.89B
Gross Margin
56.3%
Profit Margin
18.1%
Revenue Growth
32.4%
Total Cash
$918.00M
Total Debt
$8.07B
Free Cash Flow
$1.64B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
19.02
Forward P/E
12.53
Beta
0.59
52-Week High
$96.55
52-Week Low
$53.81
EPS
$3.17
50-Day Avg
$68.64
200-Day Avg
$67.93
Price/Book
1.58
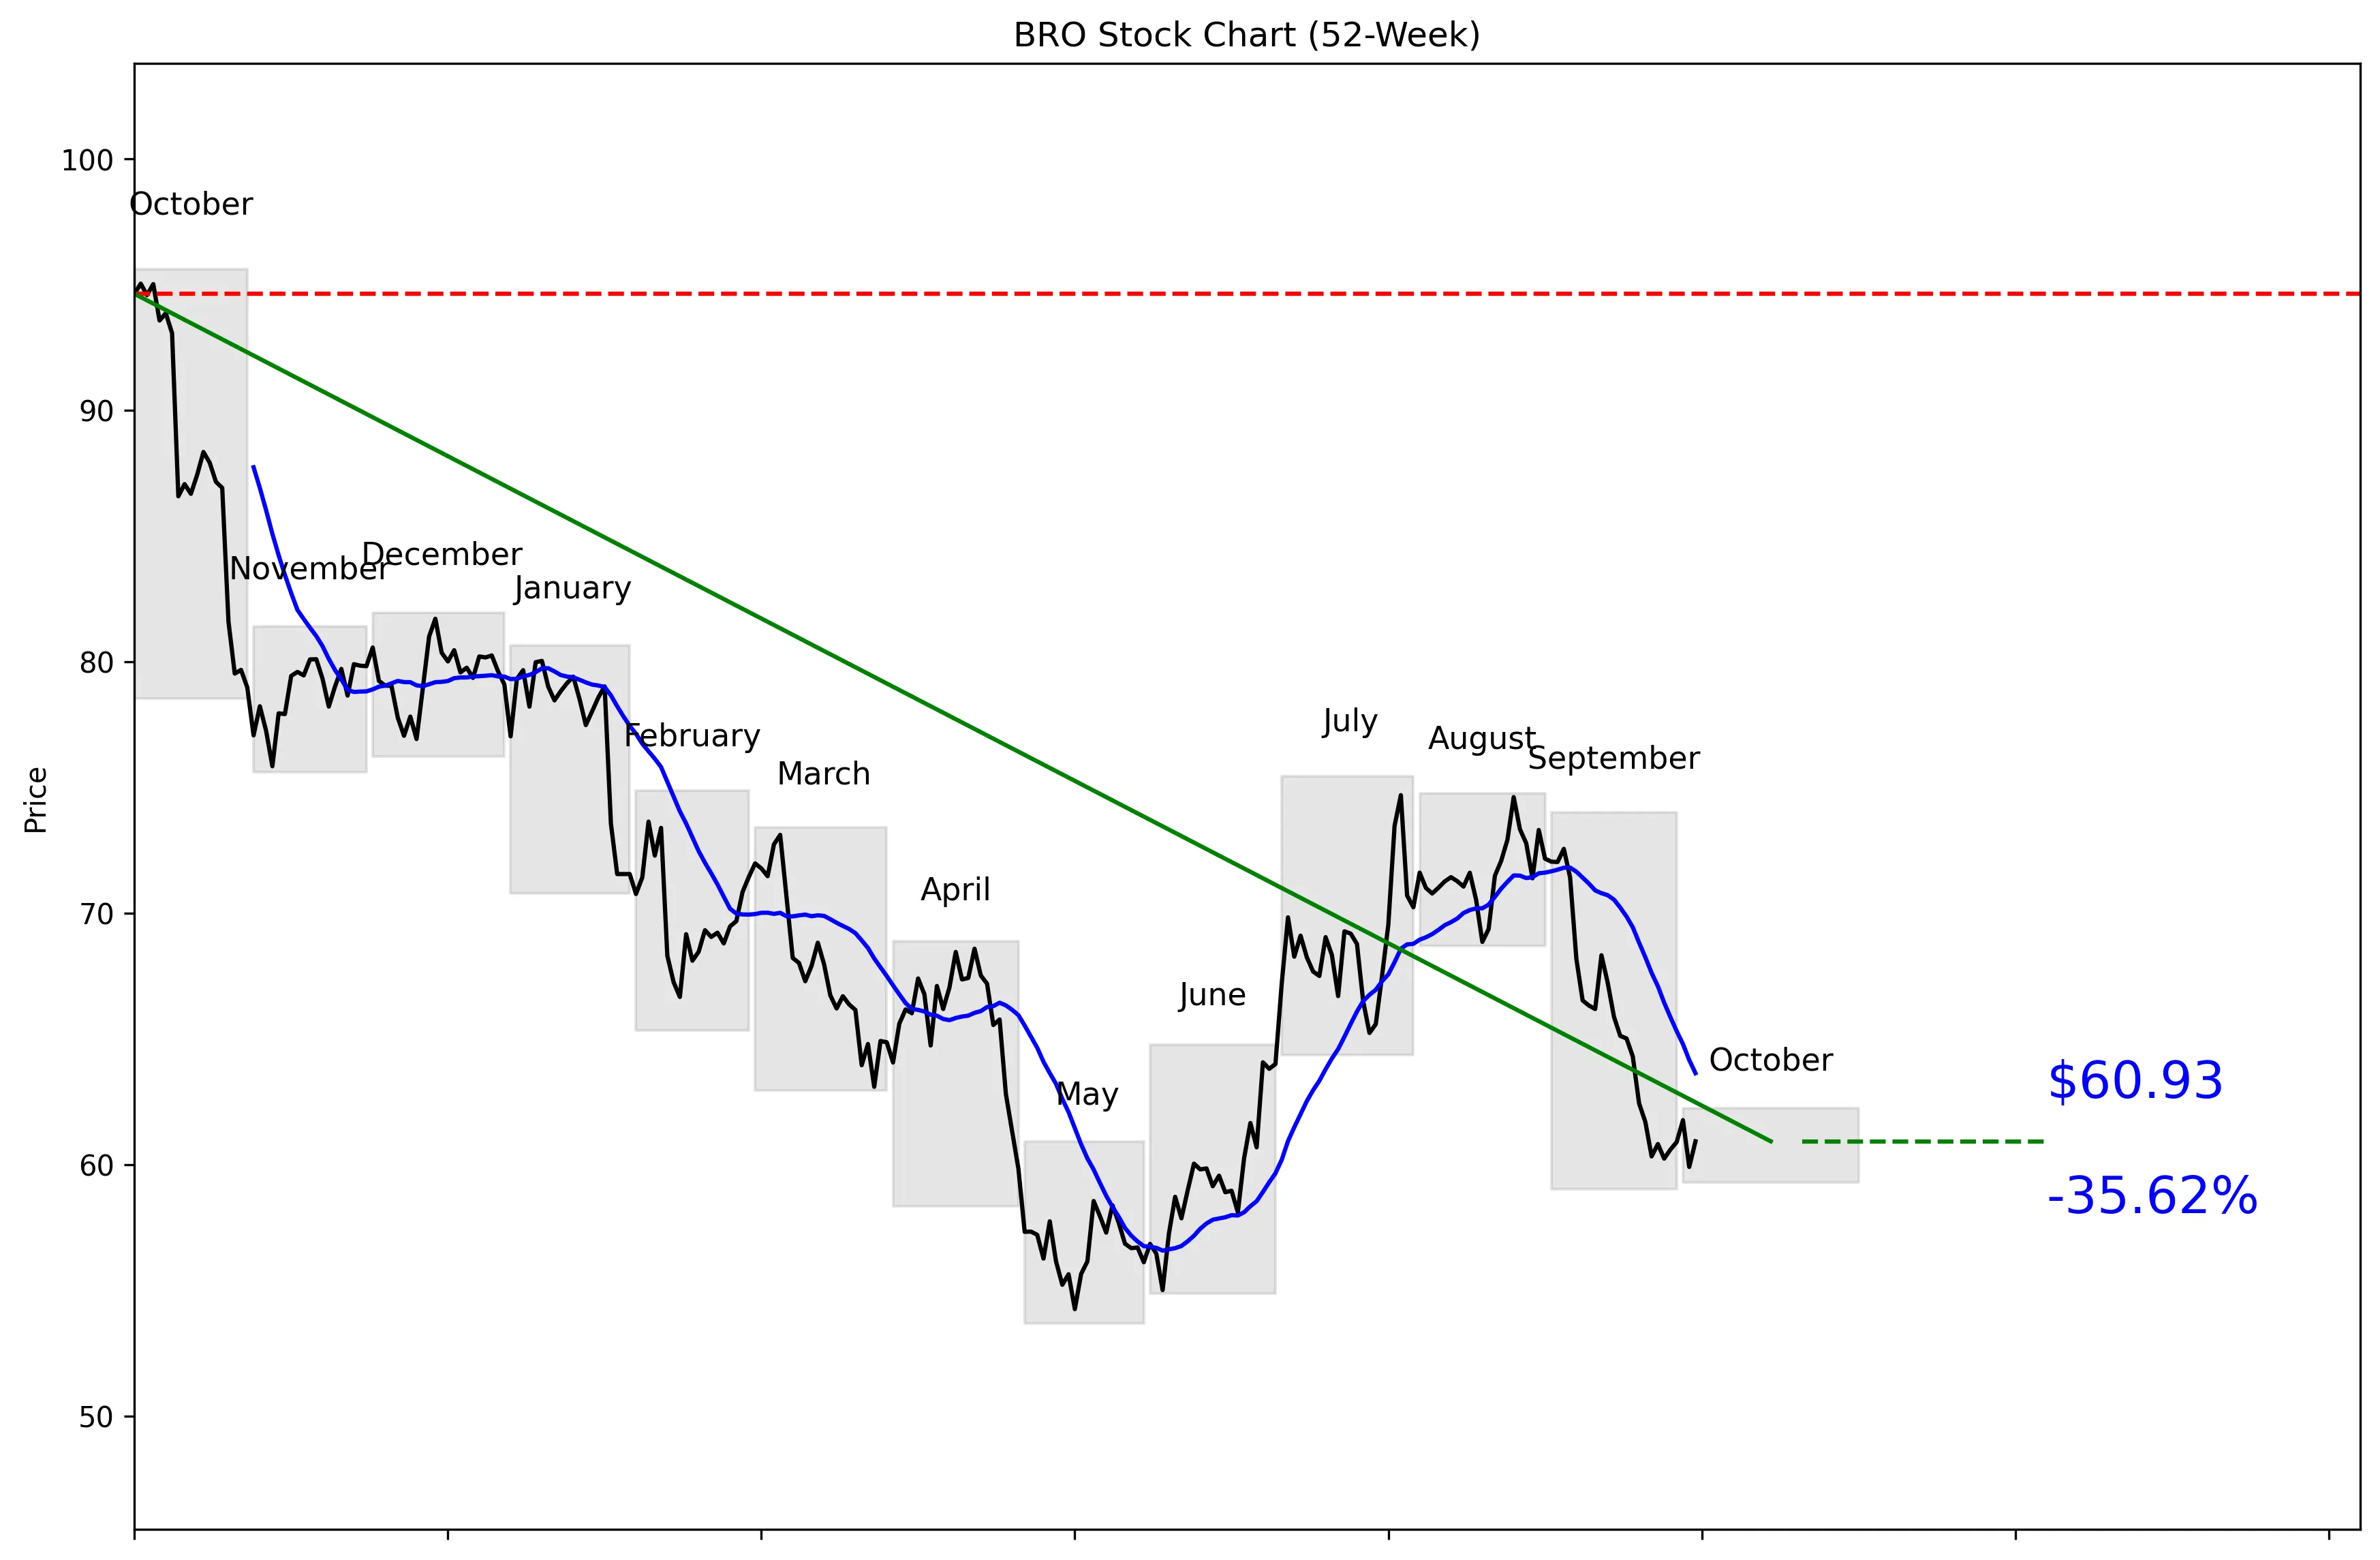
BRO 52-Week Stock Chart
Technical Analysis
BRO trades at $60.29, just 17% of the way from its $53.69 52-week low to its $95.63 high. The stock is 36.28% below that high and 13.49% above the low. It sits 4.25% below its 20-day moving average of $63.64, while 20-day momentum is negative 14.69%. Five-day momentum has improved to 1.15%, but the broader short-term trend remains weak. Near-term support is $59.91, with resistance at $74.62.


Recent News and Developments

Brown & Brown sets third-quarter earnings date

Brown & Brown will release third-quarter 2026 results after the market closes on October 26. CEO J. Powell Brown and CFO R. Andrew Watts will host an investor call at 8:00 a.m. EDT on October 27. Source: Brown & Brown, Inc.

JPMorgan raises BRO target to $83

JPMorgan increased its Brown & Brown price target from $80 to $83 on October 1. The firm kept its Neutral rating, so this was not an upgrade. Source: MT Newswires

BMO cuts BRO target by $9

BMO Capital reduced its Brown & Brown price target from $74 to $65 on October 1. It maintained a Market Perform rating. Source: MT Newswires


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 32.4% is the strongest reason to consider BRO. The company generates $6.66 billion in revenue and carries a $20.17 billion market capitalization. At 19.02 times earnings, investors are not being asked to pay the stock’s former peak price after a 36.28% decline from its 52-week high. The average analyst target is $75.69, above the current $60.29 price, while the highest target is $90.00. JPMorgan raised its target from $80 to $83 on October 1, although it kept a Neutral rating. The stock also recovered 1.70% on October 5 after its 3.01% decline on October 2. The bull case is straightforward: strong revenue growth, a sharply reduced share price, and meaningful room to the consensus target.
Bear Case
The chart is weak, with BRO trading 4.25% below its $63.64 20-day moving average. Its negative 14.69% momentum over the last 20 trading days shows that sellers still control the broader short-term trend. The balance sheet carries $8.07 billion in total debt against $918.00 million in cash, leaving limited financial flexibility compared with the debt load. Analysts remain cautious: the consensus recommendation is hold across 16 analysts. BMO cut its target from $74 to $65 on October 1, while Goldman Sachs lowered its target from $73 to $68 and kept a Neutral rating. The lowest analyst target is $60.00, slightly below the current $60.29 price. BRO needs to prove that its 32.4% revenue growth can support a 19.02 P/E and overcome the debt concern.
What to Watch
Brown & Brown will report third-quarter 2026 results after the market closes on October 26. CEO J. Powell Brown and CFO R. Andrew Watts will host the investor call at 8:00 a.m. EDT on October 27. Revenue growth is the central metric because the current rate is 32.4%. Investors should also watch total debt of $8.07 billion and cash of $918.00 million for evidence that the balance sheet is improving. On the chart, $59.91 is the immediate support level; a break below it would reinforce the negative 20-day momentum. A move above the $63.64 moving average would be an initial sign of stabilization, while $74.62 remains the near-term resistance level. The next report needs to support the growth story because recent analyst targets now span from $60.00 to $90.00.
Analyst Consensus
HOLD

Based on 16 analyst opinions
Low Target
$60.00
Mean Target
$75.69
High Target
$90.00


Earnings and Financial Data

Sector
Financial Services
Industry
Insurance Brokers
Employees
22,888
Earnings & Dividends
Next Earnings
Oct 26, 2026
EPS (Trailing)
$3.17
Dividend Yield
110.0%
Payout Ratio
20.3%

Frequently Asked Questions

Is BRO a good stock to buy?
BRO has 32.4% revenue growth, but the consensus recommendation from 16 analysts is hold. The clear takeaway is that the growth is attractive, but the available data does not support an aggressive buy call.
What is BRO’s price target?
The average analyst target is $75.69, with a range from $60.00 to $90.00. The clear takeaway is that the consensus target sits above the current $60.29 price.
Is BRO stock undervalued?
BRO trades at a P/E of 19.02 and is 36.28% below its technical 52-week high of $95.63. The clear takeaway is that the stock is far below its high, but the supplied data does not establish a definitive fair value.
What are BRO’s support and resistance levels?
Near-term support is the 30-day low of $59.91, while near-term resistance is the 30-day high of $74.62. The clear takeaway is that BRO is currently trading close to support.
How strong is BRO’s balance sheet?
Brown & Brown has $918.00 million in total cash and $8.07 billion in total debt. The clear takeaway is that debt substantially exceeds cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 06, 2026.