ALTSTATION.IO

Omnicom Group Inc. (OMC) Stock Analysis

By Nova Skye | AltStation.io | Updated October 29, 2026

Price
$77.31
Change
-1.81%
Market Cap
$21.21B
Avg Volume
2.8M

Company Overview

Omnicom Group Inc. is a global advertising and marketing holding company based in New York. Operating in the Communication Services sector within the Advertising Agencies industry, the firm sells end-to-end commercial campaigns and media services to major corporate clients. Its offerings span media planning and buying, precision marketing, public relations, healthcare communications, and customer data analytics. Brands hire Omnicom to handle everything from large-scale creative advertising to targeted retail media, digital commerce optimization, and crisis communications.

Omnicom sits as an established market leader in the agency space, backed by an operating track record that dates back to its incorporation in 1944. Its global reach across North America, Latin America, EMEA, and the Asia Pacific gives it the scale necessary to win and service multinational corporate accounts. The company’s key advantage is its cross-discipline roster, integrating specialized capabilities like CRM and decision sciences directly with creative production. The primary operational challenge comes from shifting client budgets toward measurable performance marketing and direct digital channels.

Right now, Omnicom relies on a balanced geographic footprint to manage uneven economic conditions across its regional markets. The company’s strategic focus centers on expanding high-margin capabilities, specifically in data analytics, e-commerce, and precision marketing to keep pace with modern brand demands. Rather than relying solely on traditional studio production, it continues integrating data-driven decision making across its subsidiary network. The stock remains a direct barometer for global corporate marketing budgets and institutional ad spending.

Key Financials
Market Cap
$21.21B
Revenue
$24.76B
EBITDA
$4.16B
Gross Margin
19.3%
Profit Margin
2.8%
Revenue Growth
59.1%
Total Cash
$3.80B
Total Debt
$11.36B
Free Cash Flow
$4.59B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
78.09
Forward P/E
6.87
Beta
0.70
52-Week High
$89.57
52-Week Low
$66.33
EPS
$0.99
50-Day Avg
$80.26
200-Day Avg
$78.20
Price/Book
2.12
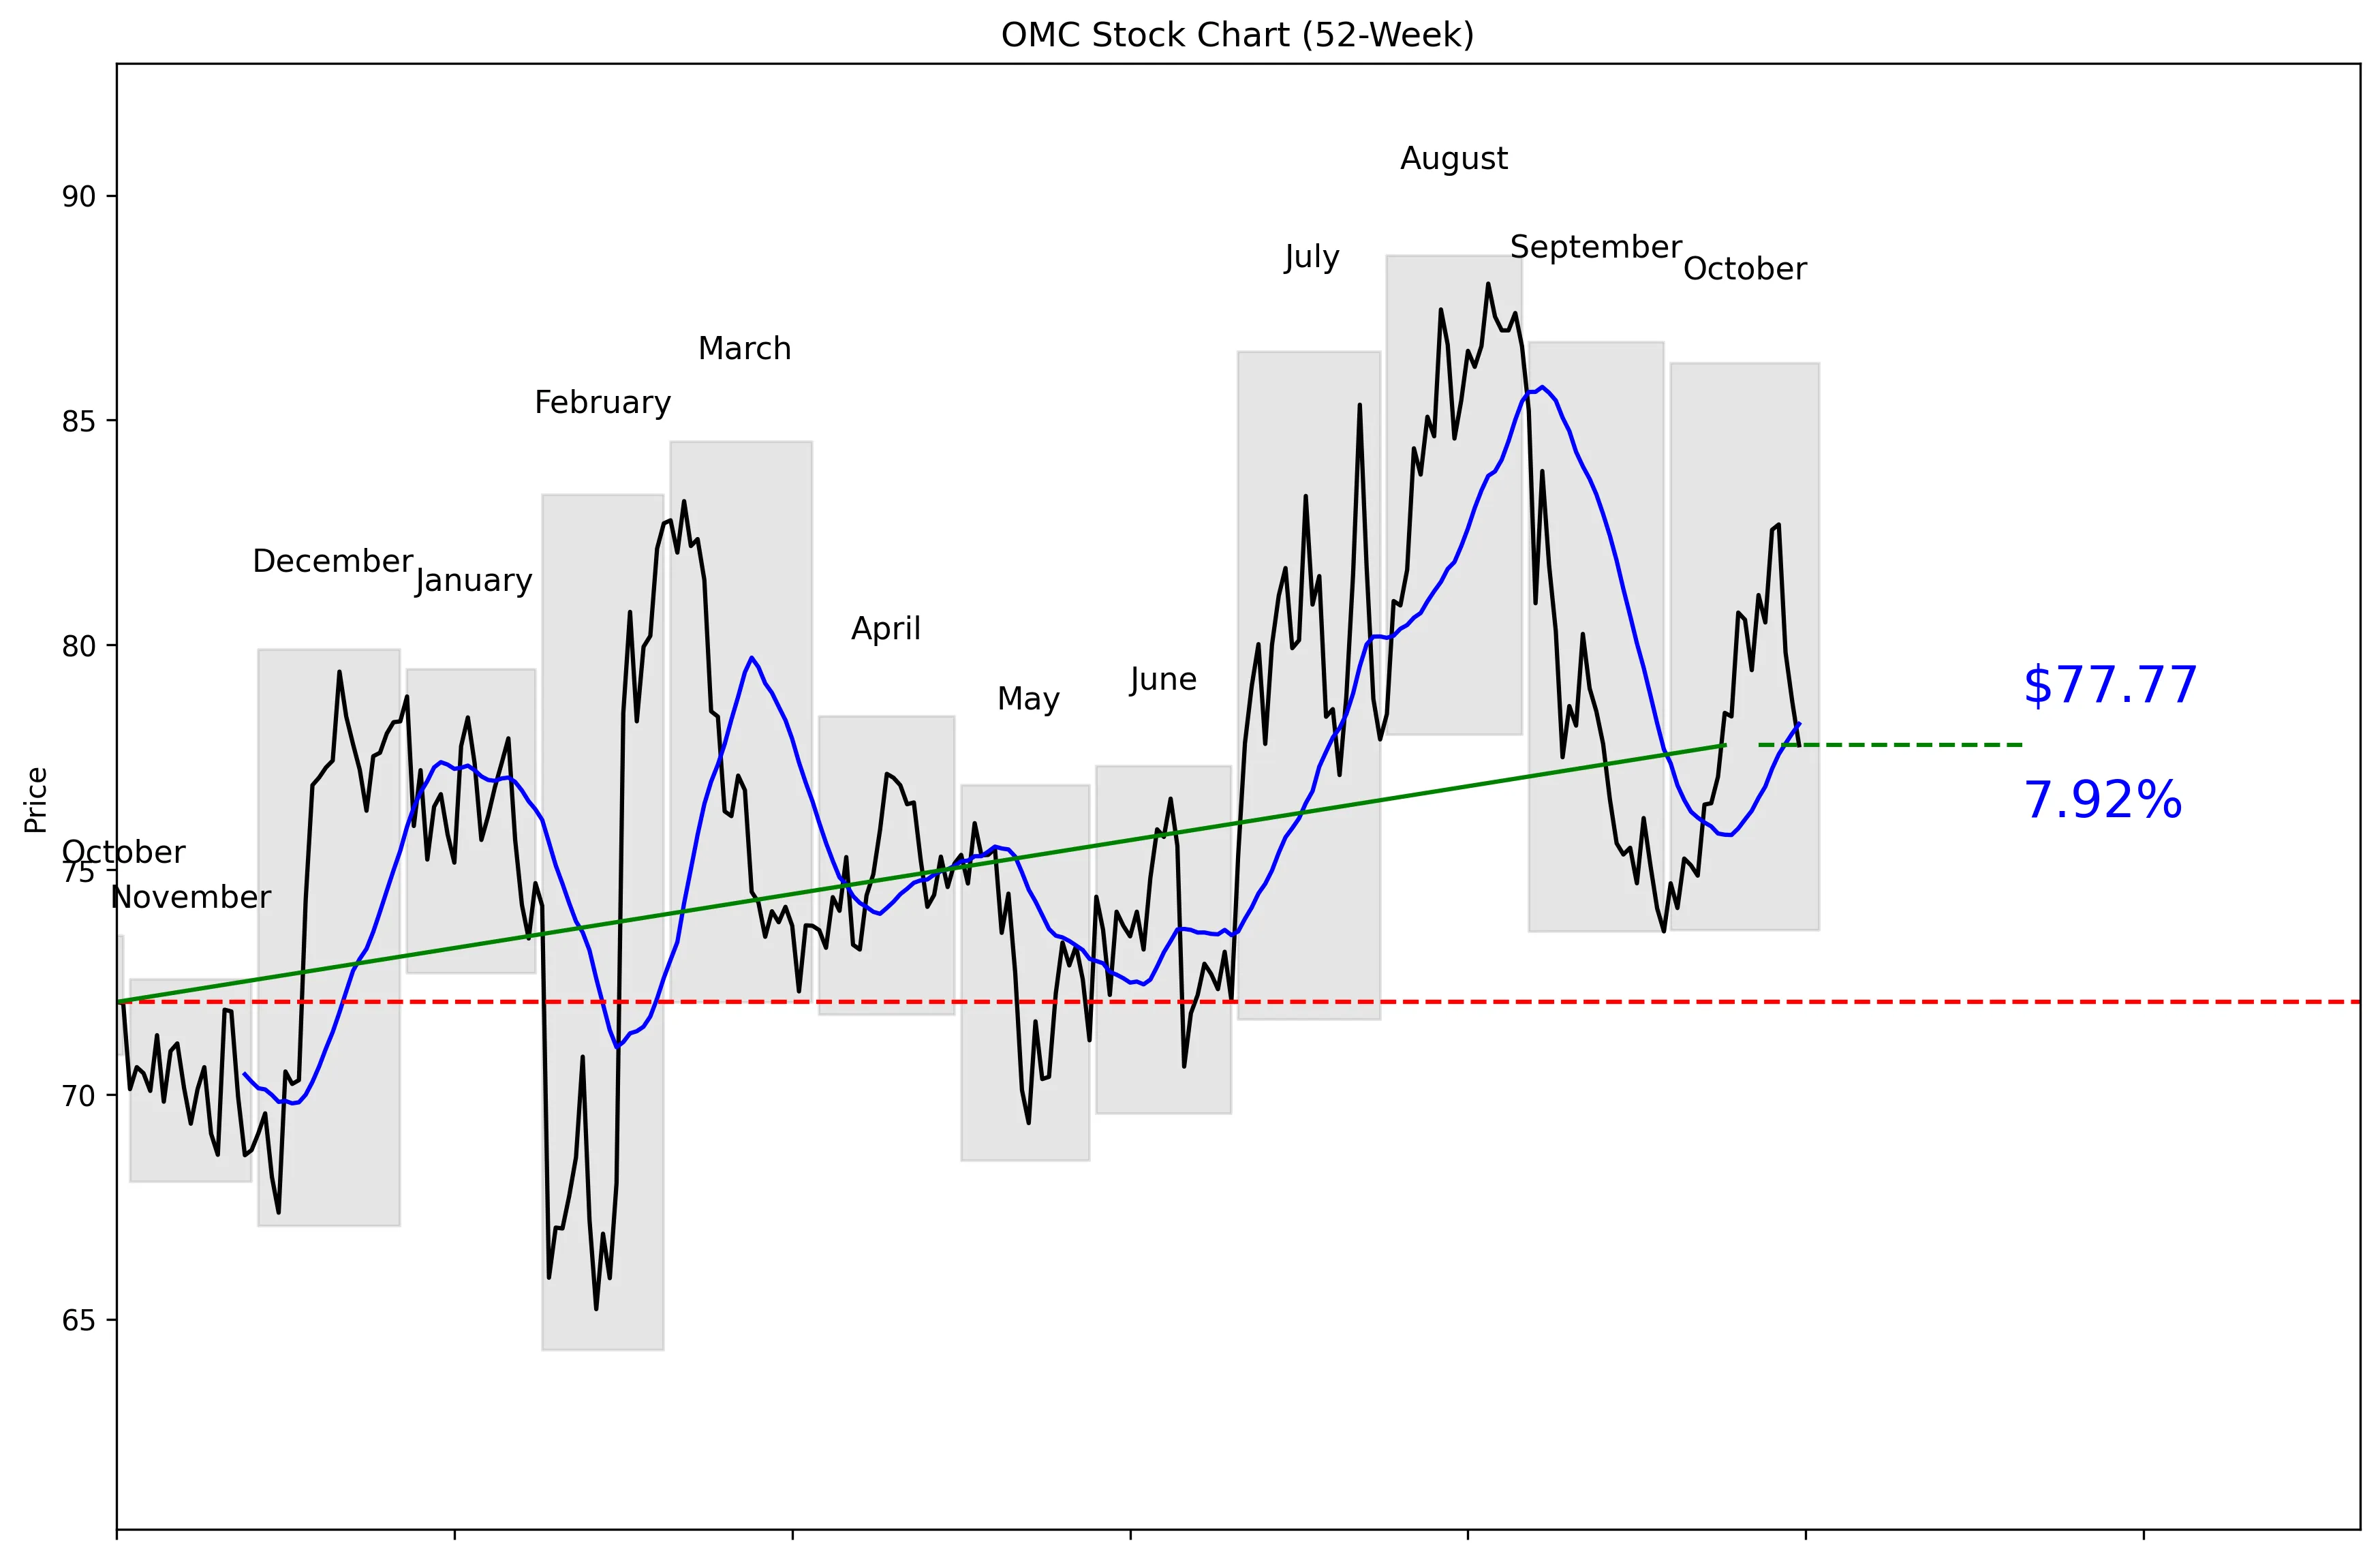
OMC 52-Week Stock Chart
Technical Analysis
OMC trades at $77.31, 55% of the way from its technical 52-week low of $64.32 to its high of $88.66. The stock is 12.28% below that high and 20.91% above the low. Price is 0.61% below the 20-day moving average of $78.24, while five-day momentum is negative 3.39%. The broader 20-day momentum remains positive at 5.62%, so the recent weakness has not erased the monthly advance. Near-term support is $73.63, with resistance at $82.68.


Recent News and Developments

Omnicom posts 7.2% organic growth

Omnicom reported third-quarter revenue of $6.4 billion, with core operations producing $6.0 billion and 7.2% organic growth. Adjusted EPS rose 22% to $2.73, while adjusted EBITA reached $1.1 billion with an 18.2% core-operations margin. Source: Omnicom

Omnicom wins Coca-Cola’s North American media account

Coca-Cola selected Omnicom as its media partner in North America following a global review announced October 22. WPP retained Coca-Cola’s media business in most other markets, making this a targeted but meaningful client win for Omnicom. Source: The Coca-Cola Company

Analysts split on Omnicom after earnings

Wells Fargo raised its OMC price target from $93 to $97 and maintained an Overweight rating on October 23, while Morgan Stanley raised its target from $83 to $85 and stayed at Equal-Weight. JPMorgan cut its target from $115 to $111 but kept its Overweight rating. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 59.1% is the strongest number in the bull case. Third-quarter revenue reached $6.4 billion, including $6.0 billion from core operations and 7.2% organic growth. Adjusted EPS increased 22% to $2.73, while adjusted EBITA reached $1.1 billion with an 18.2% core-operations margin. Coca-Cola selecting Omnicom for its North American media account adds a meaningful client win. The average analyst target is $101.17 versus a current price of $77.31, and 12 analysts collectively rate the stock a buy. The case for buying OMC rests on strong growth, solid operating performance, and analyst targets that remain above the current price.
Bear Case
The P/E ratio of 78.09 is difficult to defend without sustained growth. Omnicom holds $3.80 billion in cash against $11.36 billion in total debt, leaving debt well above available cash. Analyst conviction is also uneven despite the overall buy recommendation. Morgan Stanley maintained an Equal-Weight rating with an $85 target, while Barclays kept an Equal-Weight rating and cut its target from $88 to $87. JPMorgan reduced its target from $115 to $111, and the shares fell 3.45% to $79.83 after the Barclays cut. The downside of the analyst target range is $77.00, slightly below the current $77.31 price, so the market is not dismissing the risk of limited upside.
What to Watch
The next quarterly report needs to show whether 7.2% organic growth and the 22% increase in adjusted EPS can continue. Investors should track whether the 18.2% core-operations margin holds as Omnicom handles $11.36 billion in debt. The Coca-Cola North American media win announced October 22 is a catalyst, but the data provided does not quantify its future revenue contribution. Analyst revisions also matter after Wells Fargo raised its target to $97, Morgan Stanley raised its target to $85, JPMorgan cut its target to $111, and Barclays cut its target to $87. On the chart, a break below $73.63 would weaken the near-term setup, while a move above $82.68 would clear the stated 30-day resistance. The thesis strengthens if growth and margins hold while price clears $82.68; it weakens if growth slows and price loses $73.63.
Analyst Consensus
BUY

Based on 12 analyst opinions
Low Target
$77.00
Mean Target
$101.17
High Target
$130.00


Earnings and Financial Data

Sector
Communication Services
Industry
Advertising Agencies
Employees
120,000
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$0.99
Dividend Yield
406.0%
Payout Ratio
323.2%

Frequently Asked Questions

Is OMC a good stock to buy?
The consensus recommendation is buy based on 12 analysts, with an average target of $101.17 versus a current price of $77.31. The P/E of 78.09 and total debt of $11.36 billion make valuation and leverage important risks. Takeaway: Analysts are positive, but OMC is not a low-risk buy.
What is OMC’s price target?
The average analyst target is $101.17, with estimates ranging from $77.00 to $130.00. OMC currently trades at $77.31. Takeaway: The average target points higher, but the low target offers almost no upside.
What are OMC’s support and resistance levels?
Near-term support is the 30-day low of $73.63, while resistance is the 30-day high of $82.68. The current price of $77.31 sits between those levels. Takeaway: Watch $73.63 for downside risk and $82.68 for a breakout.
Is OMC overvalued?
OMC trades at a P/E ratio of 78.09 while reporting revenue growth of 59.1%. The data provided does not include a historical or peer P/E comparison. Takeaway: The valuation is demanding and requires strong growth to continue.
Does OMC pay a dividend?
The provided data does not include a dividend rate, yield, or payment history. A dividend conclusion cannot be made from the available figures. Takeaway: Verify current dividend information before treating OMC as an income investment.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 29, 2026.