ALTSTATION.IO

Comcast Corporation (CMCSA) Stock Analysis

By Nova Skye | AltStation.io | Updated November 02, 2026

Price
$23.22
Change
+4.27%
Market Cap
$82.45B
Avg Volume
28.7M

Company Overview

Comcast Corporation is a Philadelphia-based telecom and media giant operating in the Communication Services sector. The company sells residential broadband, wireless connectivity, and video services to consumer households, alongside dedicated ethernet and voice solutions for commercial clients ranging from small businesses to large enterprises. Beyond core telecom infrastructure, it monetizes content through NBCUniversal broadcast networks like NBC and Telemundo, the Peacock streaming service, and film production studios. It also runs international Sky entertainment networks and Universal theme parks located in Orlando, Hollywood, Osaka, and Beijing.

Comcast is an established market leader in broadband and media distribution, but it operates in a heavily pressured telecom environment. Its competitive edge comes from extensive last-mile network infrastructure and high-margin business connectivity contracts. The core vulnerability is cord-cutting, which steadily drains subscriber volume from traditional linear cable networks. To hold its ground against broadband competitors and streaming platforms, Comcast relies on bundling wireless services with residential internet to protect its customer base.

Comcast is currently in the middle of an operational pivot away from legacy cable packages and toward high-capacity data, wireless, and direct-to-consumer platforms. Strategic priorities center on scaling the Peacock streaming platform, expanding mobile subscriber lines, and growing enterprise ethernet services. At the same time, the company continues leveraging its experiential entertainment segment through its global Universal theme park operations. The operational objective is straightforward: maximize cash flow from mature distribution assets while investing to maintain broadband scale and expand digital streaming.

Key Financials
Market Cap
$82.45B
Revenue
$123.01B
EBITDA
$33.54B
Gross Margin
69.8%
Profit Margin
9.2%
Revenue Growth
-6.1%
Total Cash
$7.60B
Total Debt
$87.37B
Free Cash Flow
$13.08B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
7.35
Forward P/E
6.59
Beta
0.67
52-Week High
$32.86
52-Week Low
$20.48
EPS
$3.16
50-Day Avg
$23.40
200-Day Avg
$26.08
Price/Book
0.89
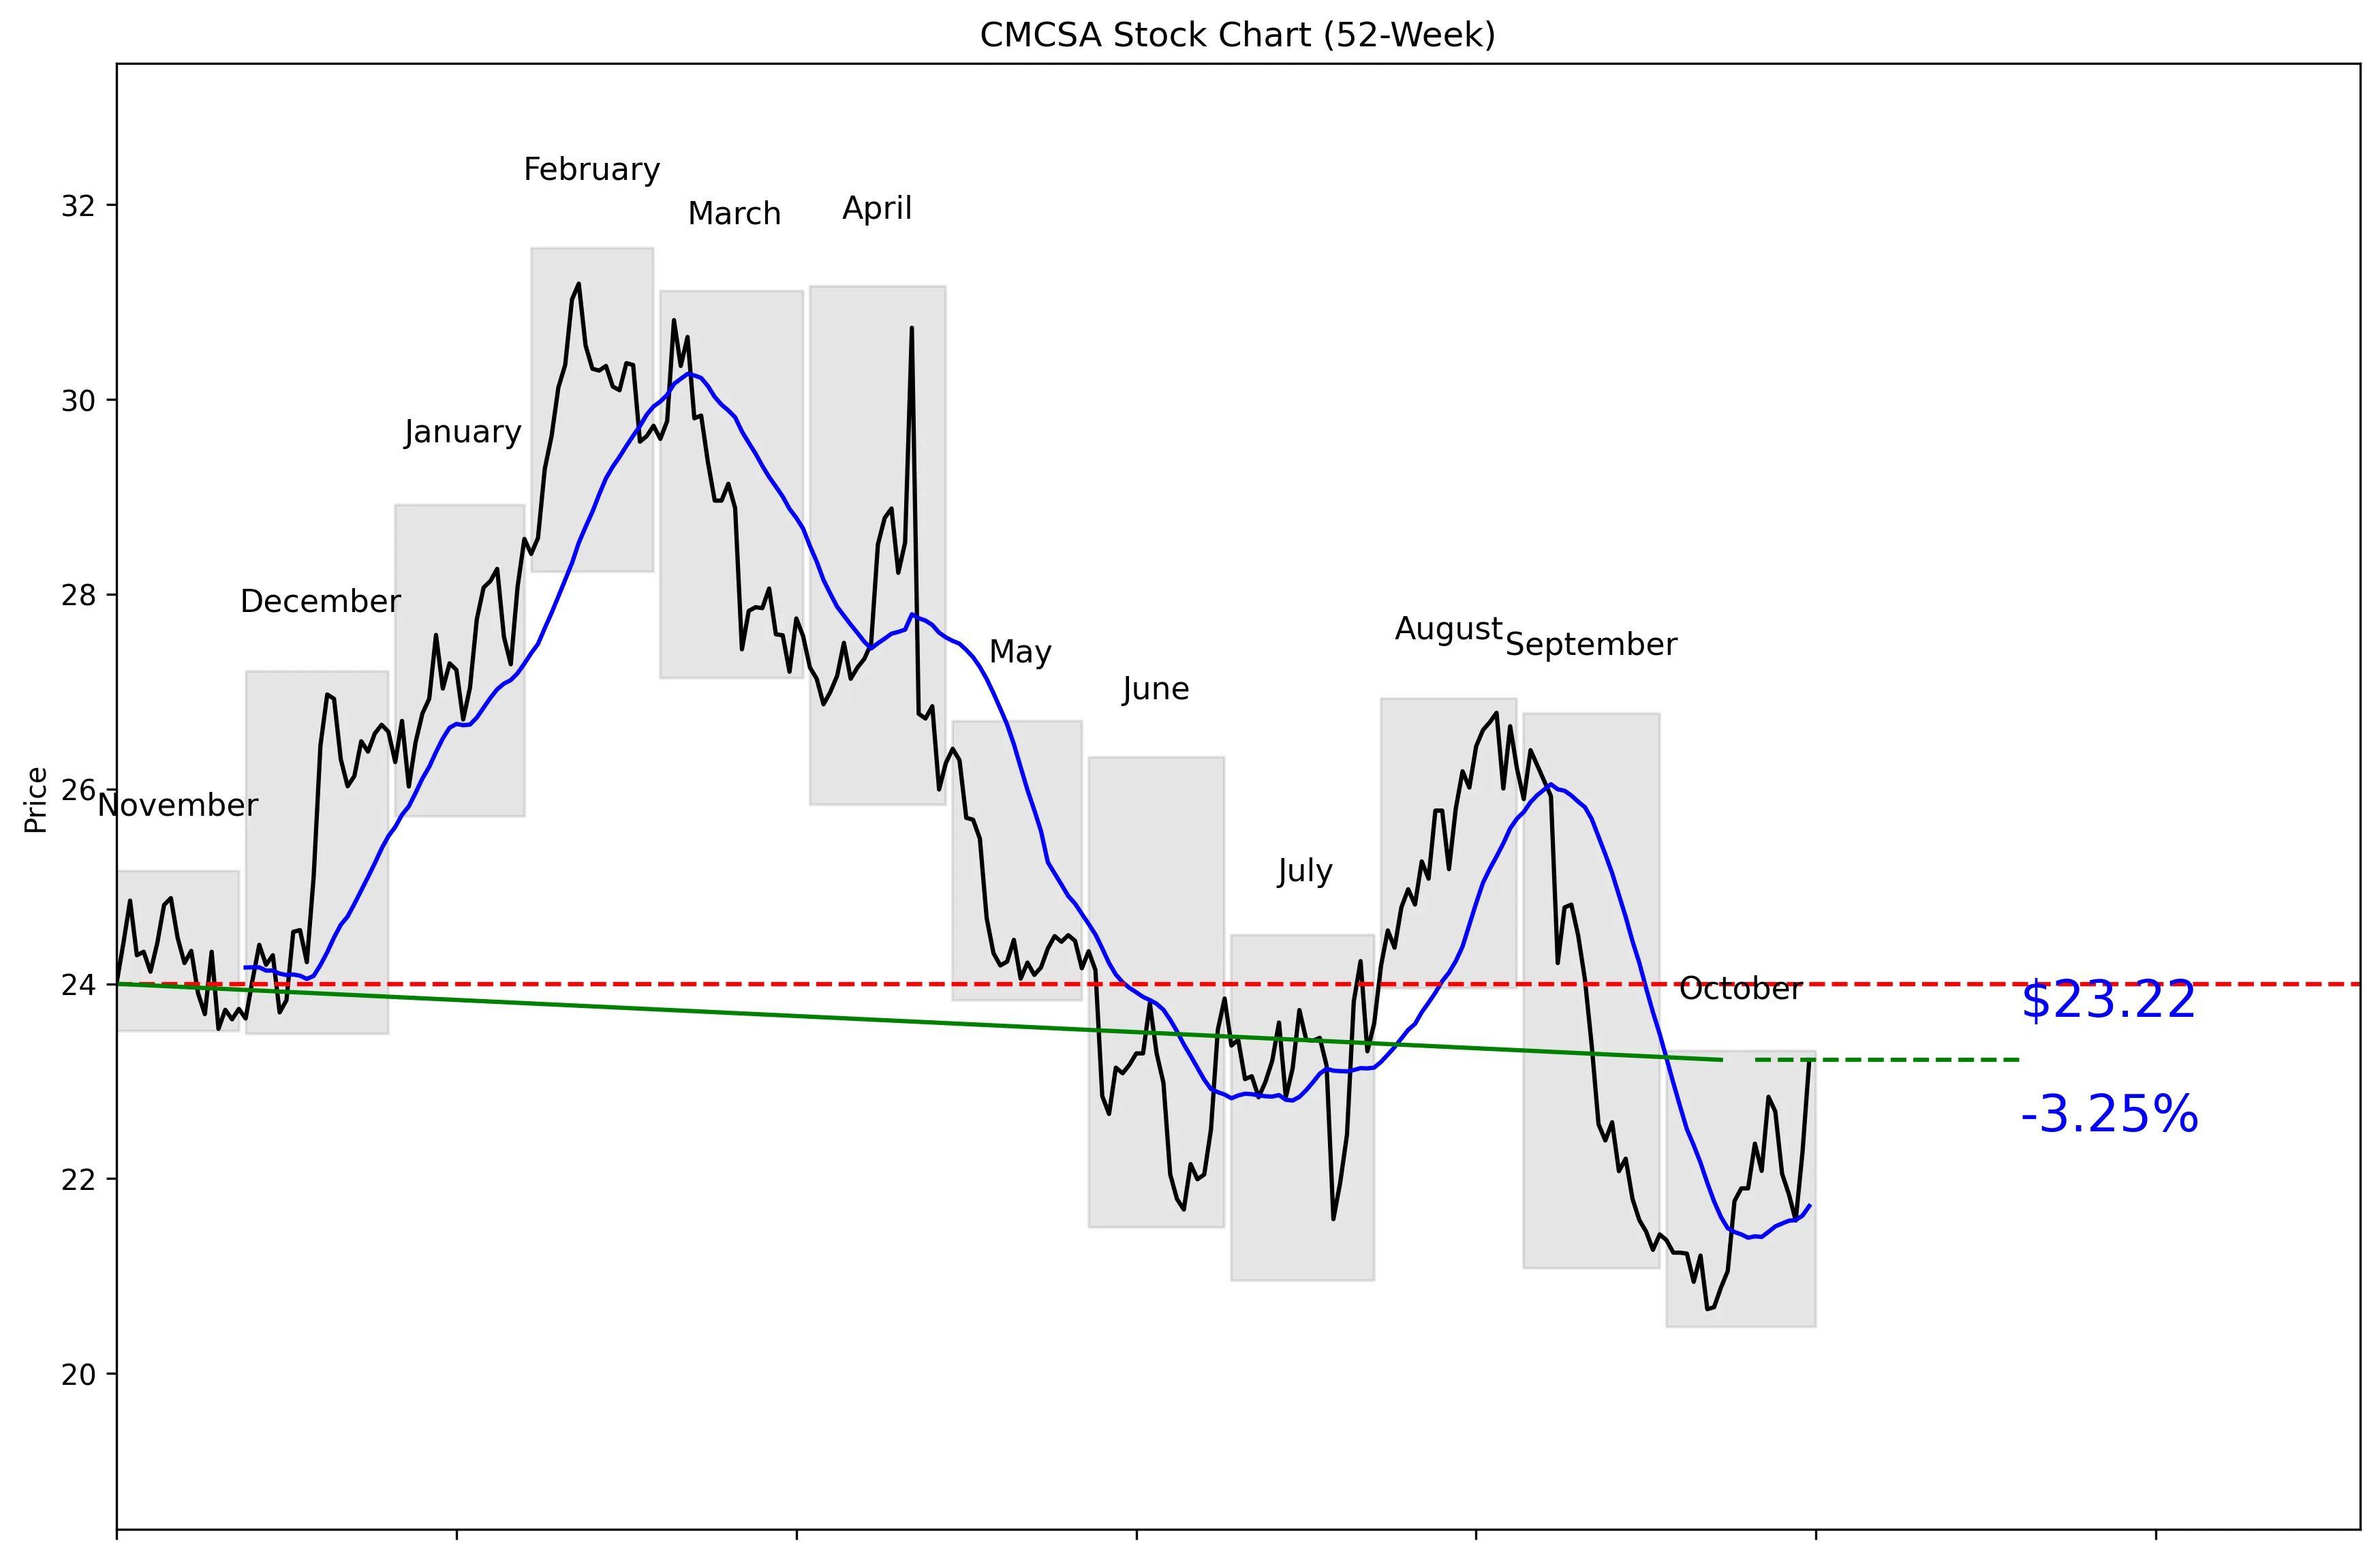
CMCSA 52-Week Stock Chart
Technical Analysis
CMCSA trades at $23.22, 25% of the way from its $20.48 52-week low to its $31.56 52-week high. The stock is 26.41% below that high but 13.38% above the low. Price sits 6.91% above the 20-day moving average of $21.72. Momentum is positive at 2.34% over five trading days and 9.32% over 20 trading days. Near-term support is $20.66, while $23.22 is the 30-day resistance level the stock is testing now.


Recent News and Developments

Freedom Broker cuts Comcast target to $25

Freedom Broker analyst Lyaysyan Sedova cut the CMCSA price target from $29 to $25 on October 26 while maintaining a Hold rating. That is a 13.8% target reduction, not a ratings downgrade. Source: Benzinga

Universal Ads expands TV buying integrations

Comcast’s Universal Ads launched Campaign Management partnerships that embed TV advertising into platforms used for search, social and other digital channels. The launch group includes 12 partners, while advertisers can also buy through Universal Ads Manager, its API and MCP integrations. Source: NEWSnet Norfolk

Xfinity reaches nearly 7,000 Virginia locations

Comcast completed a network expansion connecting nearly 7,000 homes and businesses in Forest, Virginia. The new footprint offers multi-gigabit symmetrical internet and gives Comcast another market for bundling broadband, mobile, entertainment and smart-home services. Source: Nasdaq


Market Sentiment and Analyst Recommendations

Bull Case
CMCSA is cheap at 7.35 times earnings while generating $123.01 billion in revenue. The $27.98 average analyst target sits above the current $23.22 price, although the target range is unusually wide at $17.00 to $42.00. Momentum has improved, with the stock gaining 7.7% across the October 29 and October 30 sessions. Universal Ads is expanding access to TV advertising through 12 launch partners, Universal Ads Manager, its API and MCP integrations. Comcast also completed an expansion reaching nearly 7,000 Virginia locations and started construction covering more than 4,000 New Hampshire locations. The bull case is straightforward: buy a low-multiple company while network expansion and advertising integrations create potential upside from a depressed share price.
Bear Case
Revenue growth is negative 6.1%, which explains why the market assigns CMCSA a P/E of just 7.35. Total debt stands at $87.37 billion against only $7.60 billion in cash. That debt load reduces flexibility if revenue continues shrinking. The stock remains 26.41% below its $31.56 52-week high despite its recent rebound. Freedom Broker cut its target from $29 to $25 on October 26, a 13.8% reduction, while keeping a Hold rating. The broad analyst target range of $17.00 to $42.00 shows how uncertain the outlook is, and the consensus recommendation from 22 analysts is Hold rather than Buy.
What to Watch
The first test is whether CMCSA can break above its current 30-day resistance of $23.22 rather than surrendering the recent 9.32% 20-day gain. A drop below the $21.72 moving average would weaken the near-term setup, while $20.66 remains the stated 30-day support. Investors should watch whether revenue growth improves from negative 6.1% and whether cash rises from $7.60 billion relative to $87.37 billion in debt. Universal Ads needs to show that its 12 launch partnerships and additional buying integrations can translate into measurable business results. Comcast’s nearly 7,000-location Virginia expansion provides another market for broadband and bundled services, while initial service from the more than 4,000-location Barrington expansion is expected within weeks. Full completion in Barrington is scheduled for the end of 2027, so the next quarter is about early execution rather than final results.
Analyst Consensus
HOLD

Based on 22 analyst opinions
Low Target
$17.00
Mean Target
$27.98
High Target
$42.00


Earnings and Financial Data

Sector
Communication Services
Industry
Telecom Services
Employees
179,000
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$3.16
Dividend Yield
568.0%
Payout Ratio
41.8%

Frequently Asked Questions

Is CMCSA a good stock to buy?
CMCSA trades at a low P/E of 7.35, but revenue growth is negative 6.1% and the recommendation from 22 analysts is Hold. The takeaway is that CMCSA looks inexpensive, but the provided data does not support a clear Buy rating.
What is CMCSA’s price target?
The average analyst target is $27.98, with estimates ranging from $17.00 to $42.00. The takeaway is that the average target is above the $23.22 share price, but analyst expectations vary widely.
Is CMCSA stock undervalued?
CMCSA trades at 7.35 times earnings and sits 26.41% below its $31.56 52-week high. The takeaway is that the valuation is low, but negative 6.1% revenue growth may justify part of the discount.
What are CMCSA’s support and resistance levels?
Near-term support is $20.66, and near-term resistance is $23.22 based on the 30-day low and high. The takeaway is that CMCSA is currently testing resistance.
Does CMCSA pay a dividend?
The provided key and technical data do not include dividend information. The takeaway is that no conclusion about CMCSA’s dividend can be made from this dataset.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 02, 2026.