ALTSTATION.IO

Palo Alto Networks, Inc. (PANW) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$349.63
Change
-0.16%
Market Cap
$286.15B
Avg Volume
5.9M

Company Overview

Palo Alto Networks is a Santa Clara, California-based infrastructure software company founded in 2005 that builds enterprise cybersecurity systems. The business sells cloud security through Prisma Access, inline network protection via VM-Series and CN-Series virtual firewalls, and automated operations through its Cortex platform. They package these tools alongside Unit 42 threat intelligence and recurring subscription services for DNS security, IoT protection, and URL filtering. Their direct sales and channel partner network delivers these solutions to enterprises, service providers, and government entities across 8 major sectors, including financial services, healthcare, manufacturing, and telecommunications.

Palo Alto Networks holds a clear market leader position in infrastructure cybersecurity across 6 global operating regions spanning the Americas, EMEA, and Asia-Pacific. Their primary competitive edge comes from architectural breadth, integrating Code to Cloud protection, Strata Cloud Manager, and Cortex Xpanse attack surface management into a single stack instead of selling fragmented point products. Combining proprietary threat intelligence from Unit 42 with automated response tools like Cortex XSOAR and Cortex XDR gives them an operational advantage over narrower vendors. The main friction point is defending that perimeter against specialized niche security providers while managing complex deployments across hybrid-cloud environments.

The company is executing a clear strategic pivot toward enterprise AI protection and automated security operations. Offerings like Prisma AIRS directly target securing enterprise AI ecosystems, while Cortex XSIAM focuses on replacing legacy, labor-heavy security operations centers with automated AI platforms. They are systematically tying together cloud-native application protection, firewall migrations, and threat advisory services into an integrated multi-cloud defense. That platform-first focus makes them the primary consolidation candidate for large organizations looking to reduce vendor sprawl.

Key Financials
Market Cap
$286.15B
Revenue
$11.48B
EBITDA
$1.56B
Gross Margin
70.4%
Profit Margin
2.7%
Revenue Growth
34.5%
Total Cash
$3.07B
Total Debt
$2.57B
Free Cash Flow
$4.24B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
874.08
Forward P/E
71.66
Beta
0.97
52-Week High
$432.33
52-Week Low
$139.57
EPS
$0.40
50-Day Avg
$372.01
200-Day Avg
$271.45
Price/Book
10.36
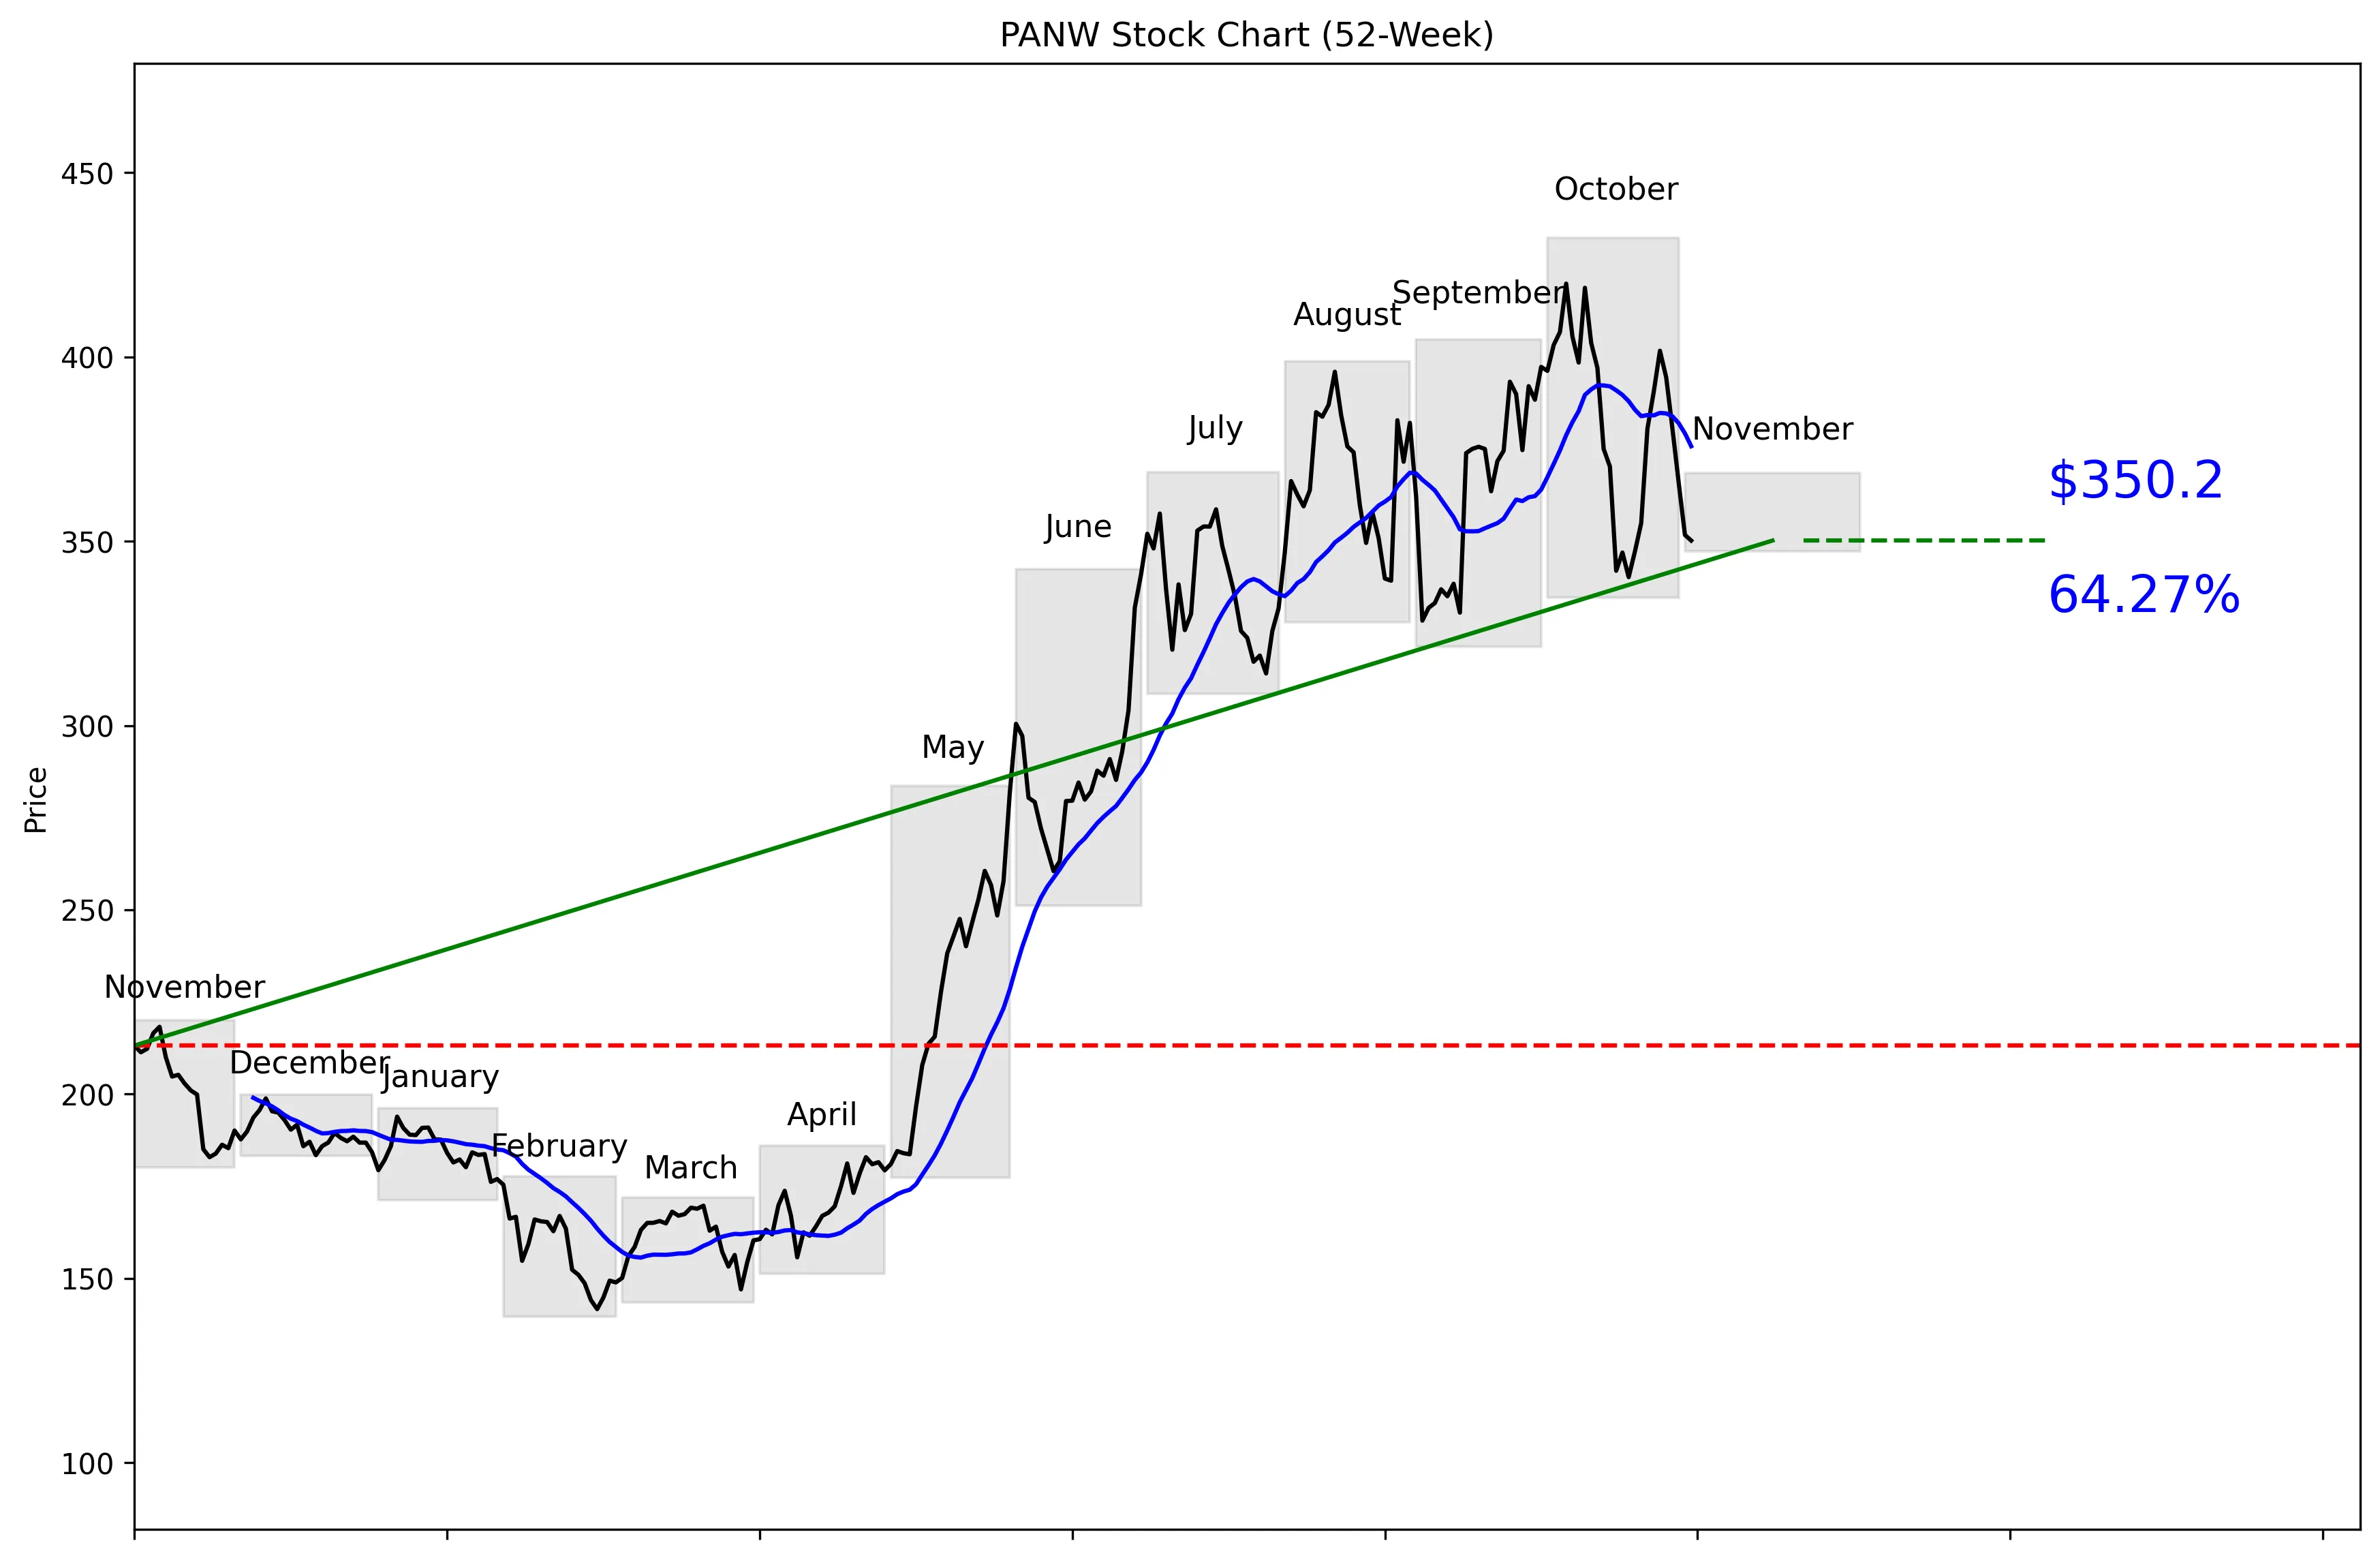
PANW 52-Week Stock Chart
Technical Analysis
PANW trades at $349.63, placing it 72% of the way from its 52-week low of $139.57 to its 52-week high of $432.33. The stock is 19.00% below that high but still 150.91% above the low. Momentum has turned sharply negative, with declines of 12.82% over the last five trading days and 16.60% over the last 20 trading days. Price sits 6.81% below the 20-day moving average of $375.80, confirming that sellers control the near-term trend. The key levels are $340.28 support and $419.91 resistance.


Recent News and Developments

PANW sets November 18 earnings date

Palo Alto Networks will report fiscal first-quarter 2027 results after the market closes on November 18. The quarter ended October 31, and management will hold a webcast at 4:30 p.m. Eastern. Source: Palo Alto Networks

Palo Alto rejects $450 mini-tender offer

Palo Alto Networks told shareholders to reject Tutanota LLC’s unsolicited offer to buy up to 250,000 shares for $450 each. The offer covers roughly 0.03% of outstanding shares and requires PANW to close above $450 before expiration, potentially leaving participating investors with a below-market price. Source: PR Newswire

PANW slides with cybersecurity sector

PANW fell 2% to $358.01 in early trading on November 2 as cybersecurity stocks sold off despite bullish news for CrowdStrike. This was sector pressure, not a Palo Alto operating setback; the same report noted that Palo Alto’s September 1 revenue increased 34.5% to $3.41 billion. Source: 24/7 Wall St.


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 34.5% is the strongest reason to own PANW. Revenue stands at $11.48 billion, giving the company real scale alongside that growth. The balance sheet holds $3.07 billion in cash against $2.57 billion in debt, so cash exceeds debt. Wall Street remains bullish: 50 analysts rate the stock a buy, with a consensus target of $398.52. That target sits above the current $349.63 price, while the highest estimate reaches $525.00. Fiscal first-quarter 2027 earnings on November 18 could reset sentiment if the company shows that its growth rate remains intact.
Bear Case
A P/E ratio of 874.08 leaves almost no room for weak execution. Investors are paying an extreme multiple even after the stock fell 19.00% from its 52-week high. Near-term momentum is poor, with the shares down 12.82% over five trading days and 16.60% over 20 trading days. Sector weakness has already hit the stock: PANW fell 5% near $375 on October 29 after Fortinet reduced its service-revenue forecast. It then fell another 2% to $358.01 in early trading on November 2 during a broader cybersecurity selloff. The analyst target range of $190.00 to $525.00 shows how sharply opinions differ, and the low end is well below the current $349.63 price.
What to Watch
The next major catalyst is fiscal first-quarter 2027 earnings after the market closes on November 18, followed by management’s webcast at 4:30 p.m. Eastern. The first test is whether revenue growth can remain close to the reported 34.5% rate. Price action around the $340.28 near-term support level matters because the stock is already below its $375.80 20-day moving average. A recovery above $375.80 would improve the short-term setup, while a move toward $419.91 would test near-term resistance. Investors should also watch whether cybersecurity-sector selling continues after the October 29 and November 2 declines. The thesis strengthens if growth holds and price recovers above the moving average; it weakens if earnings disappoint and $340.28 support fails.
Analyst Consensus
BUY

Based on 50 analyst opinions
Low Target
$190.00
Mean Target
$398.52
High Target
$525.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Infrastructure
Employees
21,921
Earnings & Dividends
Next Earnings
Nov 18, 2026
EPS (Trailing)
$0.40
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is PANW a good stock to buy?
The current recommendation is buy based on 50 analysts, and revenue growth is 34.5%. The clear takeaway is that analysts favor PANW, but its 874.08 P/E makes valuation a major risk.
What is PANW’s price target?
The analyst target is $398.52, with estimates ranging from $190.00 to $525.00. The takeaway is that the consensus target exceeds the current $349.63 price, but the range is unusually wide.
Is PANW overvalued?
PANW trades at a P/E ratio of 874.08 with revenue of $11.48 billion and revenue growth of 34.5%. The takeaway is that the valuation is extremely demanding despite strong growth.
What are PANW’s support and resistance levels?
Near-term support is the 30-day low of $340.28, while near-term resistance is the 30-day high of $419.91. The takeaway is that these are the key levels to watch around the current $349.63 price.
How far is PANW from its 52-week high?
PANW is 19.00% below its $432.33 52-week high and 150.91% above its $139.57 52-week low. The takeaway is that the stock remains high within its annual range despite its recent pullback.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.