ALTSTATION.IO

Palantir Technologies Inc. (PLTR) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$195.21
Change
+0.55%
Market Cap
$469.10B
Avg Volume
32.6M

Company Overview

Incorporated in 2003 and headquartered in Aventura, Florida, Palantir Technologies operates in the Technology sector under Software – Infrastructure. The company builds four primary platforms: Palantir Gotham for defense and counterterrorism, Palantir Foundry as a central enterprise operating system, Palantir Apollo for automated software delivery across any environment, and the Artificial Intelligence Platform (AIP) for integrating large language models. Its customer base spans intelligence and defense agencies across the United States, the United Kingdom, and international allies, alongside commercial corporate clients. In plain terms, Palantir sells the digital backbone that lets organizations aggregate messy sensor feeds and scattered operational data into one actionable screen.

Palantir is a clear market leader in government defense intelligence that is actively challenging traditional commercial infrastructure providers. Its primary competitive edge is deep operational stickiness, connecting data from central operations centers out to the tactical edge in near real-time. The company also holds a distinct moat in sovereign environments, enabling secure data and model execution where off-the-shelf software cannot operate. The main friction point in this market is implementation complexity, as deploying Palantir’s end-to-end data operating systems requires far deeper organizational integration than standard point solutions.

Right now, Palantir is aggressively expanding its footprint by anchoring its growth to the Artificial Intelligence Platform. The company has lined up key strategic collaborations to accelerate distribution, partnering with PwC for enterprise business transformation, NVIDIA to run open AI models in sovereign environments, and Ondas Inc. to power aerial, land, and stratospheric reconnaissance missions. By turning raw data into usable tools for humans and autonomous LLM agents, Palantir is pivoting from a specialized analysis tool into the core operating layer for enterprise workflows. These high-value alliances position the business to capture both critical defense spending and private sector AI infrastructure budgets.

Key Financials
Market Cap
$469.10B
Revenue
$6.16B
EBITDA
$2.66B
Gross Margin
84.8%
Profit Margin
49.0%
Revenue Growth
92.8%
Total Cash
$9.41B
Total Debt
$211.40M
Free Cash Flow
$2.16B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
168.28
Forward P/E
83.05
Beta
1.60
52-Week High
$212.94
52-Week Low
$106.37
EPS
$1.16
50-Day Avg
$183.01
200-Day Avg
$152.73
Price/Book
47.99
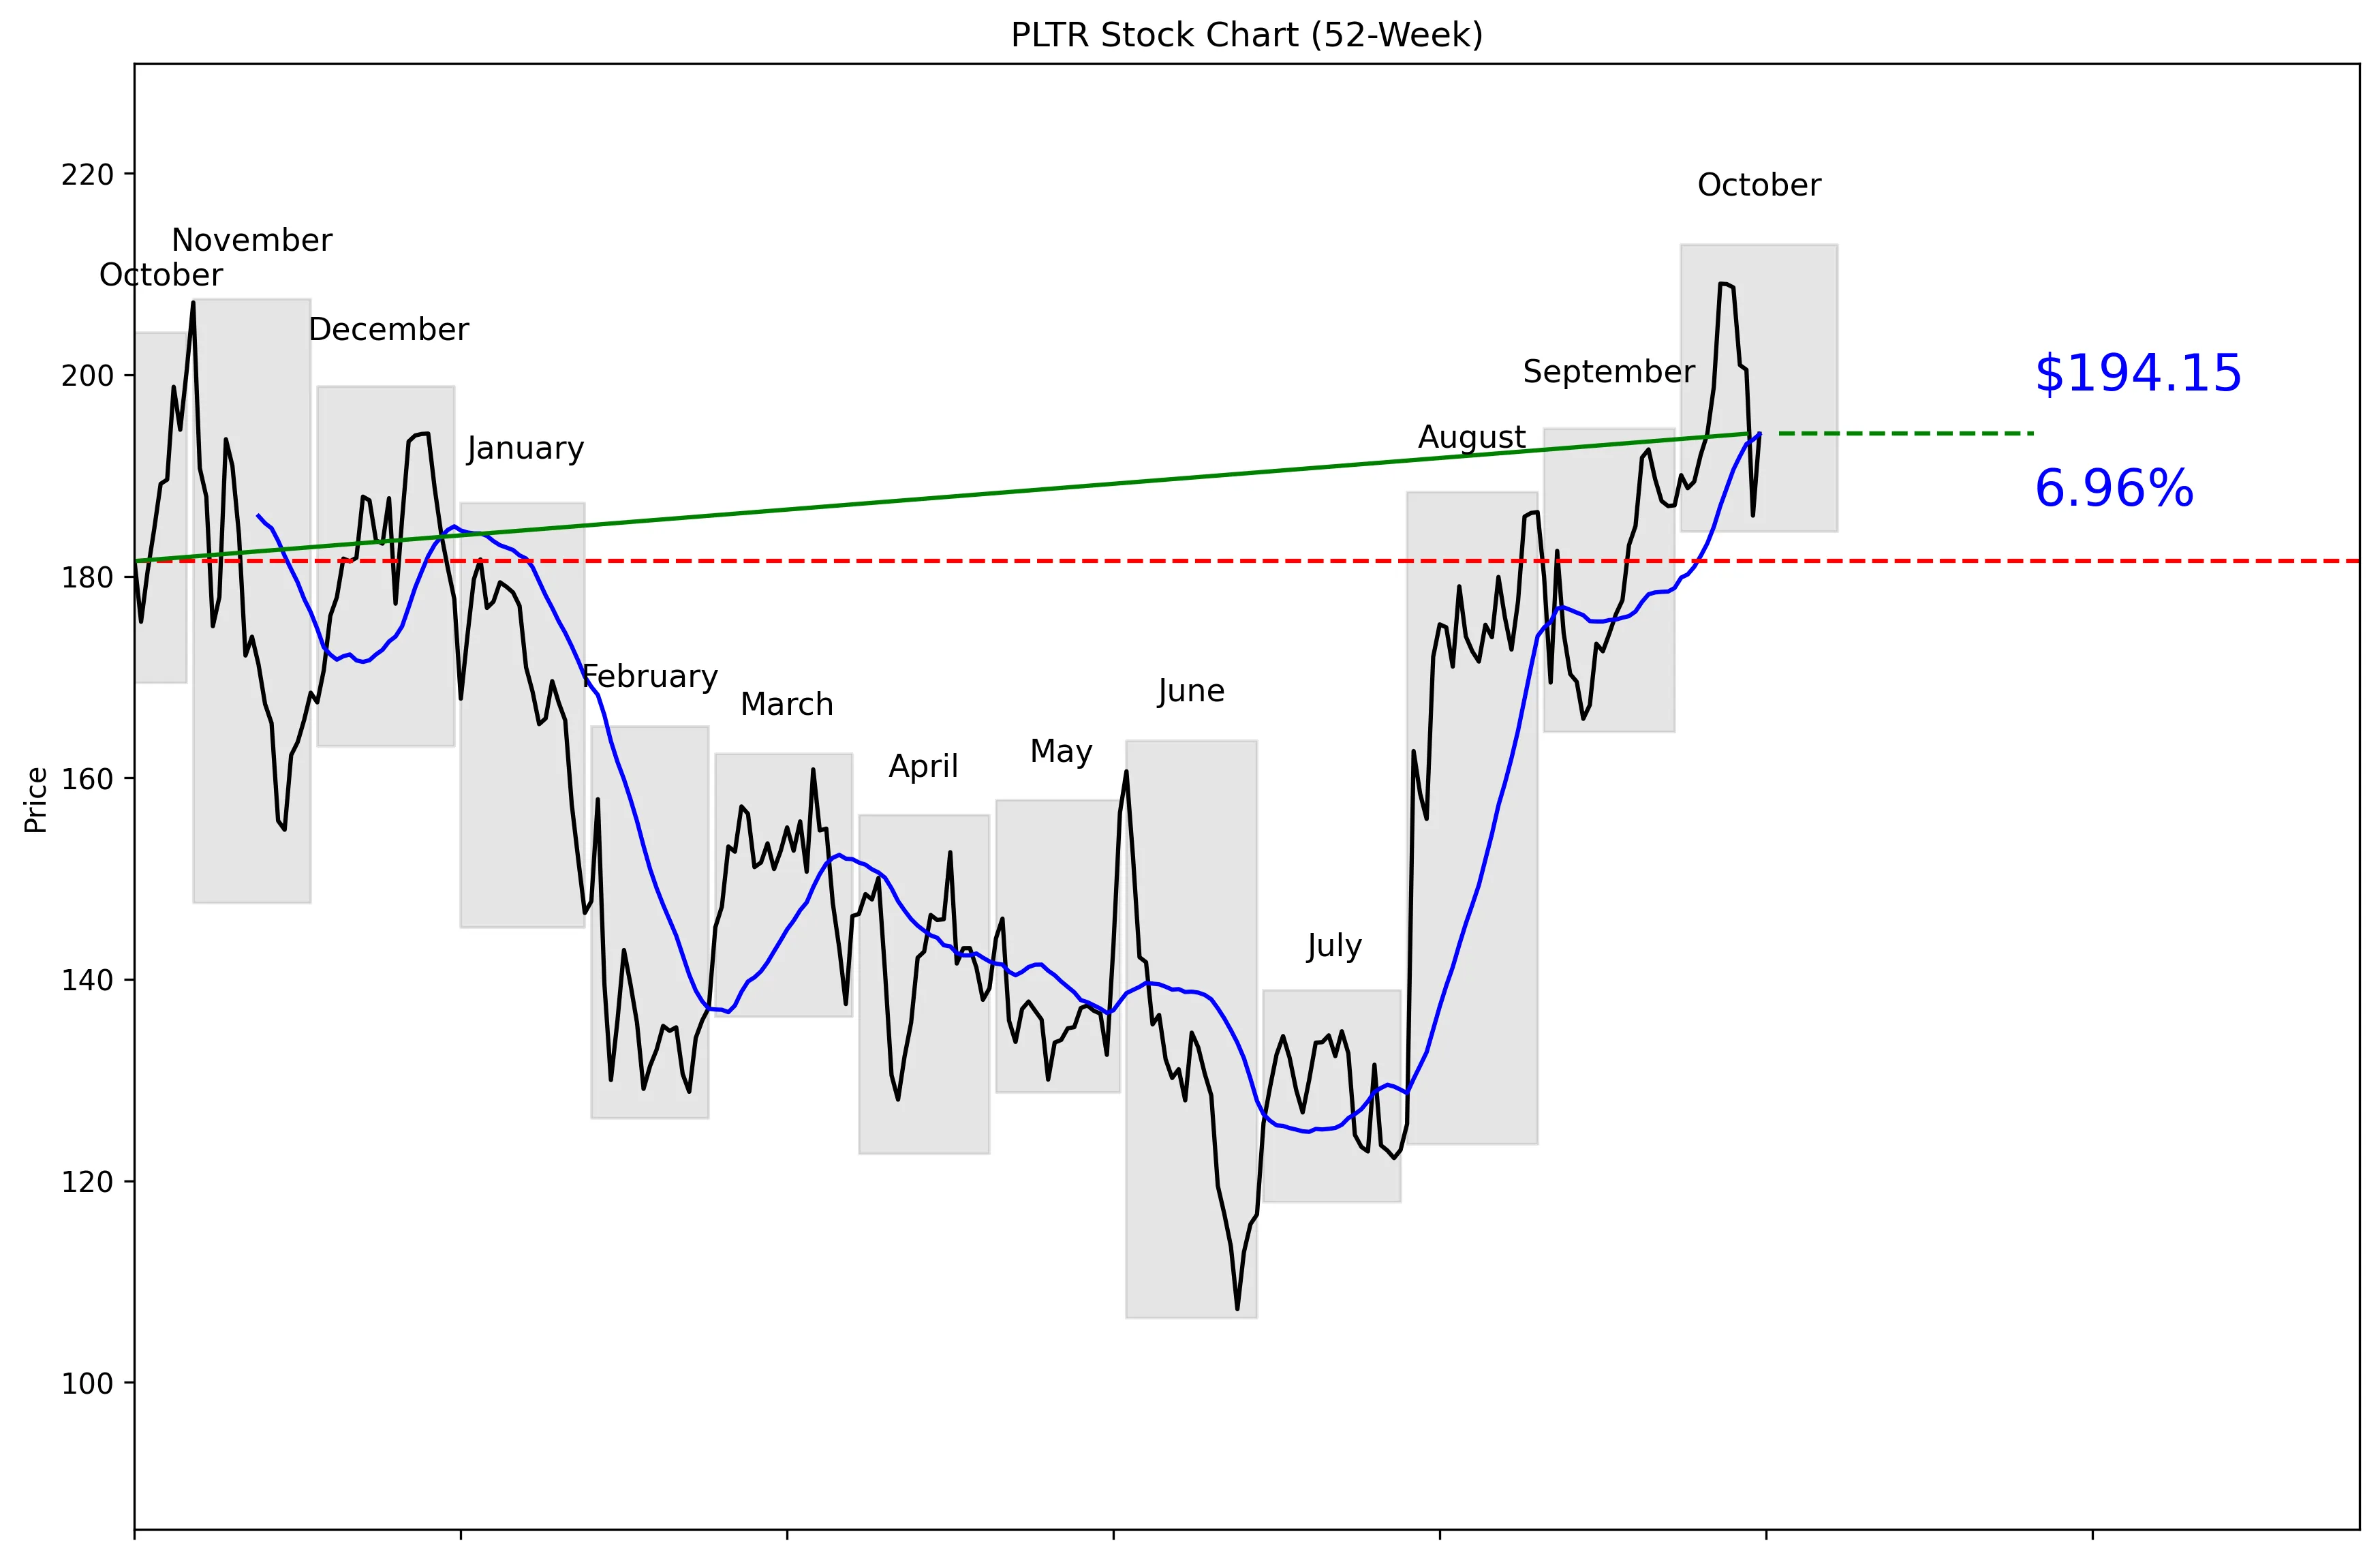
PLTR 52-Week Stock Chart
Technical Analysis
PLTR trades at $195.21, 82% of the way from its 52-week low of $106.37 to its 52-week high of $212.94. The stock is 8.82% below that high and 82.52% above the low, so the broader trend remains strong. Price is 0.02% above its 20-day moving average of $194.10. Five-day momentum is negative at 7.11%, while 20-day momentum remains positive at 6.04%. Near-term support is $165.86, and resistance is $209.05.


Recent News and Developments

Palantir and Knox target faster federal software deployment

Palantir and Knox Systems partnered to help software companies deploy into FedRAMP and IL5 government environments. PLTR closed October 19 at $194.15, up 4.36%, but the companies disclosed no financial terms or revenue target. Source: TokenPost

Mizuho lifts Palantir target to $245

Mizuho raised its PLTR price target from $215 to $245 on October 15 while keeping an Outperform rating. The 14% target increase followed healthy software-channel checks and continued strength in AI adoption. Source: TipRanks

Palantir settles dispute with London policing office

Palantir and London’s Mayor’s Office for Policing and Crime settled their legal dispute on October 14 and withdrew their allegations against each other. The case concerned MOPAC’s decision to block a proposed two-year Palantir contract for AI-assisted criminal-intelligence analysis. Source: ITV News


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 92.8% is the main reason to own PLTR. Revenue stands at $6.16 billion, showing that Palantir is producing real scale alongside that growth. The balance sheet is strong, with $9.41 billion in cash against just $211.40 million in debt. Mizuho raised its price target from $215 to $245 on October 15, citing healthy software-channel checks and continued strength in AI adoption. The Knox Systems partnership could make it faster for software companies to enter FedRAMP and IL5 government environments, reinforcing Palantir’s federal-market position. The analyst consensus is buy across 26 analysts, with an average target of $206.43. PLTR is expensive, but 92.8% revenue growth, a cash-heavy balance sheet, and AI demand give investors a credible reason to pay a premium.
Bear Case
A P/E of 168.28 leaves almost no room for weak execution. PLTR already trades at $195.21, only 8.82% below its 52-week high of $212.94. The average analyst target of $206.43 offers limited upside from the current price. Analyst targets range from $80 to $265, which shows how sharply opinions differ on what the business is worth. Five-day momentum is down 7.11%, and a break below the $194.10 moving average could weaken the near-term setup. The Knox partnership included no financial terms or revenue target, so investors should not assume it will materially lift results. The London policing dispute also shows that government opportunities can face legal and procurement friction even when Palantir’s technology is under consideration.
What to Watch
The first number to track next quarter is revenue growth relative to the current 92.8% rate. Any sharp slowdown would make the 168.28 P/E harder to defend. Watch whether PLTR can clear near-term resistance at $209.05 and then challenge the 52-week high of $212.94. On the downside, $194.10 is the 20-day moving average, while $165.86 is the stated near-term support level. Investors should also watch for financial terms, customer wins, or revenue targets tied to the Palantir-Knox partnership after its October 19 disclosure. Mizuho’s October 15 target increase from $215 to $245 set a high bar based on AI adoption and software-channel strength, so future checks need to confirm that demand. The analyst average target of $206.43 and broad $80-to-$265 range should narrow only if Palantir’s results provide clearer evidence on sustainable growth and valuation.
Analyst Consensus
BUY

Based on 26 analyst opinions
Low Target
$80.00
Mean Target
$206.43
High Target
$265.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Infrastructure
Employees
4,401
Earnings & Dividends
Next Earnings
Nov 02, 2026
EPS (Trailing)
$1.16
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is PLTR a good stock to buy?
The analyst recommendation is buy based on 26 analysts, and revenue growth is 92.8%. The clear takeaway is that PLTR has strong growth support, but its 168.28 P/E makes the entry price important.
What is PLTR’s price target?
The average analyst target is $206.43, with estimates ranging from $80 to $265. The clear takeaway is that the average target sits above the current $195.21 price, but analyst expectations vary widely.
Is PLTR overvalued?
PLTR trades at a P/E of 168.28 and has a market capitalization of $469.10 billion on $6.16 billion in revenue. The clear takeaway is that the valuation is demanding despite 92.8% revenue growth.
What are PLTR’s support and resistance levels?
Near-term support is $165.86, the 30-day low, while near-term resistance is $209.05, the 30-day high. The clear takeaway is that these are the key technical levels to monitor.
How close is PLTR to its 52-week high?
PLTR trades at $195.21, which is 8.82% below its 52-week high of $212.94. The clear takeaway is that the stock remains near the upper end of its $106.37-to-$212.94 annual range.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.