ALTSTATION.IO

Vertex Pharmaceuticals Incorporated (VRTX) Stock Analysis

By Nova Skye | AltStation.io | Updated October 27, 2026

Price
$517.02
Change
-0.09%
Market Cap
$130.96B
Avg Volume
1.2M

Company Overview

Founded in 1989 and headquartered in Boston, Massachusetts, Vertex Pharmaceuticals operates as a biotechnology company in the healthcare sector. The company develops and sells specialty prescription medicines for serious diseases, with its primary commercial revenue generated by cystic fibrosis therapies. Its core commercial lineup includes TRIKAFTA (marketed as KAFTRIO in Europe) for patients aged 2 and older, alongside ALYFTREK, SYMDEKO, ORKAMBI, and KALYDECO for patient groups down to 1 month of age. Vertex distributes these treatments globally to specialty pharmacies, wholesale distributors, retail pharmacies, hospitals, and clinics.

Vertex is the undisputed market leader in cystic fibrosis, holding a virtually unmatched commercial moat across multiple age brackets and genetic mutations. That multi-product lineup delivers reliable cash flow that competitors cannot touch. The primary threat to Vertex is revenue concentration: depending overwhelmingly on cystic fibrosis leaves it vulnerable if the patient pool saturates or alternative treatment modalities emerge. To defend its moat against disruption, the company is already testing VX-522, a CFTR mRNA therapeutic currently in Phase 1/2 clinical trials to address the root cause of cystic fibrosis.

Vertex is executing an aggressive strategic pivot to transform from a single-disease specialist into a multi-franchise biotech powerhouse. It is advancing CASGEVY for sickle cell disease and transfusion-dependent beta thalassemia, while developing JOURNAVX to target the adult acute pain market. In the clinic, the company is running a single Phase 2 trial for inaxaplin in APOL1-mediated kidney disease, alongside programs like VX-264 for Type 1 diabetes and a collaboration with AbCellera Biologics on multispecific T-cell engagers. If these non-cystic-fibrosis assets deliver, Vertex successfully diversifies its revenue engine into major new therapeutic categories.

Key Financials
Market Cap
$130.96B
Revenue
$12.59B
EBITDA
$5.10B
Gross Margin
55.0%
Profit Margin
35.0%
Revenue Growth
12.5%
Total Cash
$7.85B
Total Debt
$1.98B
Free Cash Flow
$2.63B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
30.11
Forward P/E
25.32
Beta
0.28
52-Week High
$560.25
52-Week Low
$403.16
EPS
$17.17
50-Day Avg
$522.94
200-Day Avg
$477.61
Price/Book
6.47
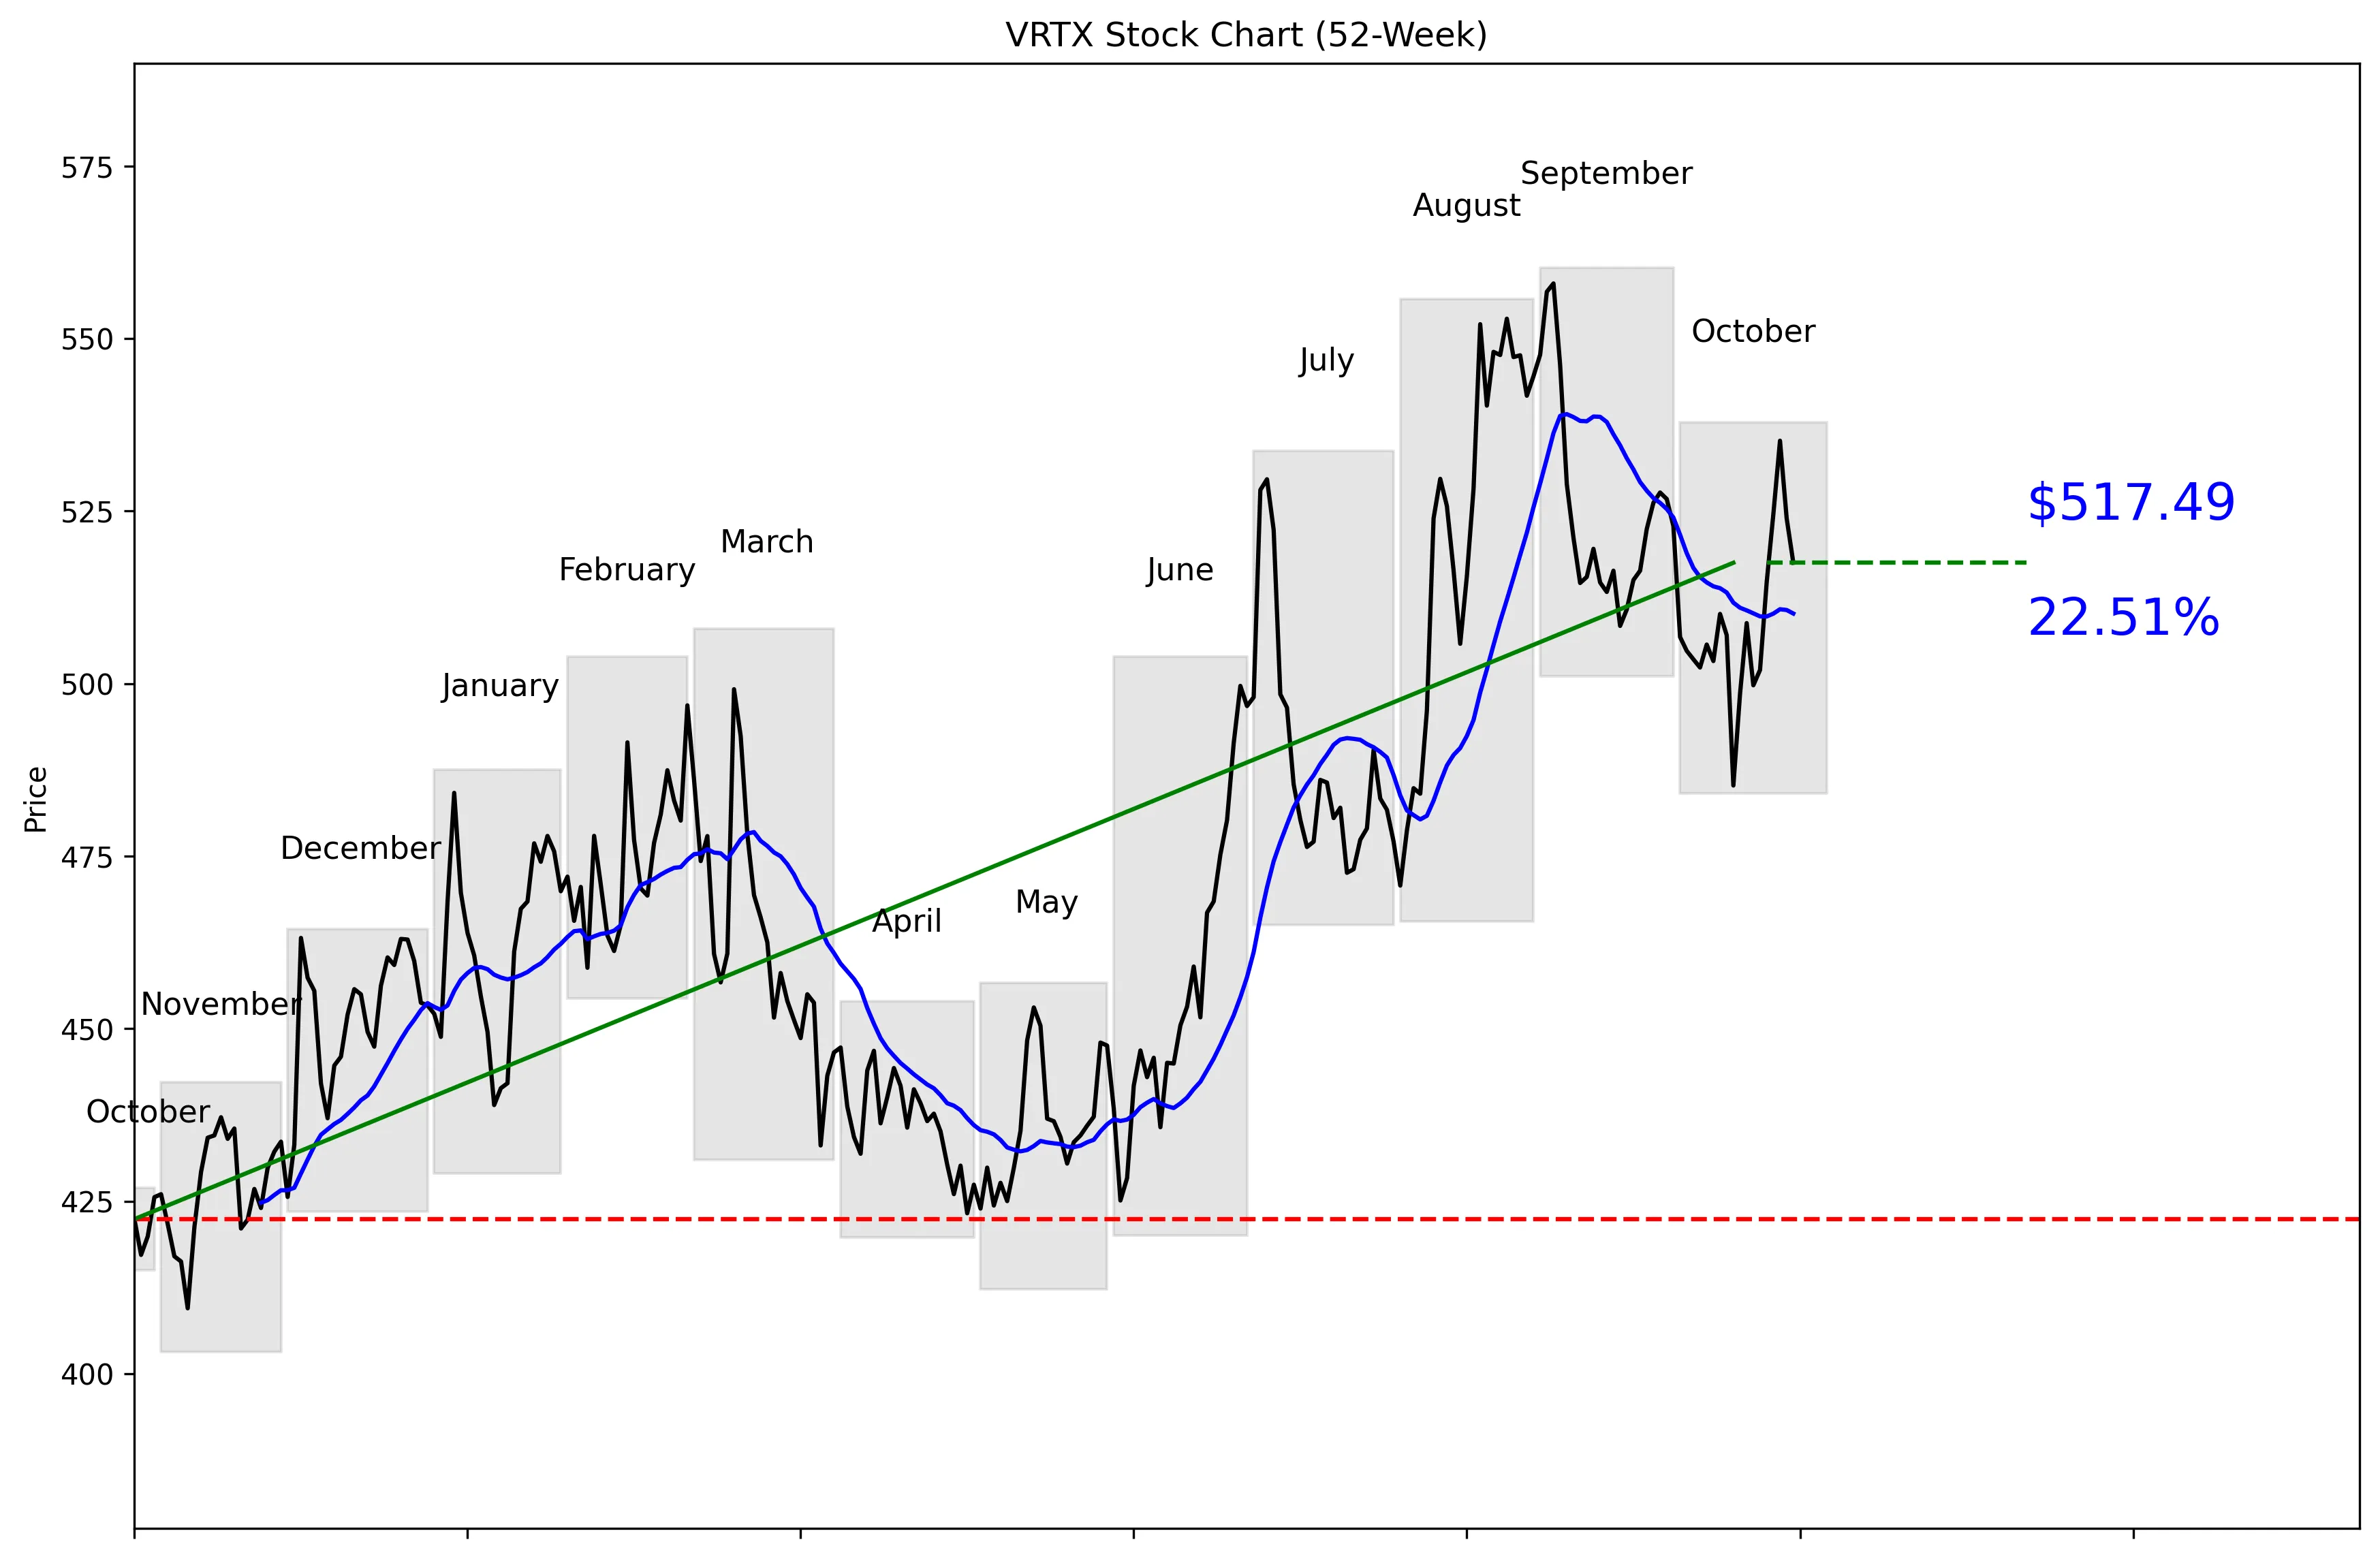
VRTX 52-Week Stock Chart
Technical Analysis
VRTX trades at $517.02, placing it 73% of the way from its 52-week low of $403.16 to its high of $560.25. The stock is 7.63% below that high and 28.36% above the low. Price sits 1.44% above the 20-day moving average of $510.14, but 20-day momentum remains negative at 1.93%. Five-day momentum is positive at 3.10%, showing a recent rebound. Near-term support is $485.22, while resistance sits at $535.17.


Recent News and Developments

Povetacicept clears Phase 3 test as FDA decision approaches

Vertex’s RAINIER trial showed a 52.0% reduction from baseline in proteinuria at Week 36 and a 49.8% reduction versus placebo. The FDA accepted the accelerated-approval application for IgA nephropathy and set November 30, 2026, as the target decision date. Source: Vertex Pharmaceuticals

Erste trims Vertex earnings estimate

Erste Group Bank cut its fiscal 2026 earnings estimate to $16.65 per share from $16.68, below the $16.75 consensus estimate. The firm projected fiscal 2027 earnings of $18.97 per share. Source: MarketBeat

Vertex adds former Boston Scientific CFO to board

Vertex appointed Daniel Brennan as an independent director on October 20, expanding its board from 10 members to 11. Brennan, Boston Scientific’s CFO from January 2014 through June 2025, also joined Vertex’s Audit and Finance Committee. Source: U.S. Securities and Exchange Commission


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $12.59 billion and growing at 12.5%, giving Vertex a solid fundamental base. The balance sheet is strong, with $7.85 billion in cash against $1.98 billion in debt. Povetacicept delivered a 52.0% reduction in proteinuria from baseline at Week 36 and a 49.8% reduction versus placebo in the RAINIER trial. The FDA has accepted the accelerated-approval application for IgA nephropathy, creating a clear catalyst on November 30, 2026. Analysts rate VRTX a buy, with 28 analysts setting an average target of $571.46 versus the current $517.02 price. The bull case is straightforward: double-digit revenue growth, a cash-heavy balance sheet and a near-term regulatory catalyst justify paying a premium.
Bear Case
VRTX is not cheap at 30.11 times earnings. The stock already sits 73% of the way through its 52-week range, so part of the optimism is reflected in the price. Near-term resistance at $535.17 could limit the rebound unless buyers push the stock toward its $560.25 high. The analyst target range stretches from $350.00 to $667.00, showing major disagreement about valuation and future results. Erste cut its fiscal 2026 earnings estimate from $16.68 to $16.65 per share, below the $16.75 consensus estimate. The FDA has accepted the povetacicept application but has not approved it, making the November decision a real execution and regulatory risk.
What to Watch
The biggest event is the FDA’s November 30, 2026 target decision for povetacicept in IgA nephropathy. Approval would strengthen the bull case, while a rejection or delay would remove the clearest near-term catalyst. Investors should watch whether VRTX clears $535.17 resistance and then challenges its $560.25 52-week high. A drop below the $510.14 moving average would weaken the recent rebound, while a decline toward $485.22 would test near-term support. Revenue growth should remain near or above the reported 12.5% rate to support a 30.11 P/E. Earnings expectations also matter after Erste lowered its fiscal 2026 estimate to $16.65 per share versus the $16.75 consensus.
Analyst Consensus
BUY

Based on 28 analyst opinions
Low Target
$350.00
Mean Target
$571.46
High Target
$667.00


Earnings and Financial Data

Sector
Healthcare
Industry
Biotechnology
Employees
6,400
Earnings & Dividends
Next Earnings
Nov 02, 2026
EPS (Trailing)
$17.17
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is VRTX a good stock to buy?
The recommendation is buy based on 28 analysts, and revenue is growing at 12.5%. The takeaway is that analysts favor VRTX, but its 30.11 P/E demands continued growth.
What is VRTX’s price target?
The average analyst target is $571.46, with estimates ranging from $350.00 to $667.00. The takeaway is that the consensus target sits above the current $517.02 price, but analyst expectations vary widely.
What is VRTX’s 52-week high and low?
VRTX has traded between $403.16 and $560.25 over the past 52 weeks. The takeaway is that the current $517.02 price sits 73% of the way from the low to the high.
Is VRTX overvalued?
VRTX trades at a P/E of 30.11 and has a market capitalization of $130.96 billion. The takeaway is that investors are paying a premium that requires sustained growth.
Does Vertex have a strong balance sheet?
Vertex holds $7.85 billion in cash and $1.98 billion in total debt. The takeaway is that cash substantially exceeds debt.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 27, 2026.