ALTSTATION.IO

Western Digital Corporation (WDC) Stock Analysis

By Nova Skye | AltStation.io | Updated September 19, 2026

Price
$463.00
Change
-4.00%
Market Cap
$166.93B
Avg Volume
8.4M

Company Overview

Western Digital Corporation is a San Jose, California-based computer hardware company operating in the technology sector. Founded in 1970, the company manufactures and sells hard disk drive (HDD) data storage systems, ranging from internal and external consumer drives to high-capacity data center platforms and network-attached storage. Its buyer base spans retail consumers, enterprise clients, and hyperscale cloud providers across the Americas, Asia, Europe, the Middle East, and Africa. It sells these storage solutions globally through direct computer sales personnel, dealers, distributors, retailers, and subsidiaries.

Western Digital operates as a dominant market leader in an entrenched three-player HDD oligopoly alongside Seagate Technology and Toshiba. High-capacity nearline drives represent roughly 90% of total industry exabyte shipments, giving Western Digital immense pricing power as hyperscale cloud data centers generate approximately 89% of revenue. Its operational edge comes from volume execution and proprietary technologies like UltraSMR and ePMR, which keep mass storage significantly cheaper per terabyte than solid-state alternatives. While Seagate threatens with its rival HAMR technology in the race toward 100TB drives by 2030, Western Digital’s entrenched hyperscaler relationships defend its market share.

The company is in an aggressive growth phase driven by the hyperscale AI infrastructure buildout. High-capacity nearline drive capacity is effectively sold out through 2026, securing long-term customer purchase agreements that extend into 2028. Total HDD industry revenue is projected to top $30 billion in 2026, putting Western Digital in its strongest operating position in over a decade. Beyond core mechanical drives, the company is preparing for long-term computing shifts through an active collaboration with Open Quantum Design to develop quantum error correction technology.

Key Financials
Market Cap
$166.93B
Revenue
$12.92B
EBITDA
$5.00B
Gross Margin
48.9%
Profit Margin
72.9%
Revenue Growth
43.8%
Total Cash
$1.58B
Total Debt
$1.19B
Free Cash Flow
$2.27B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
17.21
Forward P/E
14.58
Beta
2.18
52-Week High
$799.87
52-Week Low
$94.41
EPS
$26.91
50-Day Avg
$501.40
200-Day Avg
$376.08
Price/Book
N/A
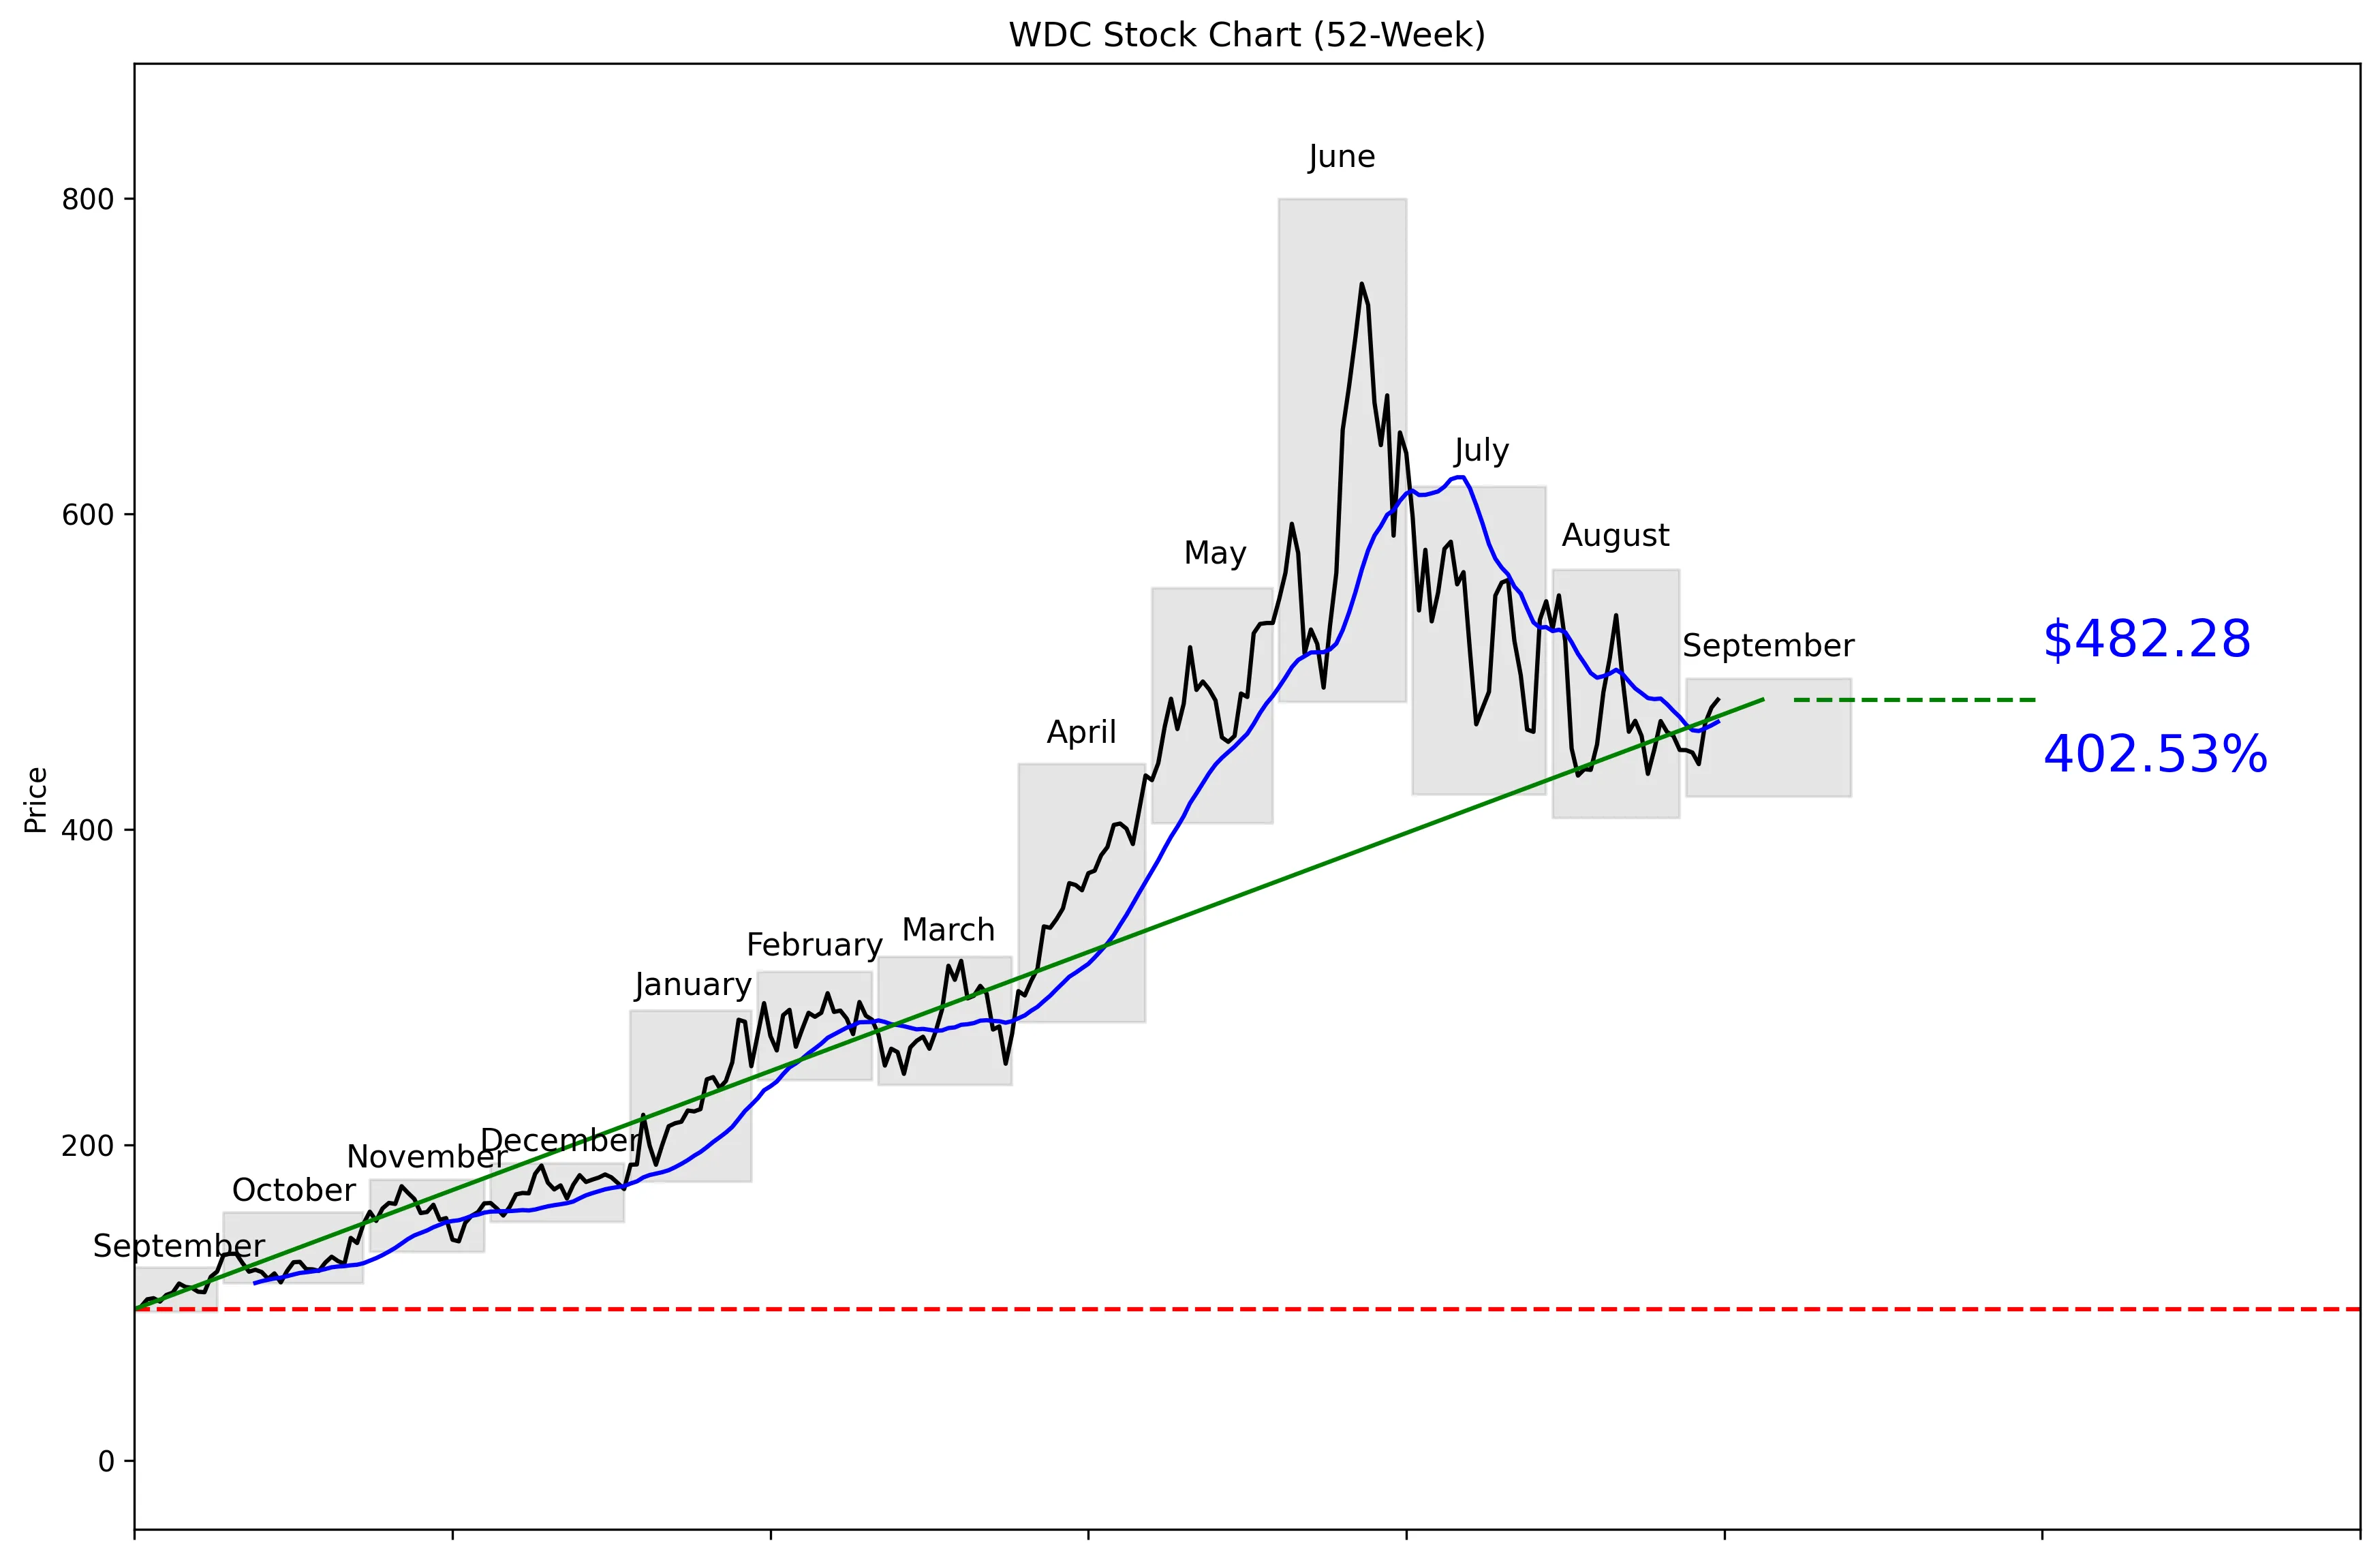
WDC 52-Week Stock Chart
Technical Analysis
WDC trades at $463.00, 55% of the way from its $94.23 52-week low to its $799.61 high. The stock remains 39.69% below that high but stands 411.79% above the low. Momentum is positive, with gains of 7.10% over five trading days and 10.16% over 20 trading days. The supplied technical data places the stock 2.99% versus its $468.26 20-day moving average. Near-term support is $434.16, while resistance sits at $548.38.


Recent News and Developments

WDC drops 4.43% after a two-day rally

Western Digital closed at $460.93 on September 10, down 4.43%. The reversal followed gains of 2.14% on September 8 and 1.04% on September 9. Source: StockAnalysis.com

Wall Street sees 45% upside, but Seagate wins the comparison

TipRanks reported a Moderate Buy consensus for WDC and a $680.94 average price target, implying 45% upside. Investor David Sparks preferred Seagate because its 2027 pricing is fixed and most nearline capacity is allocated through 2028, while Western Digital has less disclosed contract visibility beyond 2026. Source: TipRanks

Western Digital targets first-half 2027 HAMR shipments

CFO Kris Sennesael said Western Digital is qualifying its first HAMR drives with four hyperscale customers and expects initial shipments in the first half of 2027. The company is also ramping 40TB ePMR drives and has sent high-bandwidth engineering samples to five customers for products planned above 50TB. Source: StockAnalysis.com


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 43.8% is the strongest reason to own WDC. The company generated $12.92 billion in revenue and trades at 17.21 times earnings, a reasonable valuation if that growth continues. Cash of $1.58 billion exceeds total debt of $1.19 billion by $390 million. The $664.92 analyst target implies 43.61% upside from $463.00, and the high-end target reaches $1,050.00. All 24 analysts included in the supplied recommendation data collectively rate WDC a buy. Western Digital is qualifying HAMR drives with four hyperscale customers and expects initial shipments in the first half of 2027. WDC is a buy for investors who believe AI-driven storage demand and higher-capacity drives can sustain growth.
Bear Case
WDC has already risen 411.79% from its 52-week low, so expectations are no longer depressed. The stock is also volatile: it closed at $460.93 on September 10 after falling 4.43%, reversing gains of 2.14% on September 8 and 1.04% on September 9. Near-term resistance at $548.38 could limit the next advance, while a break below $434.16 would weaken the technical setup. The analyst target range runs from $420.00 to $1,050.00, showing major disagreement about fair value. Seagate has disclosed fixed 2027 pricing and nearline capacity allocations through 2028, while Western Digital has provided less contract visibility beyond 2026. HAMR shipments are not expected until the first half of 2027, leaving meaningful qualification and execution risk. The 43.8% revenue growth rate is compelling, but any slowdown would make the 17.21 P/E harder to defend.
What to Watch
The first technical test is whether WDC holds the $434.16 30-day low. A move above the $548.38 30-day high would clear the stated near-term resistance level. Investors should also watch whether the stock can reclaim and hold its $468.26 20-day moving average while preserving its 7.10% five-day and 10.16% 20-day momentum. The next major product catalyst is HAMR qualification with four hyperscale customers ahead of expected shipments in the first half of 2027. Progress ramping 40TB ePMR drives and converting samples sent to five customers into products above 50TB would strengthen the growth case. Revenue growth needs to remain strong relative to the current 43.8% rate to support the bullish thesis. Additional contract visibility beyond 2026 would directly address the competitive concern raised in the Seagate comparison.
Analyst Consensus
BUY

Based on 24 analyst opinions
Low Target
$420.00
Mean Target
$664.92
High Target
$1050.00


Earnings and Financial Data

Sector
Technology
Industry
Computer Hardware
Employees
40,000
Earnings & Dividends
Next Earnings
Nov 05, 2026
EPS (Trailing)
$26.91
Dividend Yield
12.0%
Payout Ratio
1.9%

Frequently Asked Questions

Is WDC a good stock to buy?
The supplied data gives WDC a buy recommendation from 24 analysts, supported by 43.8% revenue growth and a 17.21 P/E. The takeaway is that analysts are bullish, but the stock’s 411.79% rise from its 52-week low raises the risk of buying after a major run.
What is WDC’s price target?
The analyst target is $664.92, with estimates ranging from $420.00 to $1,050.00. The takeaway is that the average target sits above the $463.00 share price, but analyst expectations vary widely.
Is WDC stock overvalued?
WDC trades at 17.21 times earnings while revenue is growing 43.8%. The takeaway is that the valuation looks supportable if growth continues, but the provided data does not establish that WDC is definitively undervalued.
What are WDC’s support and resistance levels?
Near-term support is the 30-day low of $434.16, and near-term resistance is the 30-day high of $548.38. The takeaway is that these are the key price thresholds to monitor.
Does WDC pay a dividend?
The supplied key and technical data do not provide dividend information. The takeaway is that no dividend conclusion can be made from the available data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 19, 2026.