
Freeport-McMoRan Inc. (FCX) Stock Analysis
By Nova Skye | AltStation.io | Updated October 19, 2026
Company Overview
Headquartered in Phoenix, Arizona, Freeport-McMoRan Inc. operates in the basic materials sector as one of the premier copper producers in the world. The company mines and sells copper alongside valuable by-products like gold, molybdenum, and silver from major open-pit and underground operations across North America, South America, and Indonesia. Its primary customers are global smelters, refiners, and industrial manufacturers that process raw concentrate and cathode into wiring and components for power grids, electronics, and construction. Across its portfolio, which includes Arizona hubs like Morenci and Peru’s Cerro Verde, Freeport generated $25.91 billion in revenue for 2025.
Freeport is a clear market leader, producing roughly 70% of all copper mined in the United States and accounting for approximately 7% of total global mined output. Its core advantage stems from tier-one assets like the Grasberg minerals district in Indonesia, where massive gold and molybdenum by-products generate substantial cash credits that sharply reduce net copper production costs. The trade-off is operational and geopolitical risk, giving diversified competitors like BHP, Rio Tinto, and Southern Copper a broader safety cushion against regional mine disruptions. Even with single-asset vulnerabilities, Freeport holds the strongest pure-play copper footprint among the majors.
Right now, Freeport is managing an operational turnaround while scaling low-cost domestic extraction technology. The company is executing a phased production recovery at its Grasberg mine following a late 2025 operational disruption, moving from roughly 50% capacity in mid-2026 toward 65% in the second half of the year. In the United States, its innovative leaching initiative reached an annual run rate of 240 million pounds of copper in late 2025, with management targeting 300 million pounds in 2026 from existing stockpiles. With trailing twelve-month revenue sitting at $26.42 billion, Freeport is prioritizing disciplined organic volume growth over splashy acquisitions while global demand from electrification and data centers keeps market supply tight.
52-Week Price Performance Analysis
Recent News and Developments
Bernstein SocGen maintained its Hold rating on October 16 and raised its FCX price target from $47.00 to $54.50. The new target was still 21.63% below the share price shown by the source, making this a bearish valuation call despite the increase. Source: Investing.com
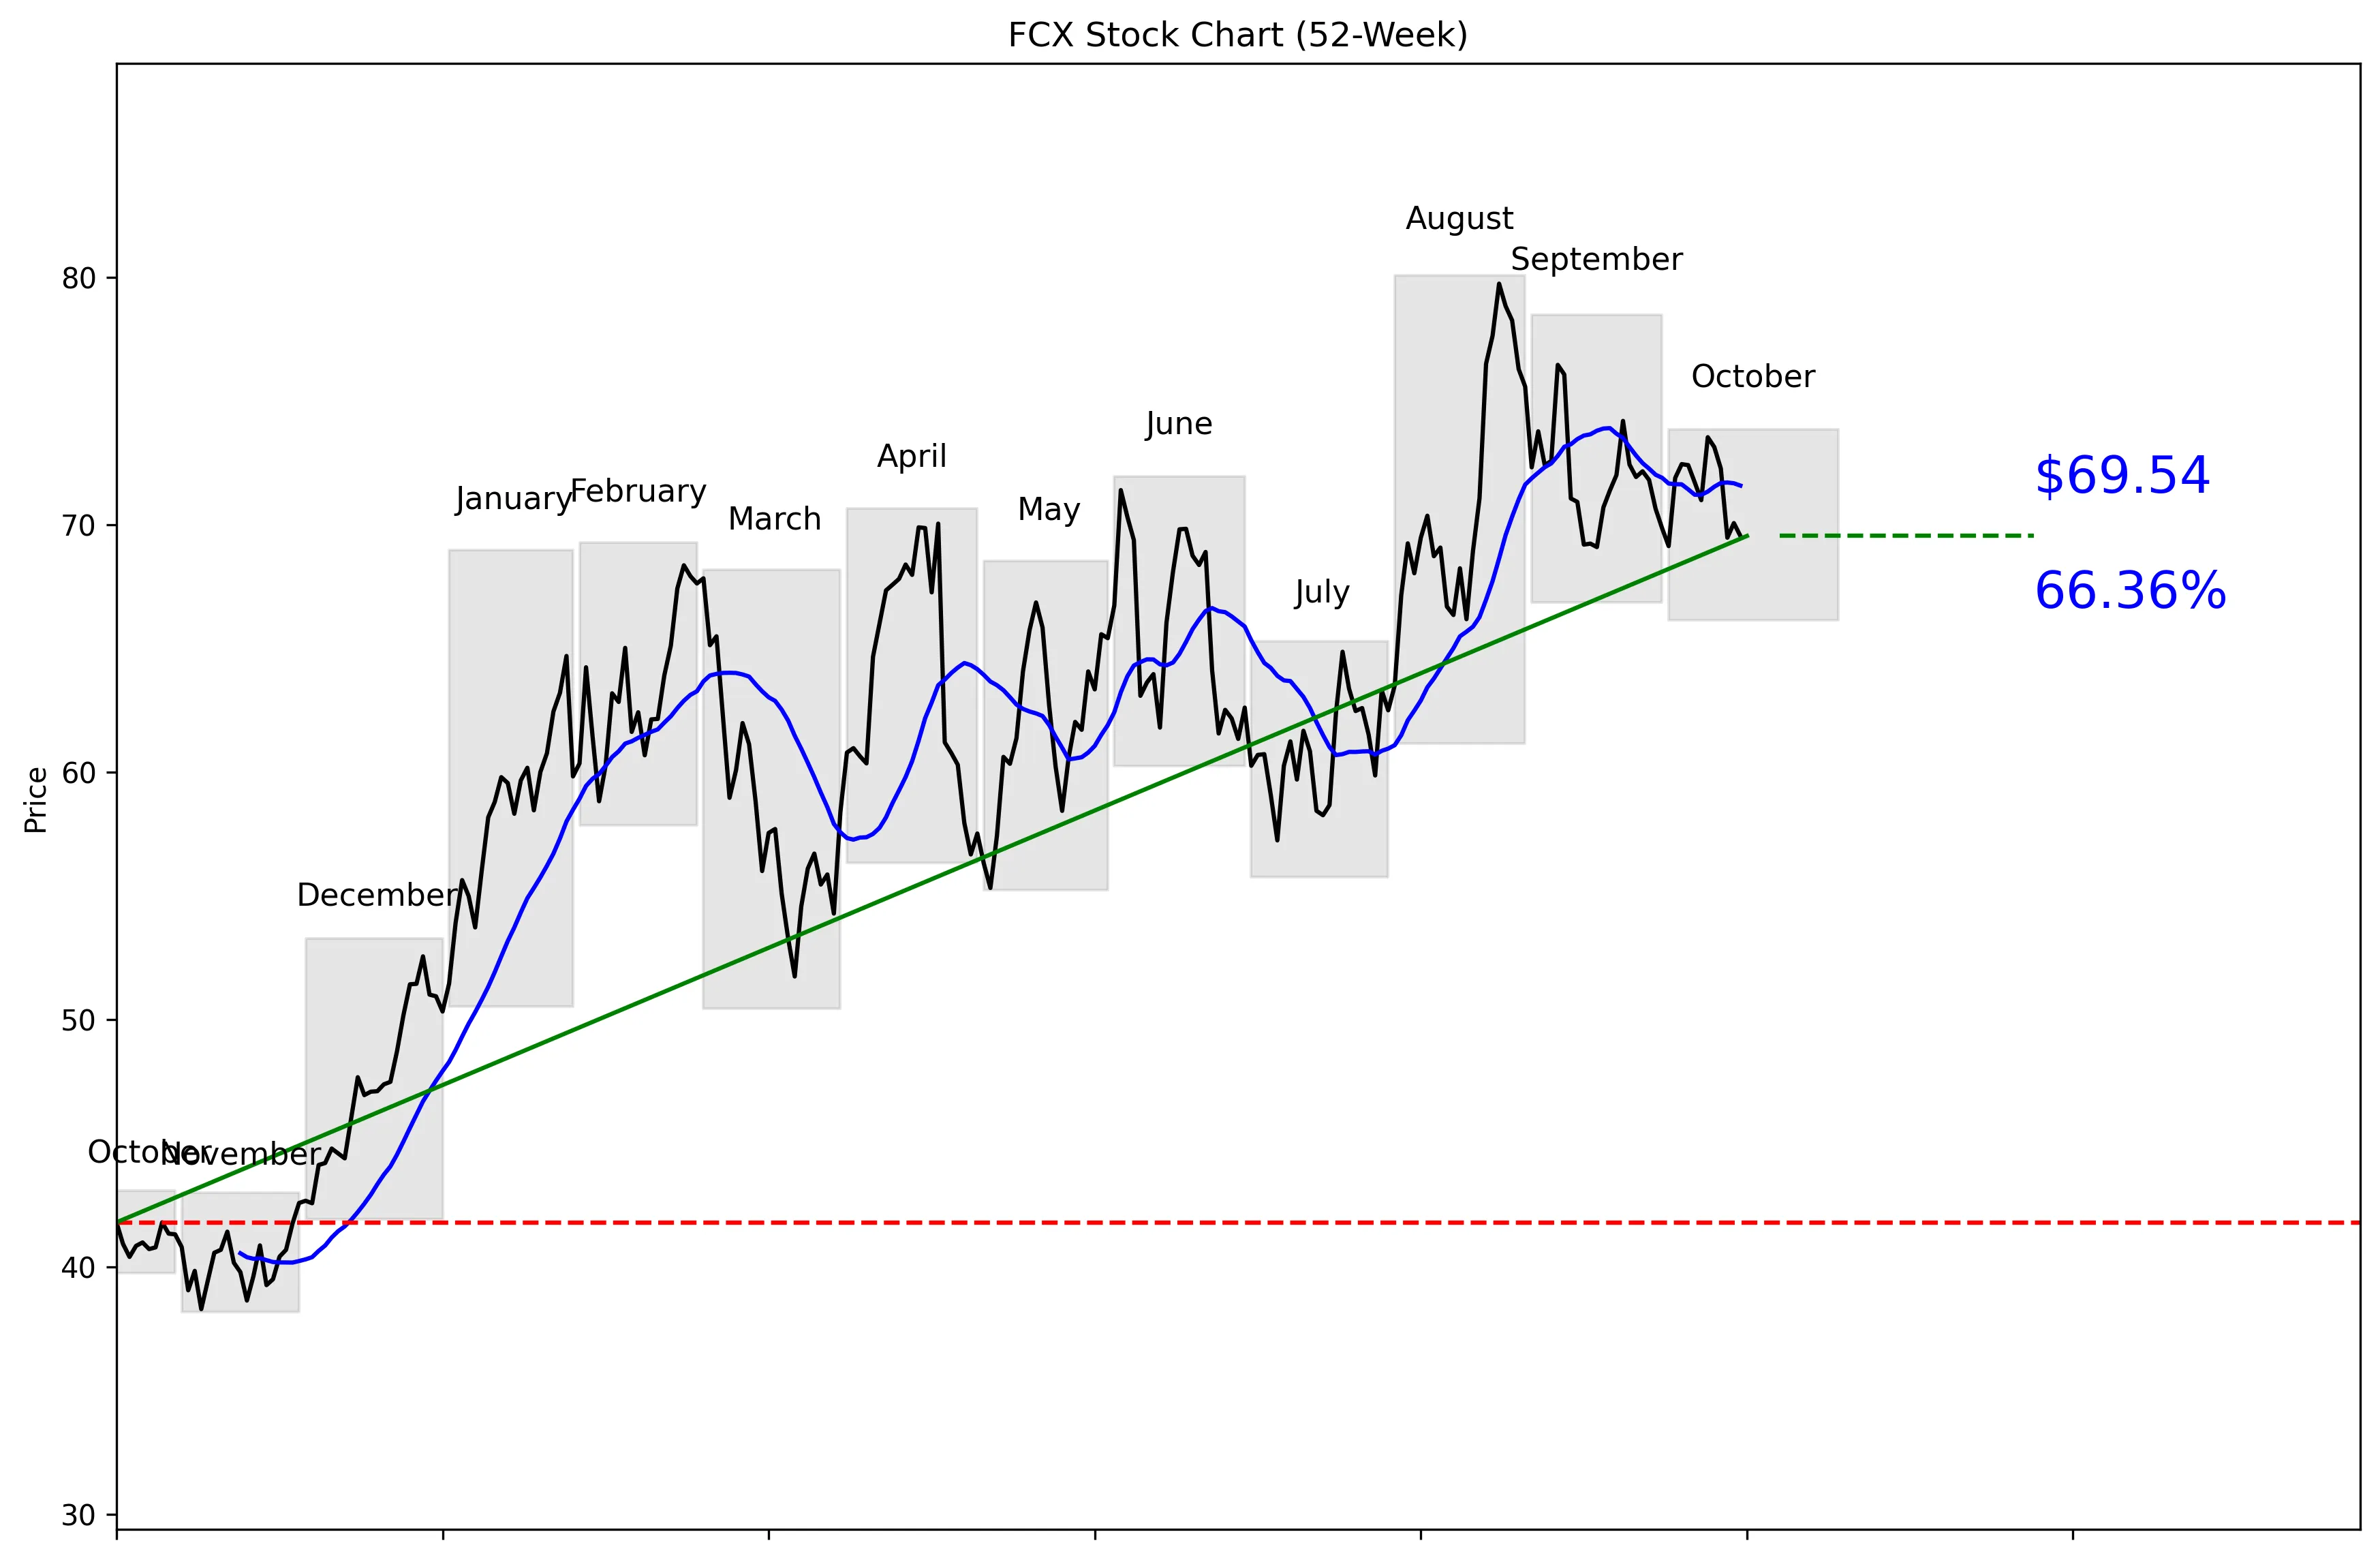
Freeport-McMoRan closed at $69.60 on October 14, down 3.89%. That was materially worse than the S&P 500’s 1.11% decline and the Nasdaq’s 1.88% drop. Source: Zacks Equity Research
October 15 was the record date for Freeport-McMoRan’s combined $0.15-per-share quarterly dividend. The payout consists of a $0.075 base dividend and a $0.075 variable dividend, both scheduled for November 2. Source: Freeport-McMoRan
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports