ALTSTATION.IO

CSX Corporation (CSX) Stock Analysis

By Nova Skye | AltStation.io | Updated October 23, 2026

Price
$51.79
Change
+7.00%
Market Cap
$95.94B
Avg Volume
10.7M

Company Overview

CSX Corporation is a Jacksonville, Florida-based freight transportation company operating in the Industrials sector under the Railroads industry. Incorporated in 1978, the company runs an approximately 20,000 route-mile rail network powered by 3,400 locomotives across 26 states east of the Mississippi River, the District of Columbia, and the Canadian provinces of Ontario and Quebec. It makes its money moving heavy bulk freight—including coal, chemicals, metals, fertilizers, and agricultural goods—for industrial plants, steel manufacturers, and electricity-generating utilities. CSX also links rail to the broader supply chain through trucking operations, approximately 30 intermodal container terminals, and rail-to-truck transfers for automotive and consumer goods shippers.

CSX is an entrenched market leader in Eastern freight rail, effectively sharing an impenetrable regional duopoly with Norfolk Southern. Its primary competitive moat is its physical footprint: 20,000 miles of track and direct connections to deep-water export ports that cannot be replicated. High capital costs and regulatory hurdles keep new rail challengers out, though long-haul trucking maintains steady price competition for flexible freight. However, heavy structural exposure to coal and cyclical industrial commodities remains a lingering vulnerability as utility power generation shifts away from fossil fuels.

CSX is currently in an efficiency-first defensive posture while navigating mild top-line contraction. Revenue slipped approximately 1% in 2024 to $14.54 billion, down from $14.66 billion in 2023, weighed down by lower fuel surcharges, softer benchmark coal pricing, and network disruptions like the Baltimore Key Bridge collapse. Despite these headwinds, the business generated $5.25 billion in 2024 operating income and maintained disciplined operating ratios in the mid-60% range. The strategy right now is clear: defend operating margins through strict cost control and network velocity rather than banking on rapid volume expansion.

Key Financials
Market Cap
$95.94B
Revenue
$14.51B
EBITDA
$6.83B
Gross Margin
47.1%
Profit Margin
22.2%
Revenue Growth
10.1%
Total Cash
$1.39B
Total Debt
$19.45B
Free Cash Flow
$1.95B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
26.97
Forward P/E
22.43
Beta
1.20
52-Week High
$53.60
52-Week Low
$33.63
EPS
$1.92
50-Day Avg
$48.67
200-Day Avg
$45.04
Price/Book
7.32
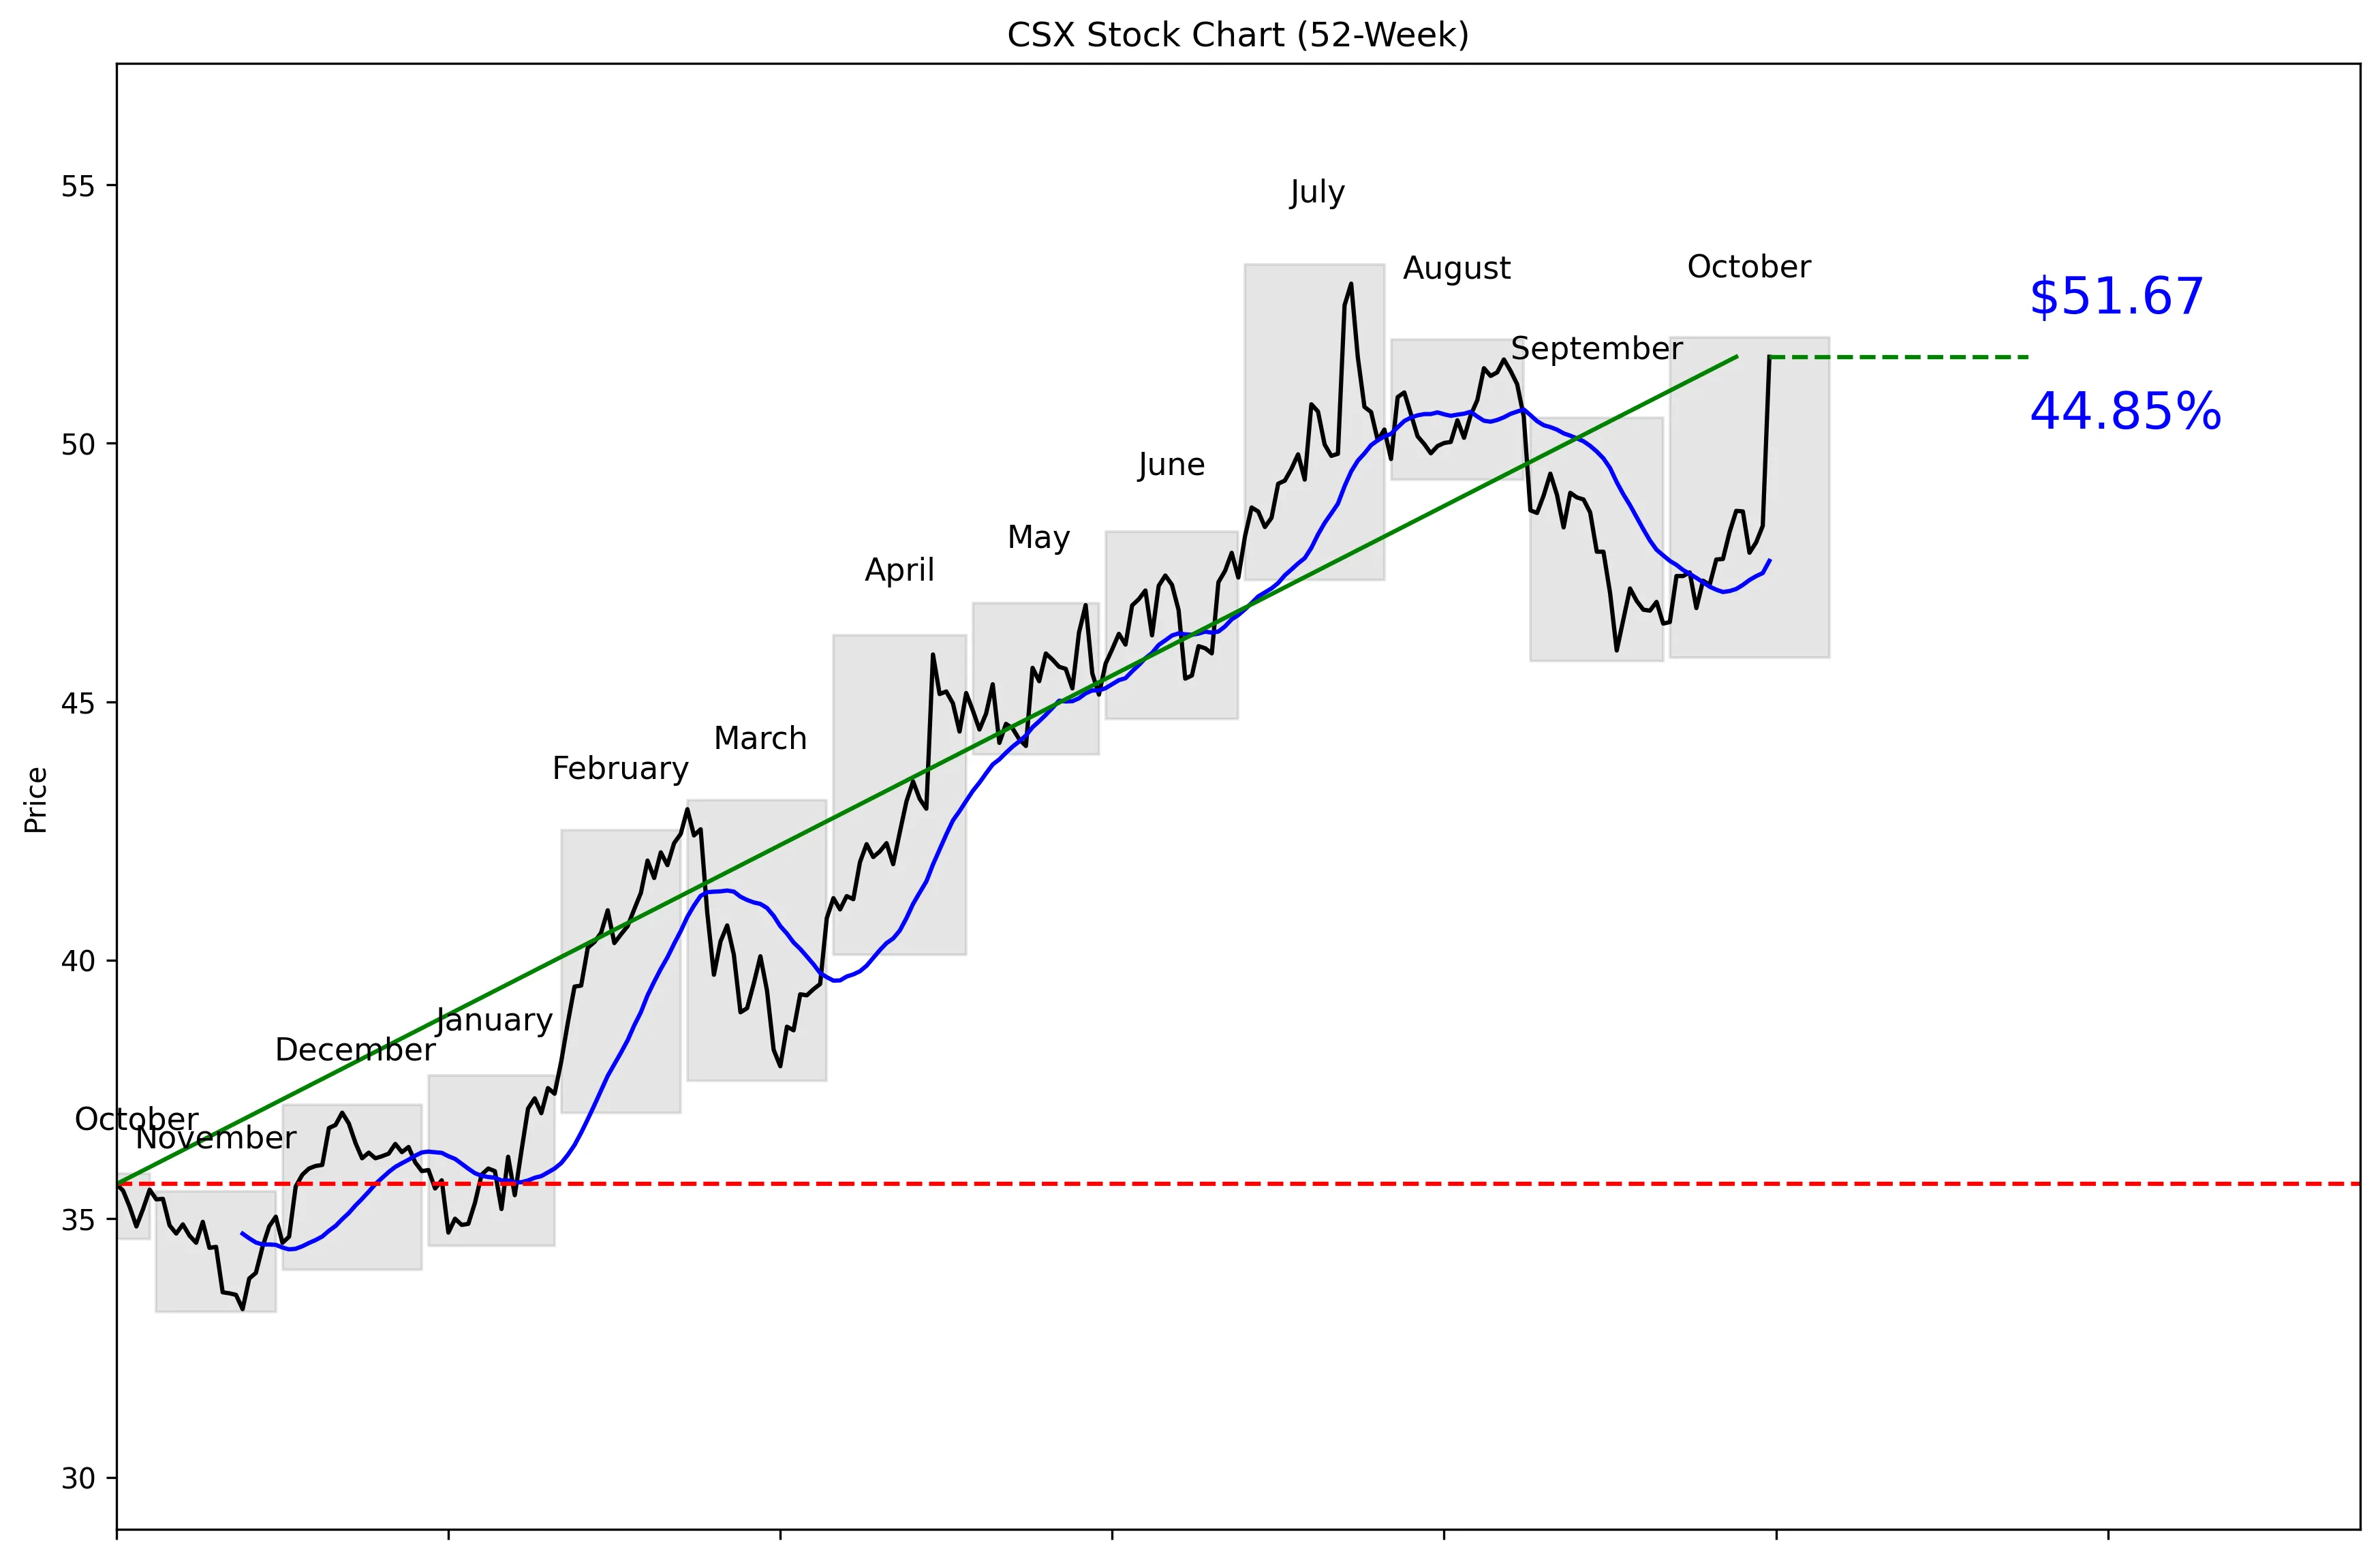
CSX 52-Week Stock Chart
Technical Analysis
CSX trades at $51.79, putting it 91% of the way from its $33.20 low to its $53.45 high. The stock is 3.34% below that high and 55.62% above the low. Price sits 8.27% above the 20-day moving average of $47.72. Momentum is strong at 6.12% over five trading days and 10.05% over 20 trading days. Near-term support is $45.99, while the listed resistance level is $51.67.


Recent News and Developments

CSX posts record revenue and 54% EPS growth

Third-quarter revenue rose 12% year over year to a record $4.02 billion, while diluted EPS climbed 54% to $0.57. Operating income reached $1.57 billion, operating margin expanded 880 basis points to 39.1%, and total volume increased 5%. Source: CSX Corporation

Analysts raise CSX targets as shares jump 6.7%

CSX shares gained 6.7% to $51.58 on October 22 after the earnings beat. JPMorgan raised its target from $57 to $58, TD Cowen moved from $54 to $55, RBC Capital increased from $53 to $54, and Bank of America raised its target from $55 to $57. Source: Benzinga

CSX eliminates 109 management positions

CSX cut 109 operations management jobs while restructuring its engineering functions. The company offered 58 affected employees other operations roles and offered severance to 51; 75% of those offered severance have union seniority and may return to craft positions. Source: FreightWaves


Market Sentiment and Analyst Recommendations

Bull Case
CSX just delivered record quarterly revenue of $4.02 billion, up 12% year over year. Diluted EPS jumped 54% to $0.57, while operating income reached $1.57 billion. The operating margin expanded 880 basis points to 39.1%, showing that revenue growth is translating into stronger profitability. Total volume increased 5%, and overall revenue growth stands at 10.1%. Analysts remain positive, with a buy recommendation from 23 analysts and a consensus target of $53.36. The bull case is straightforward: CSX has strong revenue, volume, earnings, margin, and price momentum at the same time.
Bear Case
CSX is priced for continued execution at 26.97 times earnings. The stock is already 91% of the way through its 52-week range and only 3.34% below its high, leaving less room for operational disappointment. The $53.36 consensus analyst target is only modestly above the current $51.79 price, despite individual targets ranging as high as $60.00. CSX carries $19.45 billion in total debt against $1.39 billion in cash, creating a clear balance-sheet risk. The company also eliminated 109 operations management positions while restructuring its engineering functions, which adds execution risk. A drop below the $47.72 moving average would weaken the technical picture, while a move toward $45.99 would erase much of the recent advance.
What to Watch
The next quarterly report needs to show that the third-quarter performance was sustainable, not a one-quarter spike. Watch whether revenue can build on the record $4.02 billion and whether growth remains near the reported 12% year-over-year rate. Operating margin is critical after reaching 39.1% and expanding 880 basis points. Volume growth also needs to hold near the latest 5% rate. Investors should monitor whether the October 22 rally holds, after shares gained 6.7% to $51.58 following earnings. Technically, a sustained move above $51.67 would support further strength, while breaks below $47.72 and $45.99 would materially weaken the setup.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$32.00
Mean Target
$53.36
High Target
$60.00


Earnings and Financial Data

Sector
Industrials
Industry
Railroads
Employees
22,200
Earnings & Dividends
Next Earnings
Oct 21, 2026
EPS (Trailing)
$1.92
Dividend Yield
116.0%
Payout Ratio
31.4%

Frequently Asked Questions

Is CSX a good stock to buy?
CSX has a buy recommendation from 23 analysts, 10.1% revenue growth, and positive five-day and 20-day momentum. The takeaway is that the operating and technical data are bullish, but the stock is already near its 52-week high.
What is CSX’s price target?
The consensus analyst target is $53.36, with estimates ranging from $32.00 to $60.00. The takeaway is that analyst expectations vary widely and the consensus target sits close to the current $51.79 price.
Is CSX stock overvalued?
CSX trades at a P/E ratio of 26.97 and sits 91% of the way from its 52-week low to its high. The takeaway is that the valuation and price position leave limited room for weak results.
What are CSX’s support and resistance levels?
Near-term support is $45.99, and near-term resistance is $51.67. The takeaway is that those are the key technical levels to track.
Does CSX pay a dividend?
The provided data does not include CSX’s dividend or dividend yield. The takeaway is that no dividend conclusion can be made from these figures alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 23, 2026.