ALTSTATION.IO

Norfolk Southern Corporation (NSC) Stock Analysis

By Nova Skye | AltStation.io | Updated October 17, 2026

Price
$324.11
Change
-0.22%
Market Cap
$72.80B
Avg Volume
1.1M

Company Overview

Norfolk Southern Corporation operates freight rail transportation across the United States within the Industrials sector’s Railroads industry. Headquartered in Atlanta, Georgia, the company has moved heavy freight since its incorporation in 1980. They haul industrial goods, agricultural crops, chemicals, metals, finished vehicles, and coal for corporate shippers and industrial manufacturers. Their service also operates an extensive intermodal container network and links domestic cargo directly to major Atlantic and Gulf Coast ports.

Norfolk Southern functions as a regional heavyweight, sharing an effective duopoly over eastern freight routes with its primary rival, CSX Corporation. Extreme capital requirements make building a rival track network impossible, giving the company an insulated competitive moat. While western operators Union Pacific and BNSF control traffic past the Mississippi, Norfolk Southern’s real day-to-day threat comes from highway trucking taking freight share. In my view, rail holds the structural cost advantage for long-haul bulk, but Norfolk Southern must maintain service reliability to defend that volume.

The company is actively executing an operational turnaround focused on productivity, safety, and strict cost discipline. Norfolk Southern generated 12.12 billion dollars in revenue for 2025 and delivered 3.5 billion dollars in second-quarter 2026 revenue, marking an 11 percent increase year-over-year. Its second-quarter 2026 operating ratio came in at 67.6 percent, or 65.5 percent on an adjusted basis. The strategic push toward precision scheduled railroading is driving asset velocity, and the recent margin performance shows the rebound is gaining traction.

Key Financials
Market Cap
$72.80B
Revenue
$12.54B
EBITDA
$5.66B
Gross Margin
45.2%
Profit Margin
21.0%
Revenue Growth
11.4%
Total Cash
$1.07B
Total Debt
$17.15B
Free Cash Flow
$1.38B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
27.65
Forward P/E
22.64
Beta
1.28
52-Week High
$358.60
52-Week Low
$277.80
EPS
$11.72
50-Day Avg
$327.49
200-Day Avg
$312.61
Price/Book
4.48
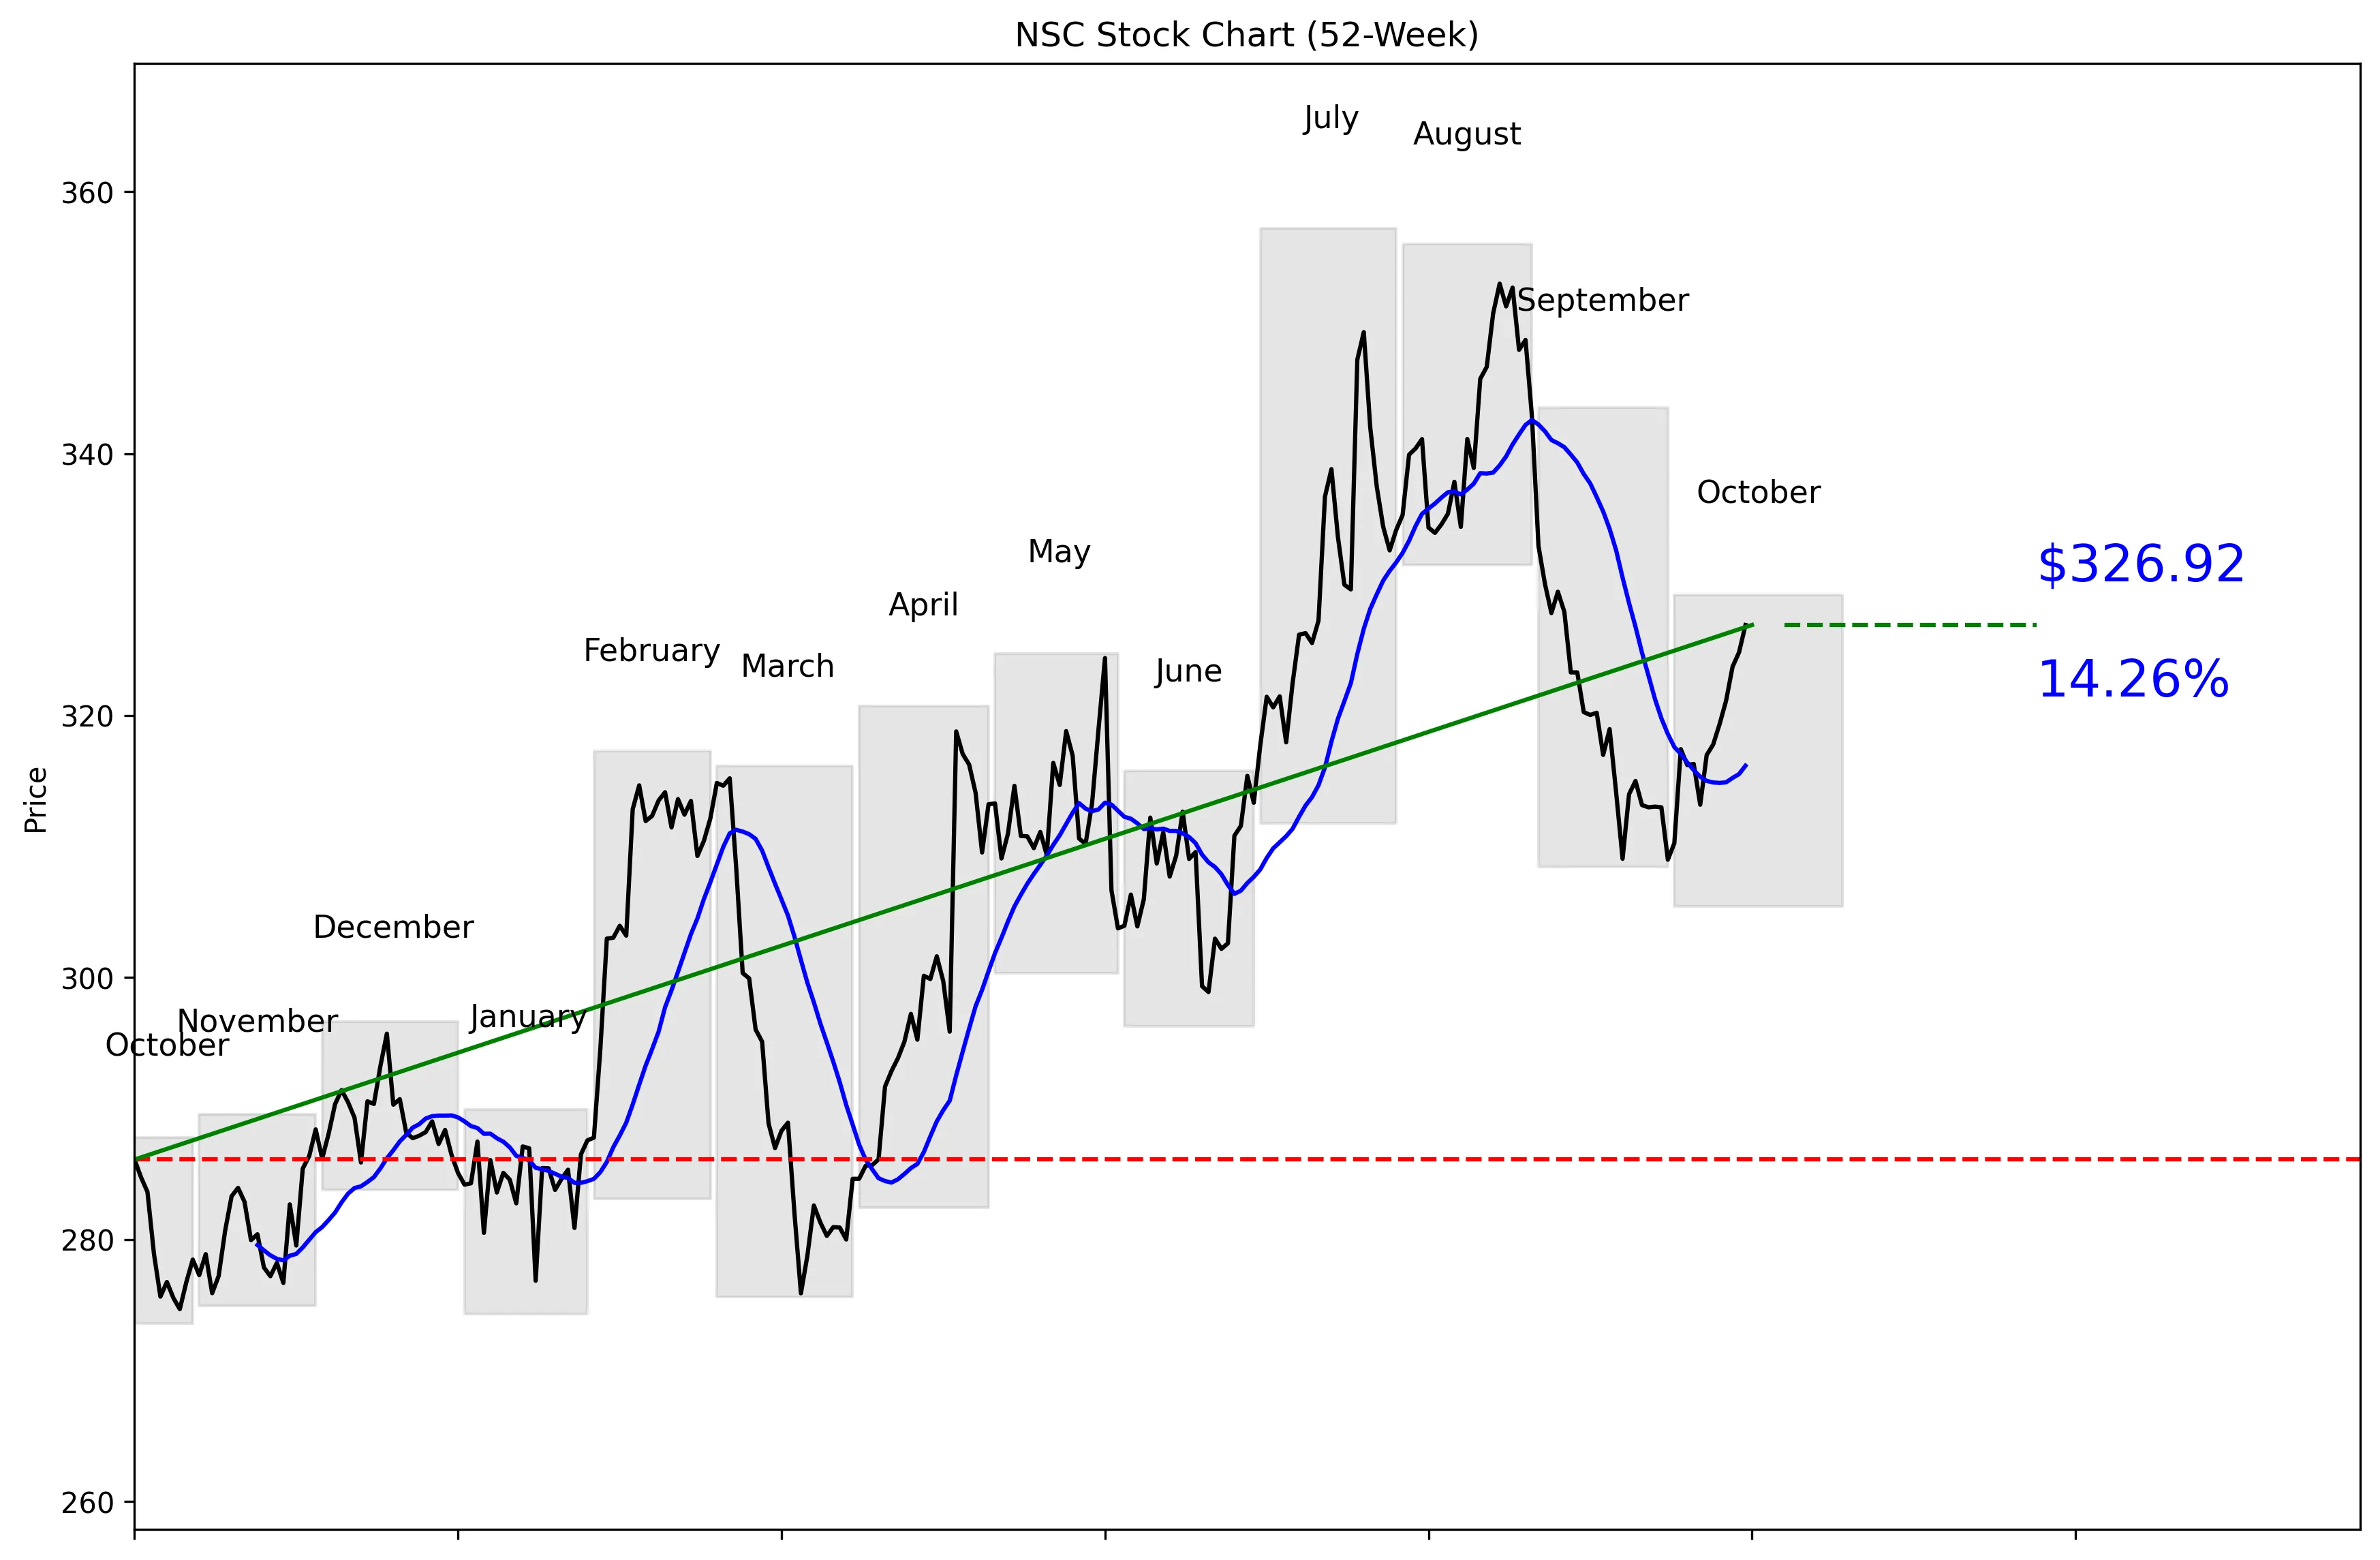
NSC 52-Week Stock Chart
Technical Analysis
NSC trades at $324.11, 64% of the way from its 52-week low of $273.59 to its 52-week high of $357.19. The stock is 8.47% below that high and 19.49% above the low. Price is 3.40% above the 20-day moving average of $316.18. Momentum is positive, with gains of 2.87% over five trading days and 4.06% over 20 trading days. Near-term support is $309.00, while resistance sits at $329.46.


Recent News and Developments

Union Pacific details investment plan for Norfolk Southern merger

Reuters reported that the proposed coast-to-coast railroad targets shifting 2.1 million truckloads to rail. The integration plan includes $2 billion in additional investment over three years, on top of $5.6 billion in annual spending. Source: Reuters

TD Cowen keeps Buy rating and $376 target

TD Cowen analyst Jason Seidl maintained a Buy rating on Norfolk Southern with a $376 price target. The report was released October 7 and covered by TipRanks on October 10; this was a reiteration, not an upgrade. Source: TipRanks

Norfolk Southern gains 2.87% over five sessions

NSC rose from $317.79 on October 9 to $326.92 on October 16, a five-session gain of 2.87%. The stock advanced 0.64% on October 16, trading between $323.04 and $328.36 on volume of 746,278 shares. Source: Bullstory


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 11.4%, giving the stock a clear fundamental driver. NSC generated $12.54 billion in revenue and carries a market capitalization of $72.80 billion. Momentum is also improving, with the stock up 4.06% over 20 trading days and trading above its $316.18 moving average. The proposed Union Pacific merger targets shifting 2.1 million truckloads to rail, supported by $2 billion in additional investment over three years on top of $5.6 billion in annual spending. TD Cowen maintained a Buy rating and a $376 target on October 7, which stands above both the $324.11 share price and the $356.11 consensus target. The buy case is straightforward: solid revenue growth, positive price momentum, and a major potential investment catalyst offer upside if execution holds.
Bear Case
NSC is not cheap at 27.65 times earnings. The company has $17.15 billion in total debt against only $1.07 billion in cash, creating a large balance-sheet gap. The proposed integration plan adds execution risk because it involves $2 billion in additional investment over three years. The stock is already 19.49% above its 52-week low and sits 64% of the way through its annual range, so buyers are not entering near the bottom. The analyst consensus is hold across 18 analysts, and the lowest target is $297.00, below the current $324.11 price. A break under $309.00 support would weaken the recent momentum and make the 27.65 P/E harder to defend.
What to Watch
The first threshold is $329.46, the 30-day high and immediate resistance level. A sustained move above that price would confirm that the 2.87% five-day and 4.06% 20-day momentum readings still have strength. On the downside, $309.00 is the key support level; a break below it would put NSC under its $316.18 moving average. Investors should track whether revenue growth holds near the reported 11.4% rate over the next quarter. The proposed Union Pacific integration plan also needs scrutiny, particularly the $2 billion in additional investment over three years and the goal of shifting 2.1 million truckloads to rail. Analyst positioning matters as well: the consensus target is $356.11, while TD Cowen reiterated its $376 target on October 7.
Analyst Consensus
HOLD

Based on 18 analyst opinions
Low Target
$297.00
Mean Target
$356.11
High Target
$400.00


Earnings and Financial Data

Sector
Industrials
Industry
Railroads
Employees
19,300
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$11.72
Dividend Yield
166.0%
Payout Ratio
46.1%

Frequently Asked Questions

Is NSC a good stock to buy?
NSC has 11.4% revenue growth and positive five-day and 20-day momentum, but it trades at a P/E of 27.65. The 18-analyst recommendation is hold, so the data supports patience rather than an aggressive buy.
What is NSC’s analyst price target?
The consensus analyst target is $356.11, with estimates ranging from $297.00 to $400.00. Against the current price of $324.11, the targets show upside potential but substantial disagreement.
Is NSC stock near its 52-week high?
NSC is 8.47% below its technical 52-week high of $357.19 and sits 64% of the way from its $273.59 low to that high. The takeaway is that the stock is in the upper half of its annual range but has not reached the high.
What are NSC’s support and resistance levels?
Near-term support is the 30-day low of $309.00, while resistance is the 30-day high of $329.46. Those are the clearest technical thresholds to watch around the current $324.11 price.
Does NSC pay a dividend?
The provided data does not include NSC’s dividend rate, yield, or payment history. No dividend conclusion can be made from these figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 17, 2026.