ALTSTATION.IO

Westinghouse Air Brake Technologies Corporation (WAB) Stock Analysis

By Nova Skye | AltStation.io | Updated October 03, 2026

Price
$279.46
Change
-0.13%
Market Cap
$47.20B
Avg Volume
927.6K

Company Overview

Westinghouse Air Brake Technologies Corporation, known as Wabtec, builds the heavy locomotives, braking systems, and digital signaling software that keep global rail networks moving. Headquartered in Pittsburgh, United States, the company operates within the Industrials sector and Railroads industry across two divisions: Freight and Transit. They sell diesel-electric and natural gas locomotives, positive train control electronics, HVAC units, and track maintenance services directly to freight rail operators and public transit agencies. Founded in 1869, the company pairs equipment manufacturing with recurring aftermarket services like overhauls and parts exchanges to generate steady revenue.

Wabtec holds a clear leadership position in heavy freight rail, sharing a virtual duopoly in North American locomotives with Caterpillar’s Progress Rail. Its real competitive moat is its massive installed base of equipment, which locks railroad operators into high-margin, multi-year maintenance and component contracts. In passenger transit and specialized components, it faces sharp global competition from players like Knorr-Bremse in braking and Alstom in rolling stock. The primary threat to its business is the expensive shift toward alternative propulsion like battery-electric power, combined with cyclical freight shipping volume that can slow new equipment orders.

The company is firmly in growth mode, lifting total revenue by 7.5% from $10.39 billion in 2024 to $11.17 billion in 2025. That growth is backed by a massive multi-year order backlog of roughly $30.93 billion as of mid-2026. Strategically, Wabtec is pivoting deeper into digital rail optimization and fleet modernization overhauls, which deliver higher margins than base manufacturing. This combination of digital rail management and long-term service contracts makes Wabtec one of the most resilient cash generators in heavy manufacturing.

Key Financials
Market Cap
$47.20B
Revenue
$11.98B
EBITDA
$2.65B
Gross Margin
35.7%
Profit Margin
10.6%
Revenue Growth
17.5%
Total Cash
$660.00M
Total Debt
$6.94B
Free Cash Flow
$1.10B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
37.56
Forward P/E
22.46
Beta
0.93
52-Week High
$306.64
52-Week Low
$184.26
EPS
$7.44
50-Day Avg
$283.25
200-Day Avg
$253.43
Price/Book
4.21
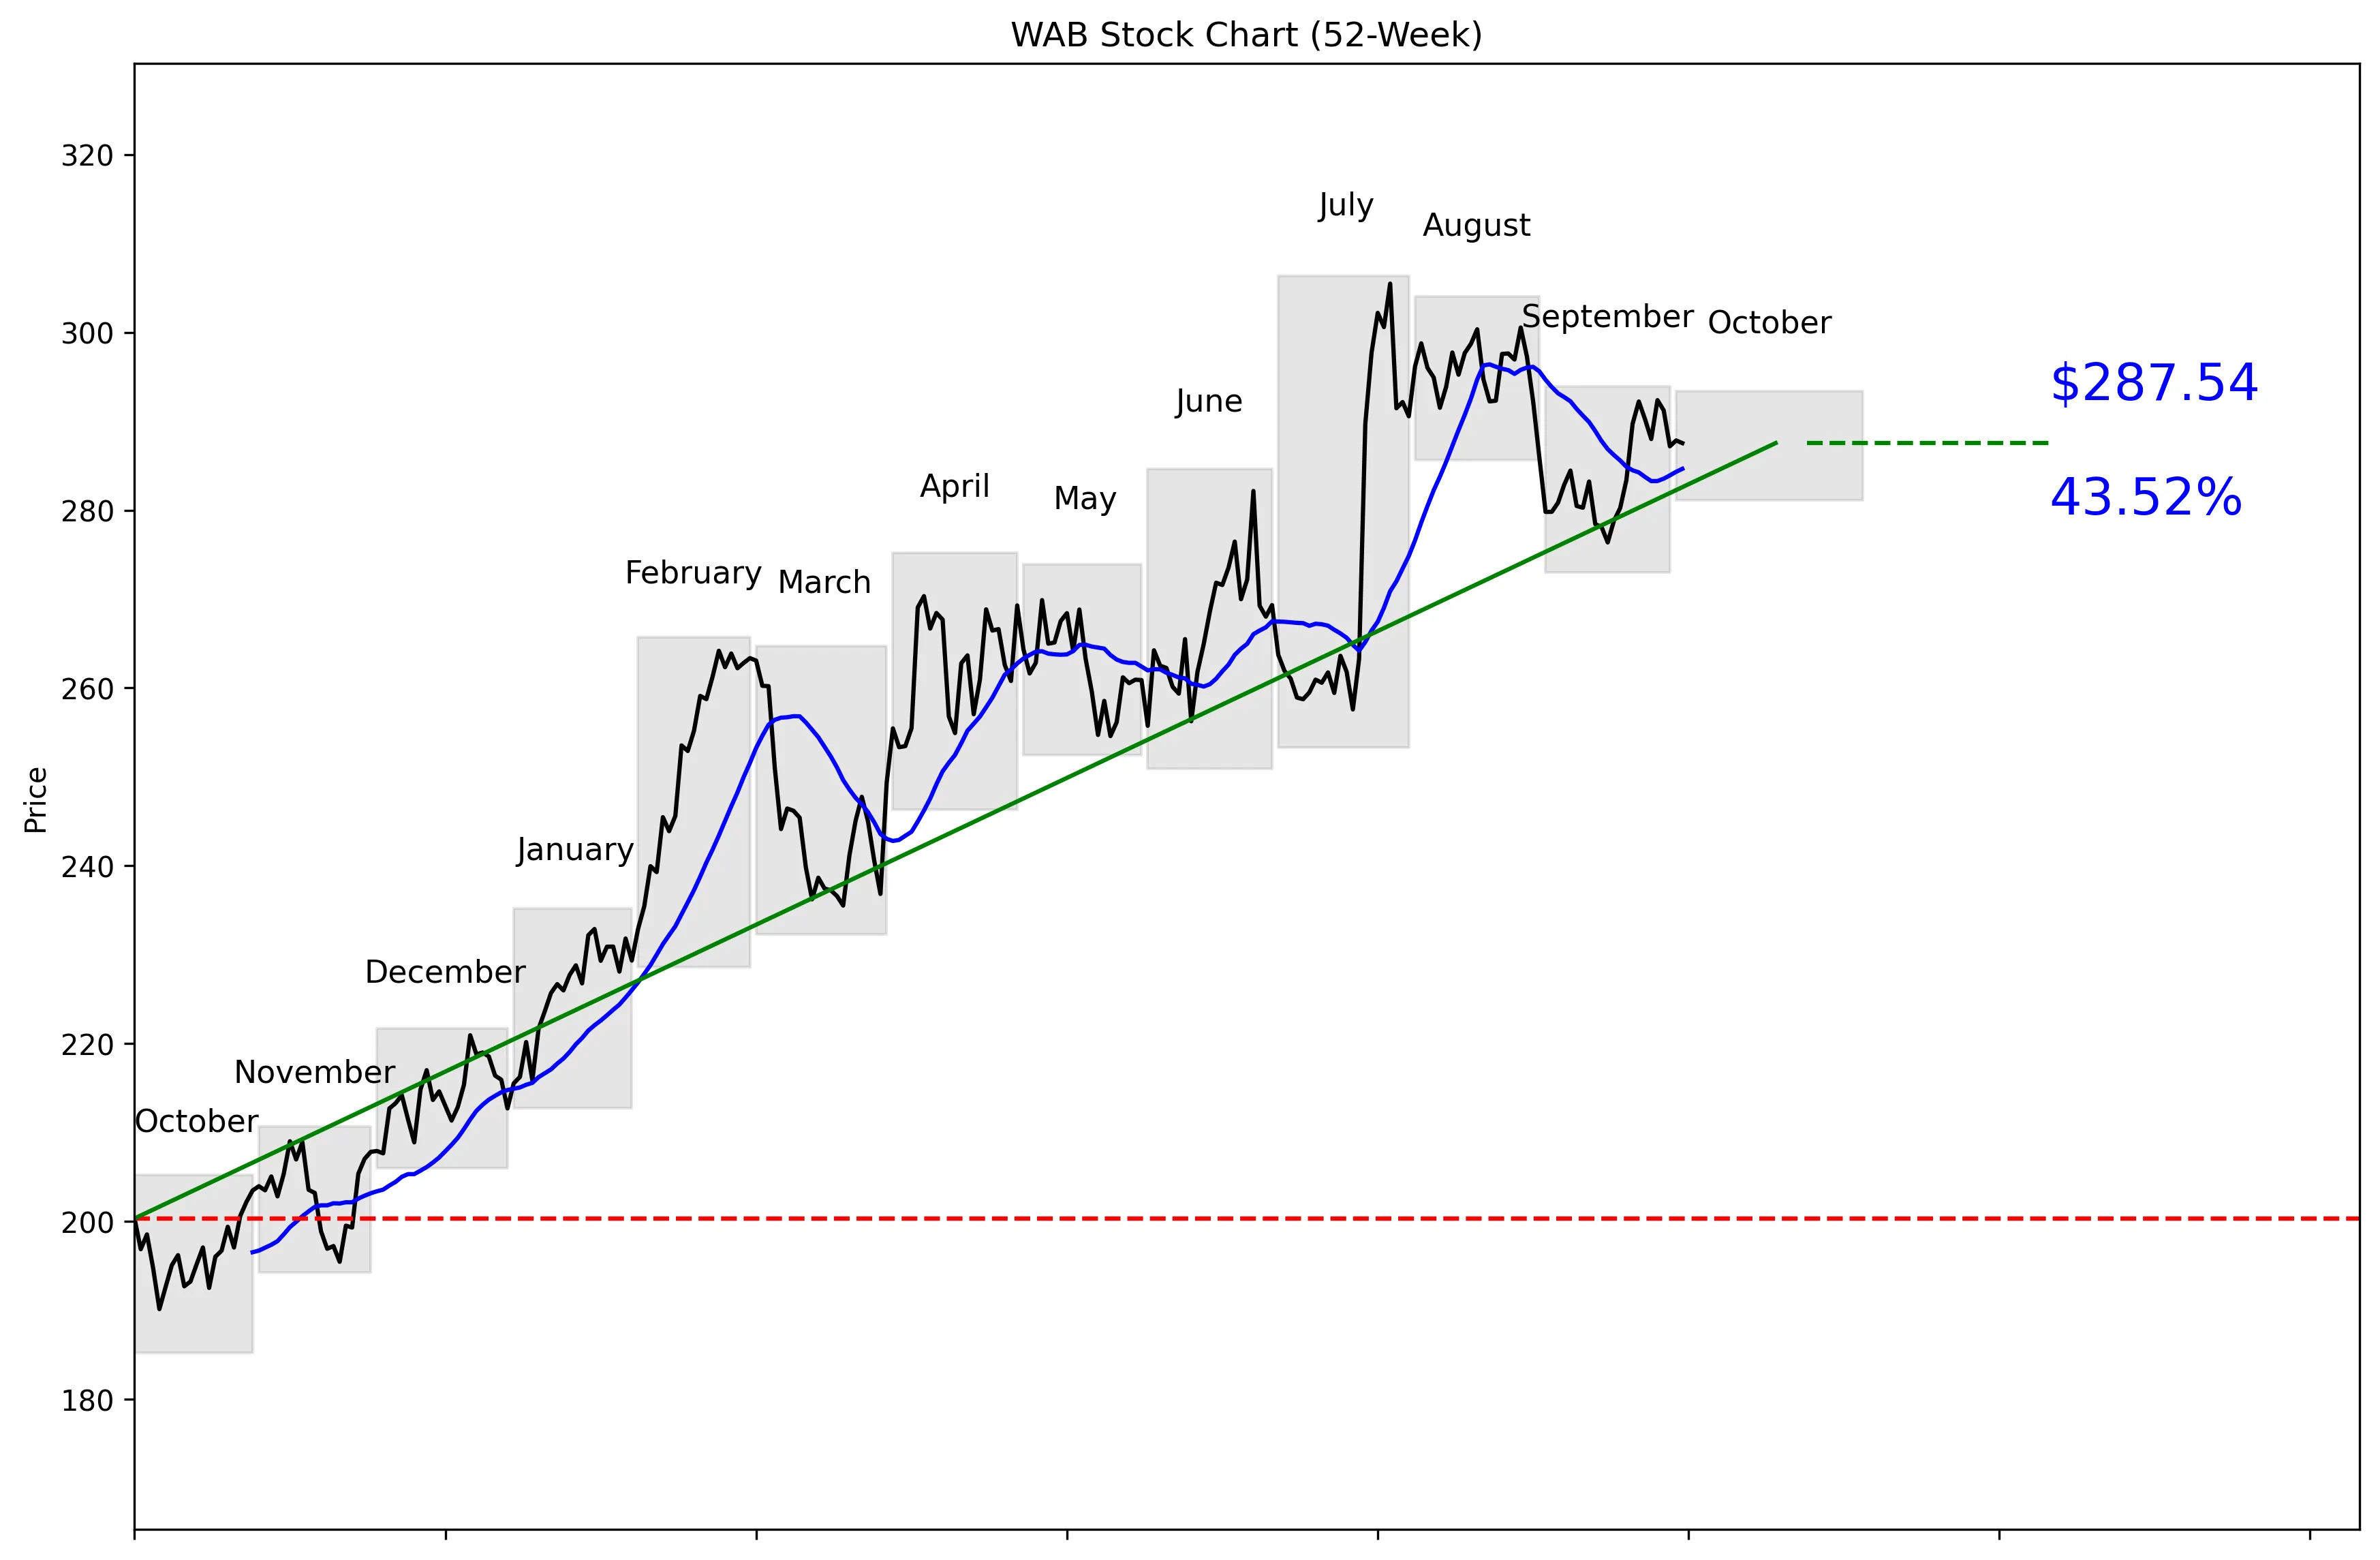
WAB 52-Week Stock Chart
Technical Analysis
WAB trades at $279.46, placing it 84% of the way from its $185.19 52-week low to its $306.32 high. The stock is 6.13% below that high and 55.26% above the low, so the long-term trend remains strong despite the recent pullback. Five-day momentum is negative at 0.16%, while 20-day momentum remains positive at 2.39%. The price is below the $284.65 20-day moving average, showing some near-term weakness. Support is $276.37, while resistance sits at $300.54.


Recent News and Developments

Wabtec opens $2 billion short-term funding program

Wabtec established a commercial-paper program on October 1 allowing up to $2 billion of unsecured notes outstanding at any time. Notes can mature within 397 days, but the company had issued none when it filed the 8-K. Source: Wabtec Corporation

Wabtec sets October 21 earnings date

Wabtec will release third-quarter 2026 results before the market opens on October 21. Its conference call starts at 8:30 a.m. ET that day. Source: Wabtec Corporation

WAB gains 1.55% to $292.47

WAB closed September 28 at $292.47, up 1.55%, on volume of 789,452 shares. The stock remained $14.17 below its $306.64 52-week high. Source: AD HOC NEWS


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $11.98 billion and growing 17.5%, which is the clearest reason to own WAB. The analyst consensus is strong buy across 12 analysts. Their average target is $329.17, with estimates ranging from $292.00 to $355.00, all above the current $279.46 price. Morgan Stanley reinforced the bullish view on September 27 by maintaining its Buy rating and $355 target. Wabtec will report third-quarter 2026 results on October 21, giving investors a near-term catalyst. The stock also remains 6.13% below its 52-week high, leaving room for another run if earnings support the growth story. My take: 17.5% revenue growth and unanimous target upside make WAB attractive, but the valuation demands continued execution.
Bear Case
The P/E ratio is 37.56, so WAB is priced for strong growth and clean execution. That valuation leaves little room for an earnings disappointment on October 21. Total debt stands at $6.94 billion against only $660 million in cash, creating a meaningful balance-sheet gap. The new commercial-paper program permits up to $2 billion of unsecured notes with maturities of up to 397 days, adding another funding channel that investors need to monitor. No notes had been issued when the company filed the program, but future use could increase short-term obligations. The stock is already 84% of the way through its 52-week range and 55.26% above its low, so buyers are not entering at a depressed price. Near-term momentum has also softened, with a 0.16% five-day decline and the price below the $284.65 moving average.
What to Watch
The main catalyst is Wabtec’s third-quarter 2026 earnings release before the market opens on October 21. The conference call begins at 8:30 a.m. ET, and investors should focus on whether reported performance supports the current 17.5% revenue growth rate. Price action around $276.37 matters because that is the 30-day low and nearest stated support level. A recovery above the $284.65 20-day moving average would improve the near-term setup. The next upside test is $300.54, followed by the $306.32 52-week high. Investors should also watch whether Wabtec begins issuing notes under its new $2 billion commercial-paper program and how that affects its existing $6.94 billion debt load. A sustained break below $276.37 or weaker growth would damage the thesis, while strong earnings and a move through $300.54 would strengthen it.
Analyst Consensus
STRONG BUY

Based on 12 analyst opinions
Low Target
$292.00
Mean Target
$329.17
High Target
$355.00


Earnings and Financial Data

Sector
Industrials
Industry
Railroads
Employees
31,000
Earnings & Dividends
Next Earnings
Oct 21, 2026
EPS (Trailing)
$7.44
Dividend Yield
44.0%
Payout Ratio
15.1%

Frequently Asked Questions

Is WAB a good stock to buy?
WAB carries a strong-buy recommendation from 12 analysts and has 17.5% revenue growth. The takeaway is that the growth case is strong, but the 37.56 P/E makes execution important.
What is WAB’s price target?
The average analyst target is $329.17, with a range from $292.00 to $355.00. The takeaway is that every listed target is above the current $279.46 price.
What are WAB’s support and resistance levels?
Near-term support is $276.37, while near-term resistance is $300.54. The takeaway is that these are the key 30-day levels to watch.
Is WAB near its 52-week high?
WAB is 6.13% below its $306.32 52-week high and sits 84% of the way from its $185.19 low to that high. The takeaway is that WAB remains near the upper end of its annual range.
Does WAB pay a dividend?
The provided data does not include dividend information, so no dividend amount or yield can be confirmed. The takeaway is that investors should not assume a dividend from this data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 03, 2026.