ALTSTATION.IO

DaVita Inc. (DVA) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$186.81
Change
-0.27%
Market Cap
$11.92B
Avg Volume
755.1K

Company Overview

DaVita Inc. runs kidney dialysis facilities across the United States for patients suffering from chronic kidney failure and end-stage renal disease. Headquartered in Denver, Colorado, the company operates in the healthcare sector under medical care facilities. Its core revenue comes from outpatient dialysis treatments, hospital inpatient care, and specialized clinical laboratory testing. Beyond brick-and-mortar clinics, the company provides home dialysis programs, risk-based disease management, and transplant software.

DaVita is a clear market leader operating in an entrenched duopoly alongside Fresenius Medical Care. Together, both companies control nearly 80% of all dialysis facilities in the United States, with DaVita commanding roughly 37% to 38% market share. That immense physical footprint delivers an insurmountable scale advantage over regional competitors. The primary threat to the business remains regulatory scrutiny over market concentration alongside vulnerability to government reimbursement policy shifts.

The company continues to grow at a reliable pace, booking $13.64 billion in revenue for fiscal year 2025, up 6.5% year over year. Operationally, DaVita is pivoting toward value-based care, with its Integrated Kidney Care platform hitting full-year profitability in 2025 while managing 66,000 risk-based patients. Home dialysis is also expanding rapidly as the company’s fastest-growing modality, now accounting for about 15% of patient treatments. This deliberate shift into home care and integrated management makes DaVita a far more defensive, higher-margin operator than a traditional clinic network.

Key Financials
Market Cap
$11.92B
Revenue
$14.01B
EBITDA
$2.83B
Gross Margin
32.4%
Profit Margin
6.0%
Revenue Growth
5.2%
Total Cash
$688.88M
Total Debt
$13.41B
Free Cash Flow
$1.04B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
15.78
Forward P/E
10.90
Beta
0.80
52-Week High
$247.49
52-Week Low
$101.00
EPS
$11.84
50-Day Avg
$180.49
200-Day Avg
$173.37
Price/Book
-15.62
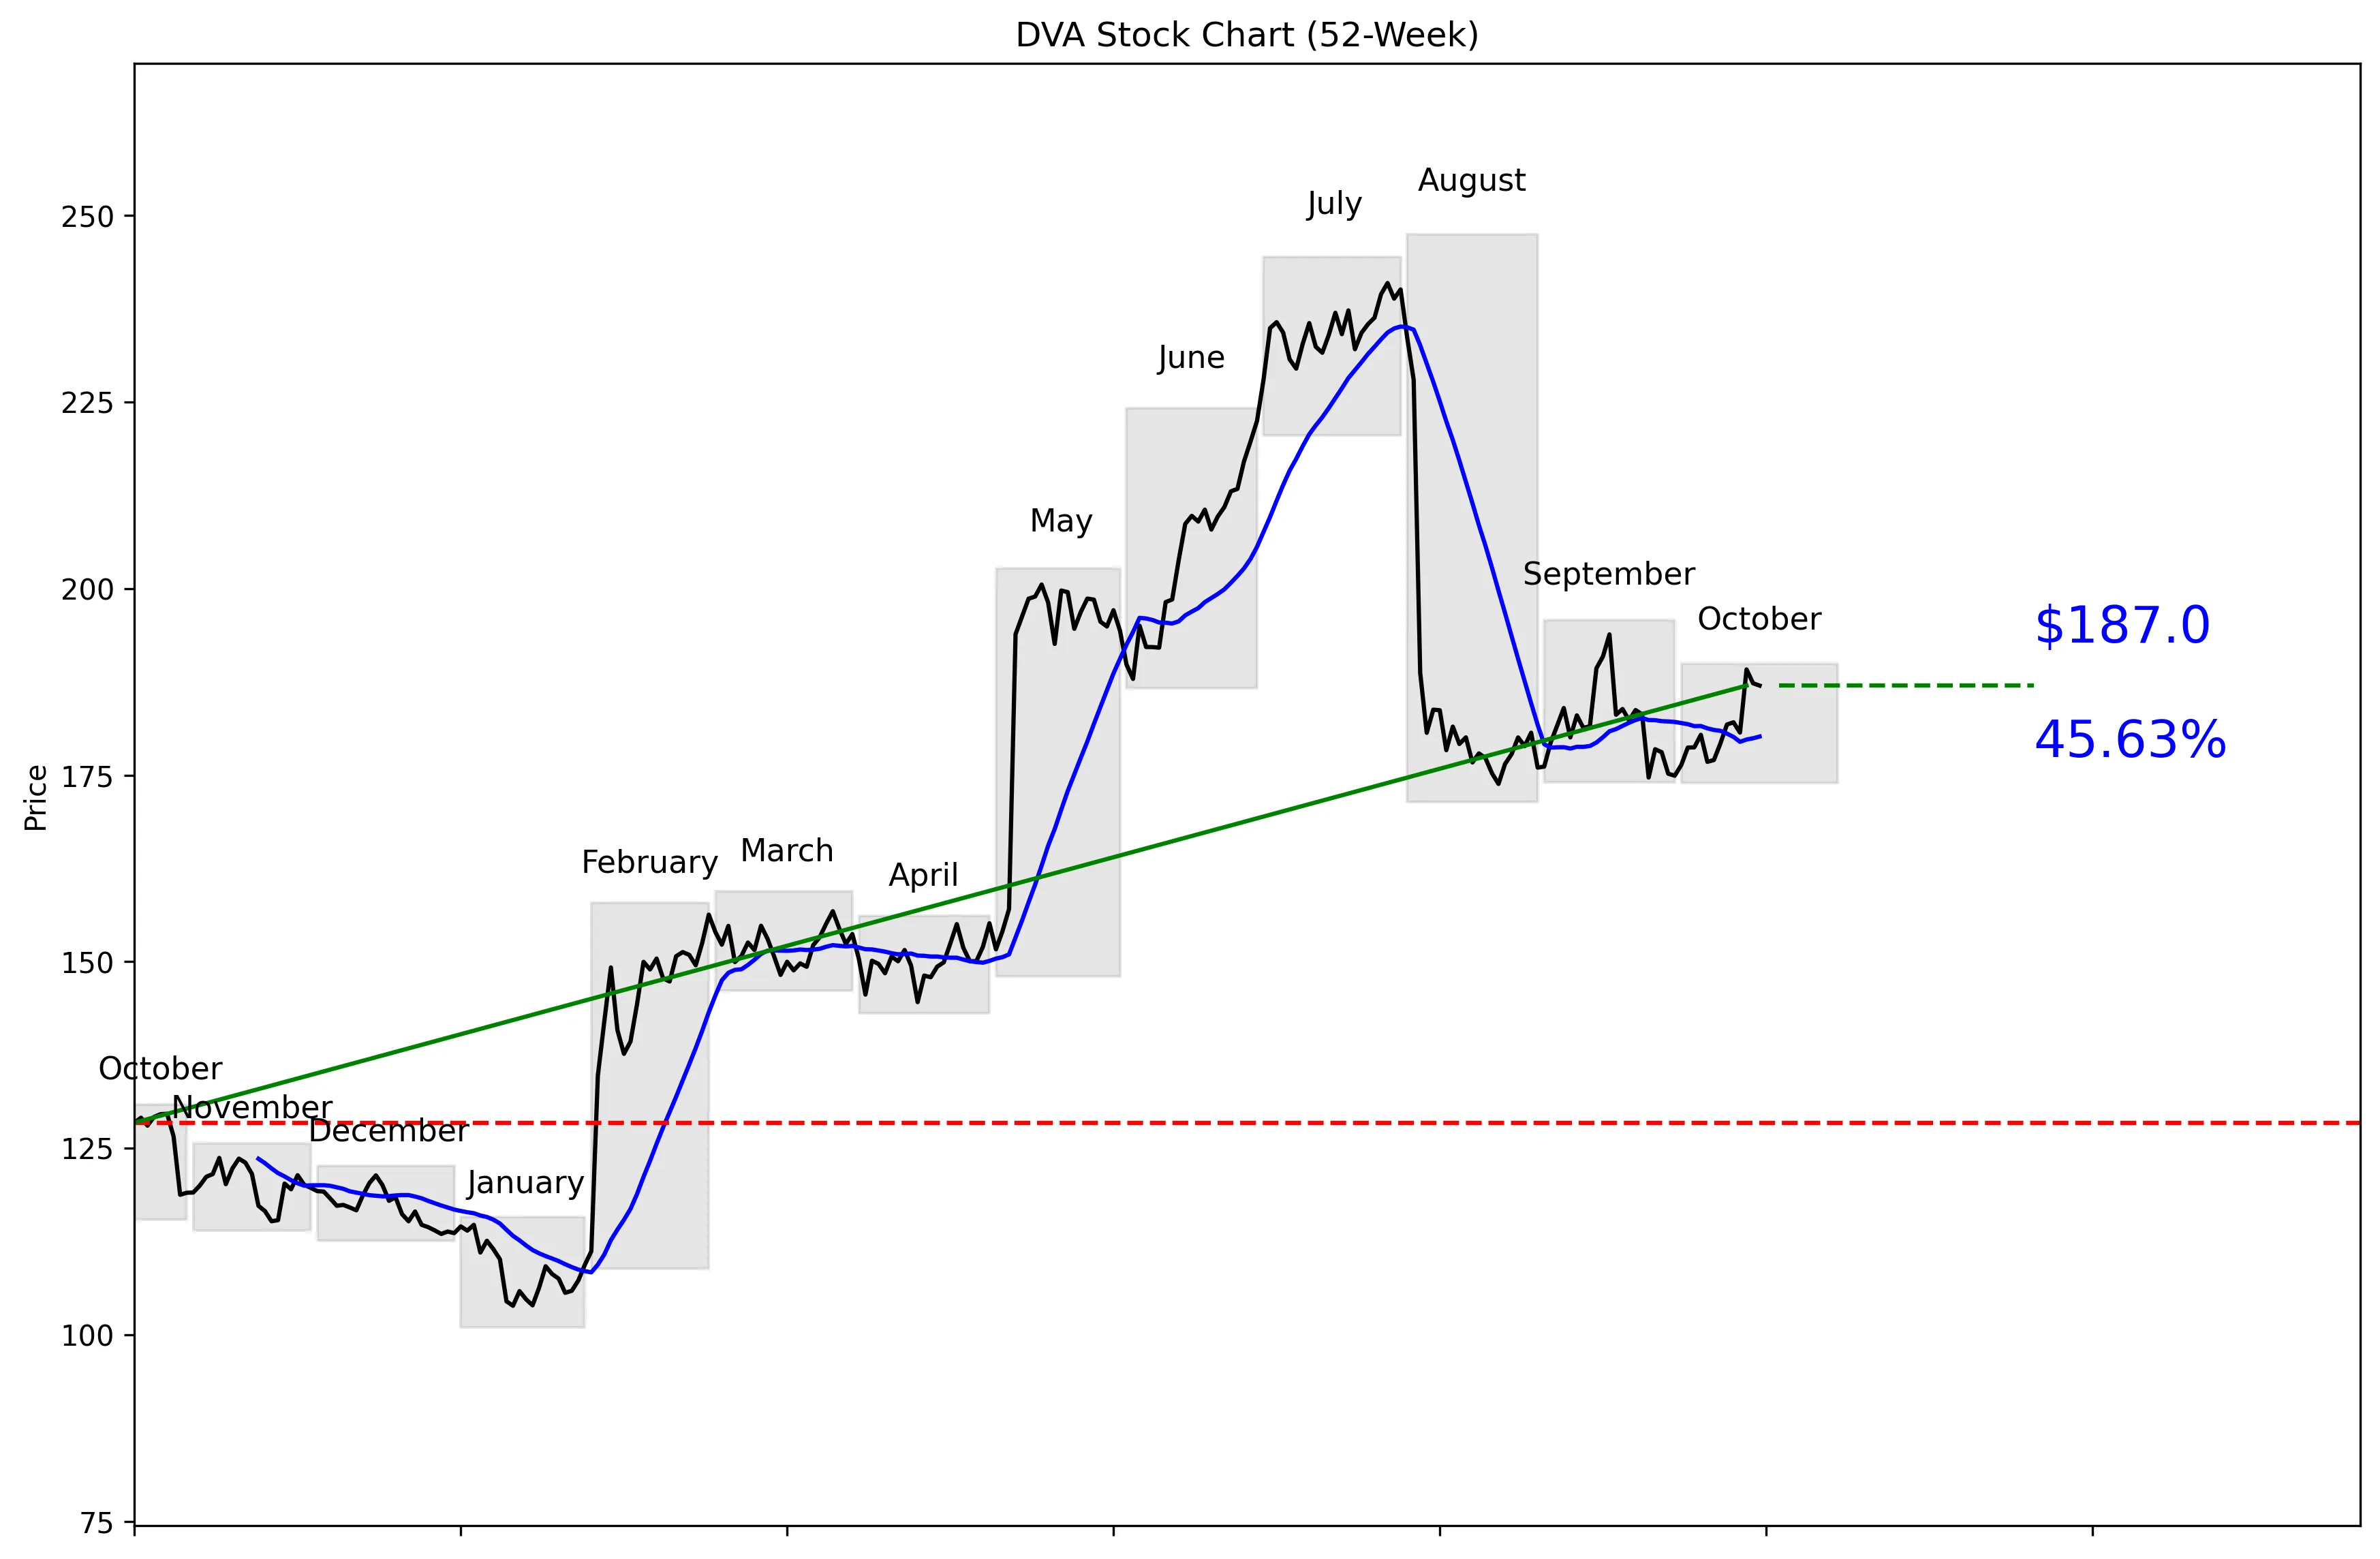
DVA 52-Week Stock Chart
Technical Analysis
DVA trades at $186.81, 59% of the way from its 52-week low of $101.00 to its high of $247.49. The stock is 24.44% below that high but remains 85.15% above the low. Price is 3.79% above the 20-day moving average of $180.17, while momentum is positive at 2.87% over five trading days and 2.56% over 20 trading days. Near-term support is $174.67, the 30-day low. Near-term resistance is $193.86, the 30-day high.


Recent News and Developments

DaVita brings seven studies to Kidney Week

DaVita said it will present seven studies at ASN Kidney Week 2026 covering expanded hemodialysis, home-based treatments and patient experience. The research includes GLP-1 exposure in peritoneal-dialysis patients and hospitalization rates after discharge. Source: DaVita Clinical Research

DaVita shares jump 4.68%

DVA closed at $189.16 on October 15, up 4.68% from its previous $180.70 close. The stock’s market value stood at $12.14 billion during the session. Source: Global Banking & Finance Review

Reimbursement pressure weighs on DaVita

Trefis reported on October 15 that DVA had fallen about 15% since June 30. It pointed to an estimated $40 million full-year reimbursement and commercial-mix headwind, along with major-shareholder selling, as key pressures. Source: Trefis


Market Sentiment and Analyst Recommendations

Bull Case
DaVita generated $14.01 billion in revenue and posted 5.2% revenue growth. The stock trades at 15.78 times earnings, while seven analysts rate it a buy. Their average target is $219.86, compared with the current price of $186.81. Near-term momentum is constructive, with the stock above its $180.17 moving average and gains over both the last five and 20 trading days. DaVita is also presenting seven studies at ASN Kidney Week 2026, covering expanded hemodialysis, home-based treatments and patient experience. That research includes GLP-1 exposure in peritoneal-dialysis patients and hospitalization rates after discharge. The case for buying DVA is straightforward: positive growth, a moderate earnings multiple, improving momentum and an analyst target above the current price.
Bear Case
DaVita carries $13.41 billion in total debt against just $688.88 million in cash. That balance-sheet gap is the clearest financial risk in the supplied data. The stock is also 24.44% below its 52-week high despite trading 85.15% above its low, showing how much volatility investors have absorbed. Trefis reported on October 15 that DVA had fallen about 15% since June 30. It cited an estimated $40 million full-year reimbursement and commercial-mix headwind, along with major-shareholder selling. The analyst target range runs from $165.00 to $270.00, so professional expectations are unusually wide. A break below $174.67 would weaken the near-term technical setup and put the $180.17 moving average firmly above the stock.
What to Watch
Watch whether DVA can clear the $193.86 near-term resistance level after closing at $189.16 on October 15. That session produced a 4.68% gain from the previous $180.70 close, but one strong day does not settle the trend. The first downside threshold is the $180.17 moving average, followed by support at $174.67. Investors should track whether revenue growth holds near the reported 5.2%. Reimbursement and commercial mix matter because the estimated full-year headwind is $40 million. ASN Kidney Week 2026 is the next identified research catalyst, with seven DaVita studies covering dialysis treatments and patient outcomes. A move through $193.86 would strengthen the bullish case, while a drop below $174.67 would undermine it.
Analyst Consensus
BUY

Based on 7 analyst opinions
Low Target
$165.00
Mean Target
$219.86
High Target
$270.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Care Facilities
Employees
78,000
Earnings & Dividends
Next Earnings
Oct 28, 2026
EPS (Trailing)
$11.84
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is DVA a good stock to buy?
Seven analysts rate DVA a buy, and their average target is $219.86 versus a current price of $186.81. The stock also trades 3.79% above its 20-day moving average, so the takeaway is that analyst sentiment and near-term momentum are positive.
What is DVA’s price target?
The average analyst target is $219.86, with estimates ranging from $165.00 to $270.00. The takeaway is that the consensus target sits above the current $186.81 price, but the wide range signals meaningful uncertainty.
Is DVA overvalued?
DVA trades at a P/E ratio of 15.78 and has a market capitalization of $11.92 billion. The supplied data does not establish whether that valuation is high or low relative to competitors, so the takeaway is that investors need a peer comparison before calling it overvalued.
What are DVA’s support and resistance levels?
Near-term support is $174.67, while near-term resistance is $193.86. The takeaway is that these are the key 30-day levels around the current $186.81 price.
Does DVA pay a dividend?
The supplied data does not include dividend or yield information. The takeaway is that no dividend conclusion can be made from the available figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.