ALTSTATION.IO

HCA Healthcare, Inc. (HCA) Stock Analysis

By Nova Skye | AltStation.io | Updated October 25, 2026

Price
$472.03
Change
+1.01%
Market Cap
$104.72B
Avg Volume
1.3M

Company Overview

Nashville-based HCA Healthcare operates as the largest for-profit health system in the United States, running 190 hospitals and over 2,500 outpatient care sites across 19 states and the United Kingdom. Positioned in the healthcare sector’s medical care facilities industry, the company delivers acute inpatient care, emergency room treatments, surgical procedures, and specialized diagnostics. Its end buyers are individual patients seeking medical treatment, with bills primarily funded by commercial insurance providers, Medicare, and Medicaid. Revenue flows directly from clinical procedure volumes, hospital bed occupancy, and ambulatory patient visits.

HCA is the undisputed market leader among facility operators, generating over $75 billion in annual revenue. Its primary competitive edge lies in clustering facilities across fast-growing Sunbelt markets like Texas and Florida, giving it immense leverage to negotiate favorable commercial insurance rates compared to smaller rivals like Tenet Healthcare. The persistent threats to its business are rising nurse labor expenses and exposure to fixed government reimbursement rates that lag clinical inflation. Even so, its massive scale across roughly 47 million annual patient encounters lets it absorb supply-chain and labor shocks far better than standalone regional hospitals.

Right now, HCA is in steady expansion mode, driving quarterly revenue past $20 billion in 2026 on strong inpatient admissions and procedural demand. Management is actively executing a strategic pivot to widen its outpatient footprint, targeting roughly 20 ambulatory and urgent care sites for every core acute-care hospital. This hub-and-spoke expansion captures high-margin surgical cases early and funnels complex care directly into HCA facilities, squeezing independent operators out of the market. HCA remains a dominant, disciplined cash generator that trades regulatory headaches for unmatched local pricing power.

Key Financials
Market Cap
$104.72B
Revenue
$78.01B
EBITDA
$15.75B
Gross Margin
42.6%
Profit Margin
8.8%
Revenue Growth
8.7%
Total Cash
$1.13B
Total Debt
$51.55B
Free Cash Flow
$3.74B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
15.82
Forward P/E
14.76
Beta
1.11
52-Week High
$556.52
52-Week Low
$353.99
EPS
$29.83
50-Day Avg
$430.37
200-Day Avg
$444.67
Price/Book
-15.49
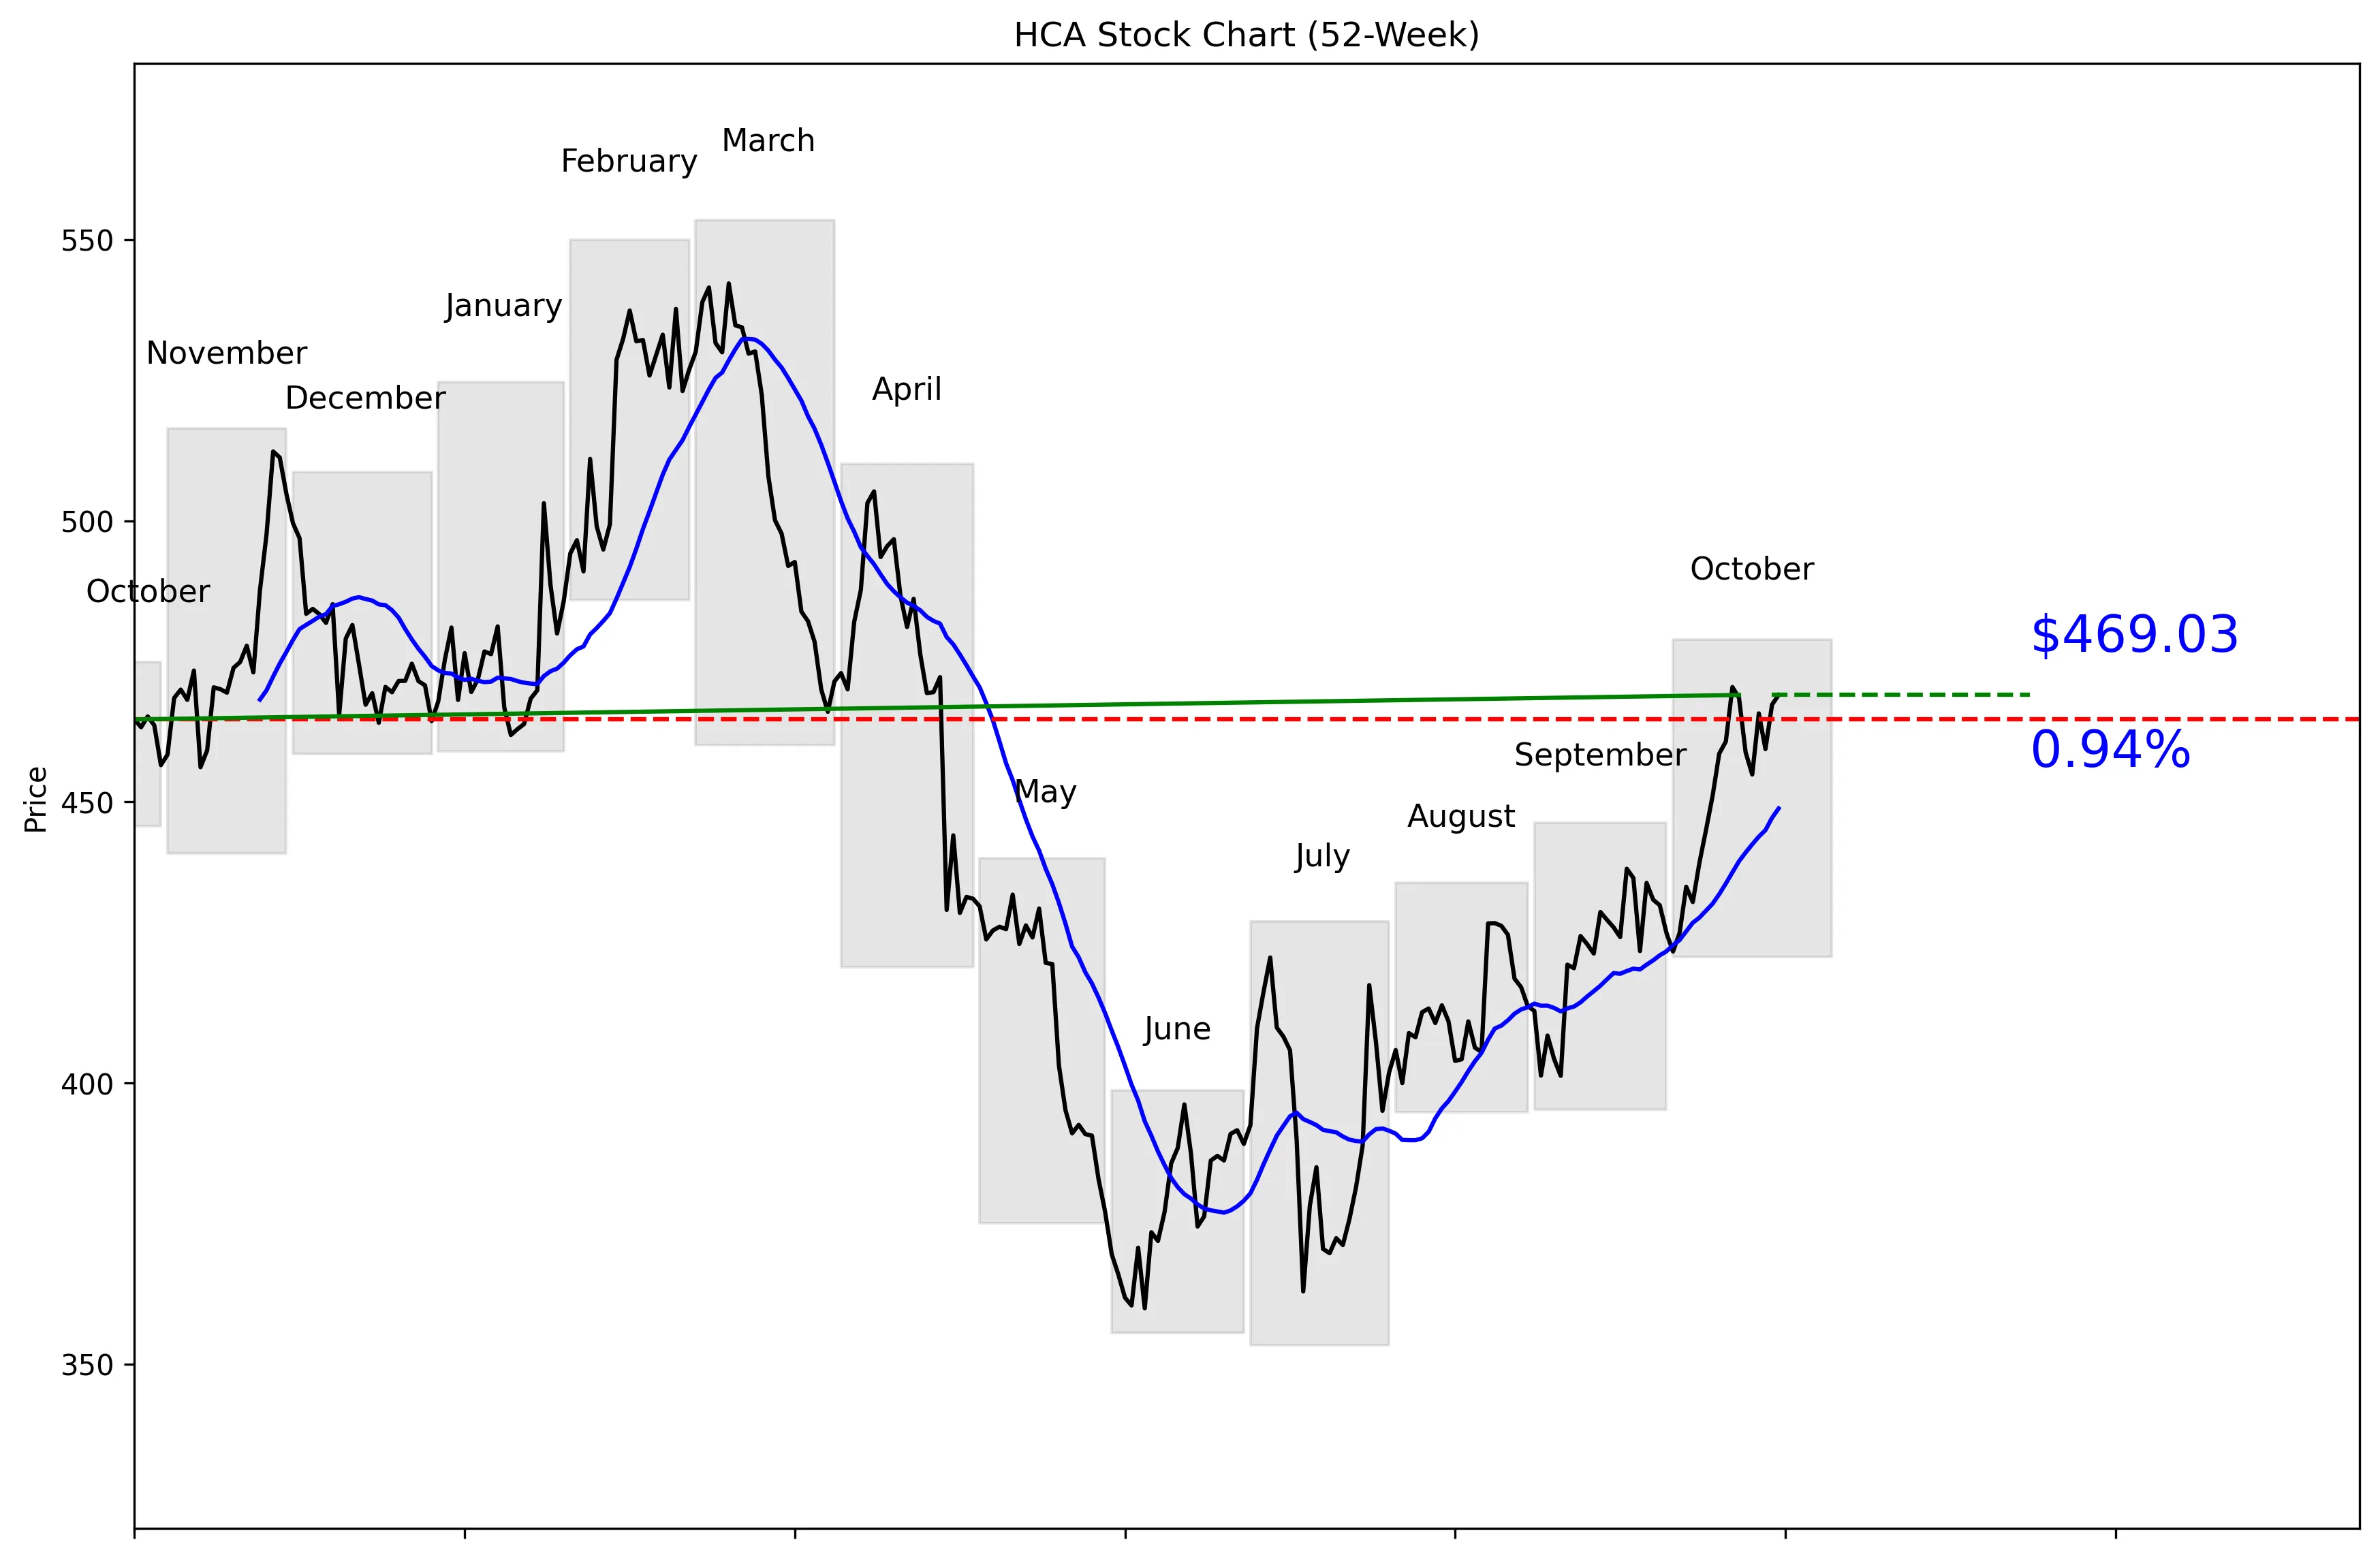
HCA 52-Week Stock Chart
Technical Analysis
HCA trades at $472.03, 58% of the way from its exact 52-week low of $353.34 to its exact high of $553.56. The stock is 15.27% below that high and 32.74% above the low. Price is 4.50% above the 20-day moving average of $448.85, backed by gains of 2.22% over five trading days and 7.67% over 20 trading days. Near-term support sits at the 30-day low of $423.04. HCA has moved above the stated 30-day resistance level of $470.44, making its ability to hold that breakout the immediate technical test.


Recent News and Developments

HCA challenges North Carolina’s authority in Mission Hospital case

HCA asked the court to dismiss North Carolina Attorney General Jeff Jackson’s lawsuit, arguing his office lacks constitutional or statutory authority to enforce the Mission Hospital purchase agreement. The lawsuit alleges HCA violated commitments to maintain emergency and oncology services after acquiring Mission Health in 2019. Source: North Carolina Health News

Wall Street expects lower third-quarter earnings

Zacks expects HCA to report third-quarter earnings of $6.75 per share, down 3% year over year, when results arrive October 27. Revenue is projected at $19.38 billion, up 1.1%, while equivalent admissions are expected to rise 1.7% and operating expenses 2%. Source: Zacks Equity Research

HCA shares gain 3.06% ahead of earnings

HCA closed at $469.45 on October 23, giving the stock a five-day gain of 3.06%. Shares rose 2.11% on October 20 and another 1.71% on October 22, despite falling 1.29% between those sessions. Source: MarketBeat


Market Sentiment and Analyst Recommendations

Bull Case
HCA is growing revenue by 8.7% from an already substantial $78.01 billion base. The stock trades at 15.82 times earnings, which is not an aggressive multiple for a company with positive revenue growth. Momentum is also working: shares gained 7.67% over the past 20 trading days and trade 4.50% above the 20-day moving average. Wall Street still rates HCA a buy based on recommendations from 22 analysts. The highest analyst target of $579.00 leaves room above the current $472.03 price. Projected third-quarter revenue of $19.38 billion, equivalent-admission growth of 1.7%, and a clean hold above $470.44 would strengthen the bull case.
Bear Case
The balance sheet is the clearest weakness, with $51.55 billion in debt against just $1.13 billion in cash. The consensus analyst target is $460.59, below the current price of $472.03. Wall Street expects third-quarter earnings of $6.75 per share, down 3% year over year, while projected revenue growth is only 1.1%. Expected operating-expense growth of 2% would exceed the projected revenue increase and could pressure profitability. The stock remains 15.27% below its exact 52-week high despite strong recent momentum. HCA also faces a lawsuit alleging that it violated commitments to maintain emergency and oncology services after acquiring Mission Health in 2019, creating legal and operational uncertainty.
What to Watch
Third-quarter results arrive October 27, with expected earnings of $6.75 per share and revenue of $19.38 billion. Investors should compare the reported figures with the projected 3% earnings decline and 1.1% revenue growth. Equivalent admissions are expected to increase 1.7%, so weaker volume would undermine the near-term growth case. Operating expenses are projected to rise 2%; costs growing faster than revenue would be a negative signal. On the chart, watch whether HCA can remain above the former 30-day resistance level of $470.44 and the 20-day moving average of $448.85. A move toward $423.04 would signal that the recent 7.67% 20-day advance is breaking down, while continued strength would put the $553.56 high back into focus. The Mission Hospital case also matters because HCA is challenging the North Carolina attorney general’s authority to enforce the 2019 purchase agreement.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$380.00
Mean Target
$460.59
High Target
$579.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Care Facilities
Employees
230,000
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$29.83
Dividend Yield
67.0%
Payout Ratio
10.1%

Frequently Asked Questions

Is HCA a good stock to buy?
HCA carries a buy recommendation from 22 analysts, has 8.7% revenue growth, and trades at a P/E of 15.82. The takeaway is that the operating and valuation data support the buy case, but the debt load deserves attention.
What is HCA’s price target?
The consensus analyst target is $460.59, with estimates ranging from $380.00 to $579.00. The takeaway is that the average target sits below the current $472.03 price, although analyst expectations vary widely.
Is HCA stock overvalued?
HCA trades at 15.82 times earnings and has a market capitalization of $104.72 billion. The takeaway is that the supplied valuation data do not show an extreme earnings multiple, but the consensus target of $460.59 is below the current price.
What are HCA’s support and resistance levels?
Near-term support is the 30-day low of $423.04, while the stated 30-day resistance level is $470.44. The takeaway is that the current $472.03 price is above resistance, so holding that level is the immediate test.
Does HCA pay a dividend?
The supplied data do not include a dividend amount, yield, or payment schedule. The takeaway is that no dividend conclusion can be made from the available information.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 25, 2026.