ALTSTATION.IO

QUALCOMM Incorporated (QCOM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 05, 2026

Price
$181.94
Change
-1.59%
Market Cap
$194.32B
Avg Volume
12.5M

Company Overview

Headquartered in San Diego, Qualcomm is a semiconductor powerhouse that designs the core chips, modems, and system software powering mobile phones, connected vehicles, and IoT hardware. The company makes money through two primary engines: selling physical silicon via its Qualcomm CDMA Technologies (QCT) division and collecting high-margin patent royalties through Qualcomm Technology Licensing (QTL). Global device makers, automakers, and government contractors purchase their integrated circuits, while virtually every 4G and 5G device manufacturer pays them licensing fees for standard-essential wireless patents. In fiscal 2024, total revenue reached $38.96 billion, with semiconductor sales generating $33.20 billion and licensing contributing $5.57 billion.

Qualcomm holds the dominant market leadership position in premium cellular modems and foundational wireless intellectual property. Its strongest moat is the QTL patent portfolio, which forces the entire mobile ecosystem to pay royalties regardless of whose silicon ends up inside the handset. The biggest structural threat remains customer insourcing, led by Apple’s push to develop internal modems, alongside cost-driven competition from MediaTek in mid-tier Android devices. Qualcomm still maintains a decisive technical lead over rivals in top-tier modem performance and integrated digital cockpit systems for cars.

The business is in a clear growth phase, posting 9% top-line revenue expansion in fiscal 2024 compared to $35.82 billion in fiscal 2023. Management is executing an aggressive diversification pivot to reduce reliance on the smartphone upgrade cycle, reallocating engineering muscle into automotive telematics, automated driving platforms, and edge IoT devices. That strategy is already paying off, driving a 9% year-over-year increase in QCT segment sales and delivering record automotive revenue in fiscal 2024. Qualcomm is successfully transforming from a pure mobile chip supplier into a diversified edge-compute standard.

Key Financials
Market Cap
$194.32B
Revenue
$44.07B
EBITDA
$12.00B
Gross Margin
54.2%
Profit Margin
21.0%
Revenue Growth
-4.0%
Total Cash
$8.30B
Total Debt
$15.27B
Free Cash Flow
$10.24B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
21.06
Forward P/E
17.83
Beta
1.65
52-Week High
$259.92
52-Week Low
$121.99
EPS
$8.64
50-Day Avg
$171.45
200-Day Avg
$169.26
Price/Book
6.95
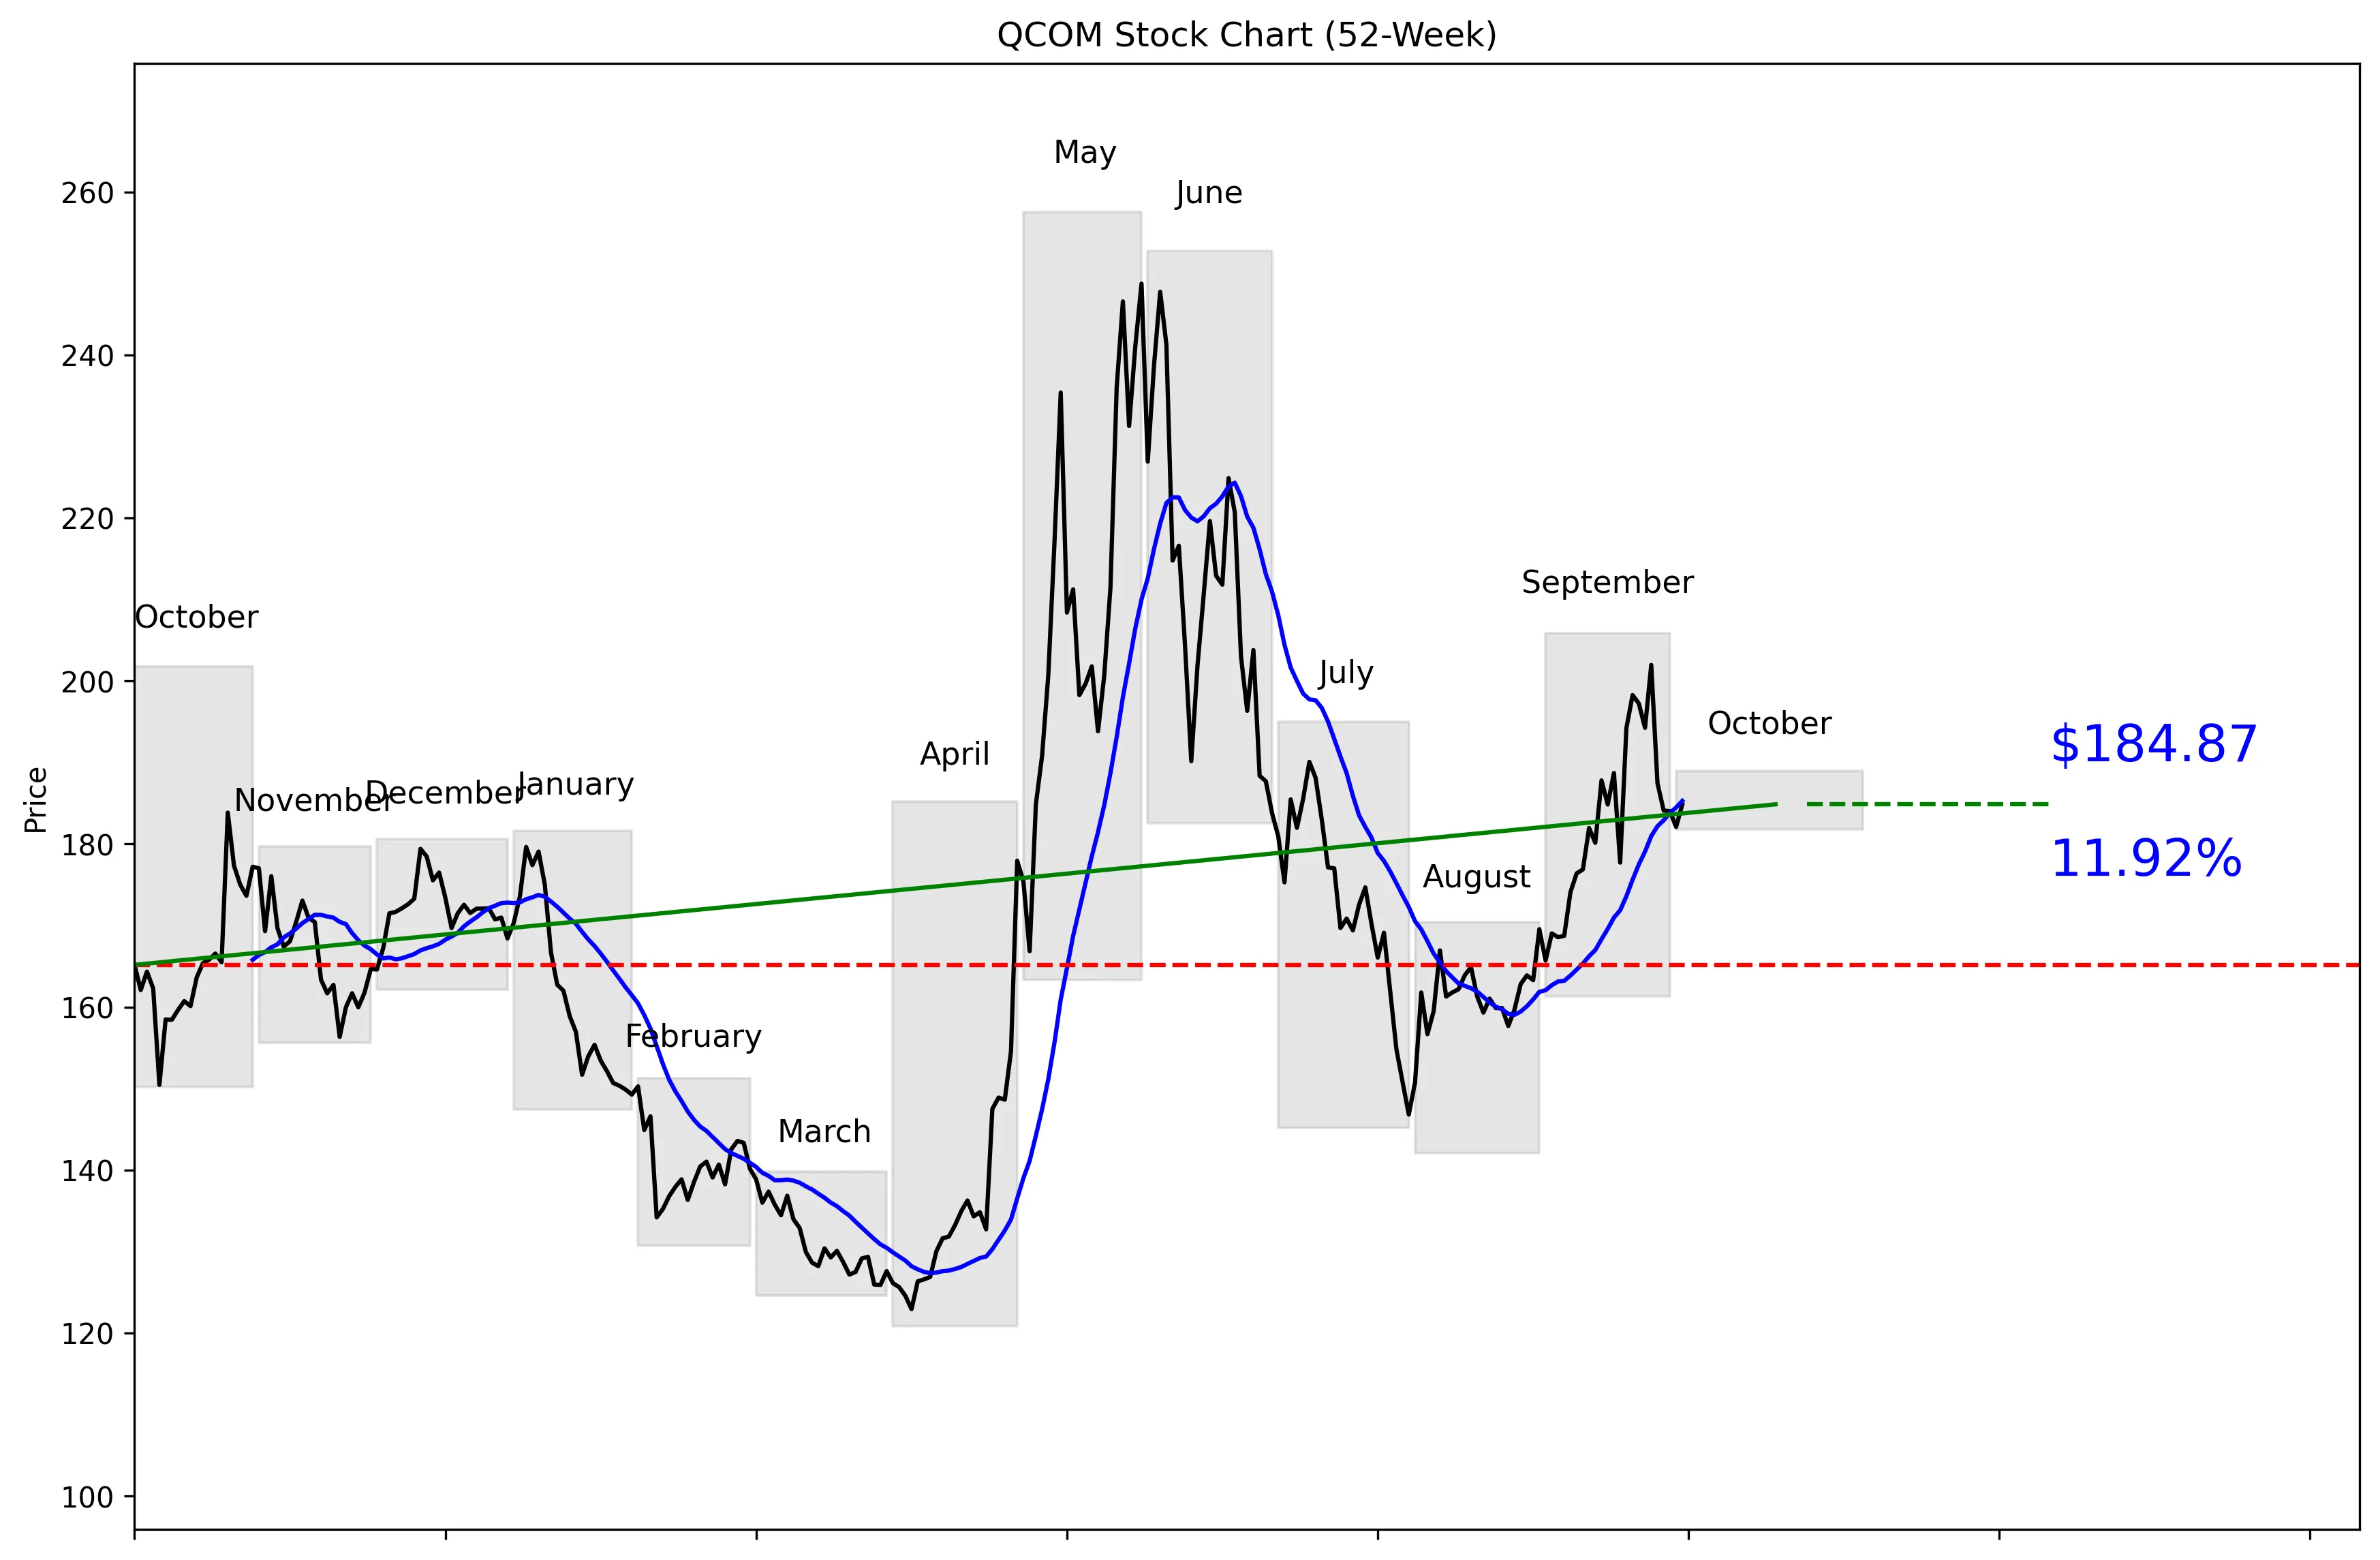
QCOM 52-Week Stock Chart
Technical Analysis
QCOM trades at $181.94, 28.22% below its $257.56 52-week high and 52.93% above its $120.88 low. The stock sits 47% of the way from that low to that high, placing it near the middle of its annual range. Price is 0.23% below the 20-day moving average of $185.29. Momentum is mixed: QCOM gained 9.67% over the last 20 trading days but lost 8.47% over the last five. Near-term support is $157.67, while resistance is $201.97.


Recent News and Developments

Qualcomm and Huawei sign broad patent deal

Qualcomm and Huawei agreed to a multi-year patent cross-license covering 5G, AI, computing and networking. Qualcomm will also purchase certain Huawei U.S. patents, with closing subject to regulatory approval. Source: Qualcomm

QCOM drops 7.17% as its September rally breaks

Qualcomm fell $14.49 to $187.48 on September 28, sharply underperforming a roughly 1% decline in the QQQ. The selloff followed a strong run driven by Qualcomm’s Snapdragon Summit, renewed Apple license and Amazon Web Services collaboration, with fading momentum and unresolved Samsung foundry talks weighing on shares. Source: Yahoo Finance

Qualcomm rebounds 1.53% but remains below $185

QCOM closed at $184.87 on October 2, gaining 1.53% while the S&P 500 rose 0.73%. The rebound was not enough to erase the September 28 selloff, leaving the stock $17.10 below its September 25 close. Source: Zacks Equity Research


Market Sentiment and Analyst Recommendations

Bull Case
Qualcomm generates $44.07 billion in revenue and carries a $194.32 billion market cap. The stock trades at 21.06 times earnings, which gives investors real profits to value rather than a story built only on expectations. The $194.13 analyst target sits above the current price of $181.94. QCOM remains 28.22% below its 52-week high, leaving room for recovery if momentum improves. Qualcomm’s multi-year Huawei patent cross-license covers 5G, AI, computing, and networking, while the planned purchase of certain Huawei U.S. patents could strengthen its intellectual-property position if approved. The buy case is straightforward: profitable scale, broad patent exposure, and a current price below both the analyst target and recent resistance.
Bear Case
Revenue growth is negative 4.0%, which is the clearest problem in the current data. Total debt of $15.27 billion exceeds total cash of $8.30 billion by $6.97 billion. The 21.06 P/E is harder to defend while revenue is shrinking. Analysts rate QCOM a hold, and the target range of $100.00 to $400.00 shows unusually wide disagreement about its value. The stock lost 8.47% over the last five trading days after falling 7.17% on September 28. QCOM is also below its $185.29 moving average, so buyers do not yet have a clean technical recovery.
What to Watch
First, watch whether QCOM can reclaim its $185.29 20-day moving average after the 8.47% five-day decline. A move through the $201.97 30-day high would strengthen the recovery case, while a drop toward $157.67 would put near-term support under pressure. Investors should track whether the Huawei patent agreement receives regulatory approval and whether the planned U.S. patent purchase closes. The September 28 decline to $187.48 and the October 2 close at $184.87 show that the stock has not fully recovered from its recent selloff. Revenue growth needs to improve from negative 4.0% for the valuation case to become more convincing. The next quarter should clarify whether the 9.67% 20-day momentum can reassert itself or whether the weaker five-day trend is taking control.
Analyst Consensus
HOLD

Based on 30 analyst opinions
Low Target
$100.00
Mean Target
$194.13
High Target
$400.00


Earnings and Financial Data

Sector
Technology
Industry
Semiconductors
Employees
52,000
Earnings & Dividends
Next Earnings
Nov 04, 2026
EPS (Trailing)
$8.64
Dividend Yield
199.0%
Payout Ratio
41.5%

Frequently Asked Questions

Is QCOM a good stock to buy?
QCOM trades at $181.94 with a 21.06 P/E, negative 4.0% revenue growth, and a hold recommendation from 30 analysts. The takeaway is that the current data supports patience more than an aggressive buy.
What is QCOM’s analyst price target?
The analyst target is $194.13, with estimates ranging from $100.00 to $400.00. The takeaway is that the average target is above the current $181.94 price, but analyst expectations vary widely.
Is QCOM undervalued?
QCOM is 28.22% below its $257.56 52-week high and trades at 21.06 times earnings. The takeaway is that the stock is well below its high, but negative 4.0% revenue growth prevents a clear undervaluation call.
What are QCOM’s support and resistance levels?
Near-term support is $157.67, and near-term resistance is $201.97. The takeaway is that these are the key 30-day levels to monitor around the current $181.94 price.
Does QCOM pay a dividend?
The supplied data does not include dividend information. The takeaway is that no dividend conclusion can be made from these figures alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 05, 2026.