ALTSTATION.IO

Williams-Sonoma, Inc. (WSM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 13, 2026

Price
$239.16
Change
+0.13%
Market Cap
$28.17B
Avg Volume
1.1M

Company Overview

Founded in 1956 and headquartered in San Francisco, Williams-Sonoma operates in the Specialty Retail industry within the Consumer Cyclical sector. The company sells premium home furnishings, cookware, cutlery, furniture, and home decor to middle- and upper-income consumers across the United States and internationally. Its core brand lineup includes Williams Sonoma, Pottery Barn, West Elm, Rejuvenation, Mark and Graham, and GreenRow. It reaches customers through a synchronized omni-channel setup combining e-commerce platforms, direct-mail catalogs, and physical retail stores.

Williams-Sonoma is an established market leader in the premium home retail space, not a niche player. Its main operational edge comes from being a true digital-first operator, generating roughly 65% to 70% of total revenue online while leveraging more than 600 retail stores as design showrooms and local fulfillment centers. That multi-brand ecosystem allows it to capture customers across life stages, from Pottery Barn Kids to West Elm. The primary threat is macro cyclicality, as high interest rates and housing market slowdowns directly squeeze discretionary home spending.

The company is currently focused on operational efficiency and margin defense rather than aggressive footprint expansion. Instead of discounting heavily during retail slowdowns, management has maintained pricing discipline, optimized supply chain automation, and leaned into high-margin e-commerce fulfillment. That strategy keeps operating margins resilient compared to traditional retail peers. For traders, the takeaway is straightforward: Williams-Sonoma is a disciplined cash generator, but top-line growth remains tightly tied to a rebound in housing turnover.

Key Financials
Market Cap
$28.17B
Revenue
$8.01B
EBITDA
$1.66B
Gross Margin
45.7%
Profit Margin
14.7%
Revenue Growth
6.7%
Total Cash
$1.03B
Total Debt
$1.53B
Free Cash Flow
$1.07B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
24.53
Forward P/E
22.75
Beta
1.47
52-Week High
$254.89
52-Week Low
$165.51
EPS
$9.75
50-Day Avg
$234.61
200-Day Avg
$210.40
Price/Book
13.16
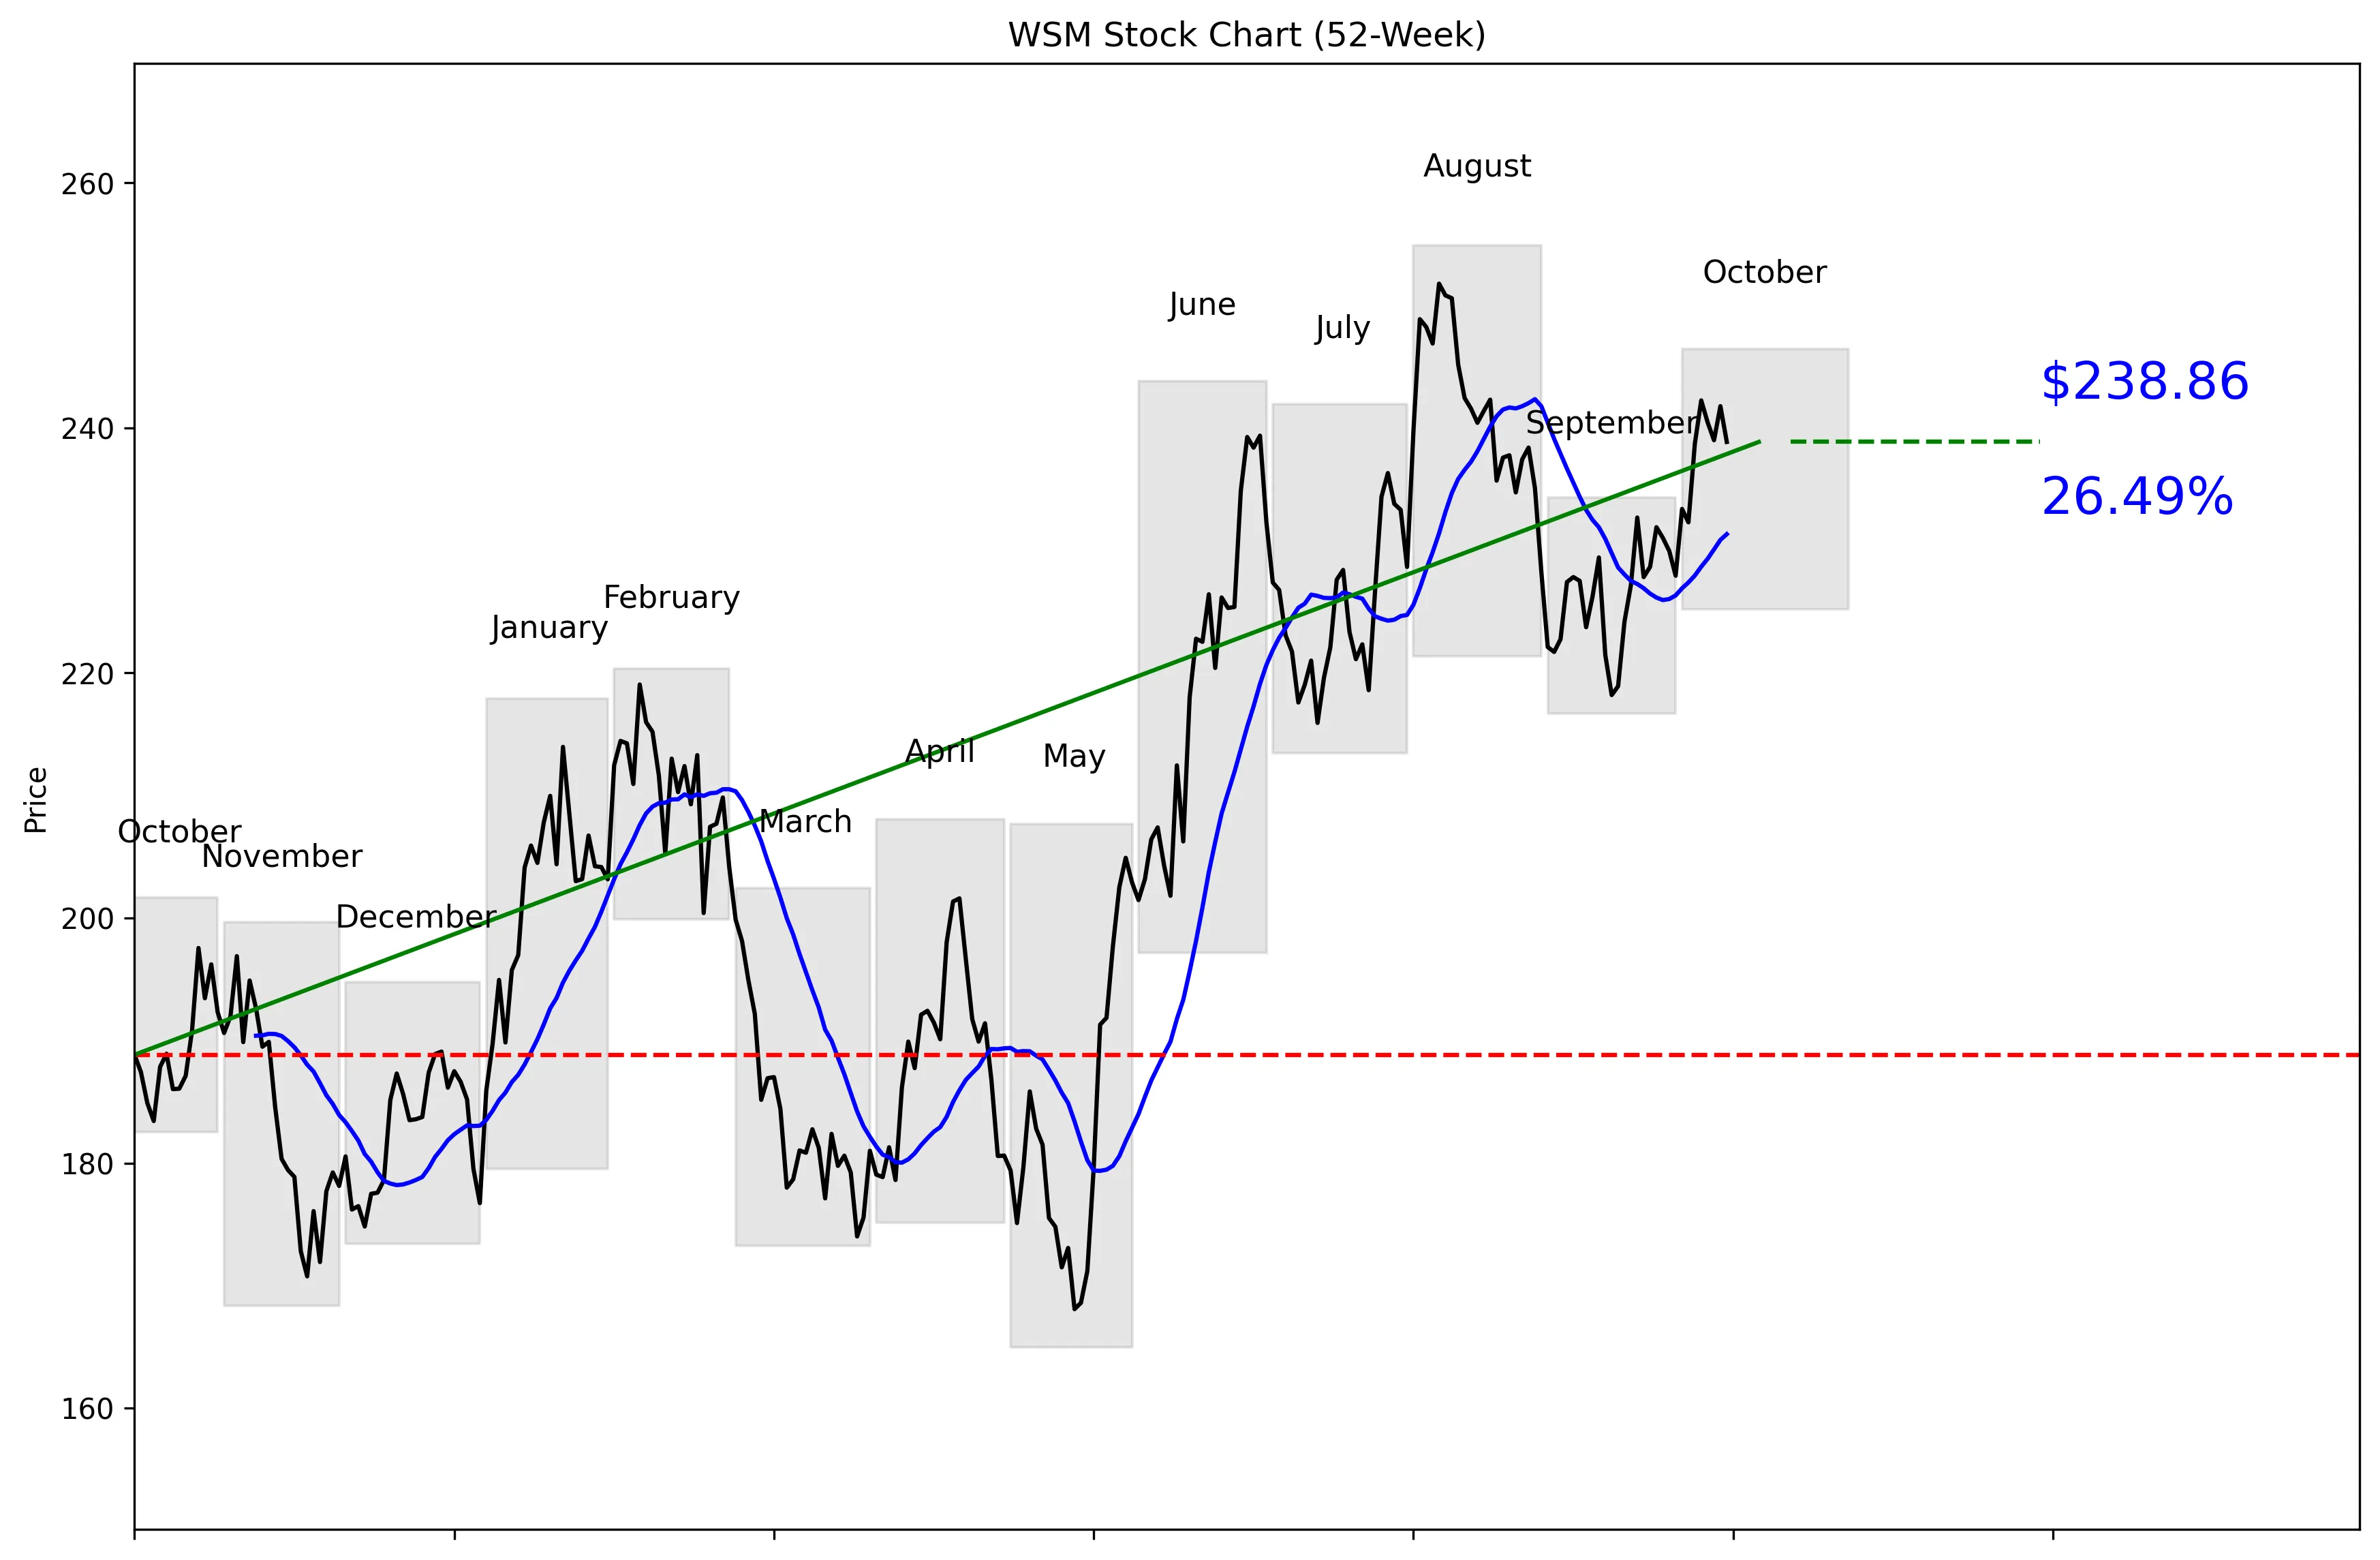
WSM 52-Week Stock Chart
Technical Analysis
WSM trades at $239.16, 82% of the way from its $164.96 52-week low to its $254.89 high. The stock is 6.29% below that high and 44.80% above the low, confirming a strong 52-week trend. Price sits 3.25% above the 20-day moving average of $231.34. Momentum is nearly flat over five trading days at 0.07%, but remains positive over 20 trading days at 4.11%. Near-term support is $218.20, while $242.25 is the resistance level buyers need to clear.


Recent News and Developments

UBS holds Neutral rating and $247 target

UBS reiterated its Neutral rating on Williams-Sonoma on October 12 with a $247 price target after meetings with the company’s CFO, CAO and investor relations team. The firm cited market-share gains and disciplined execution but flagged weak housing activity, elevated interest rates and cautious consumers. Source: Investing.com

Williams-Sonoma executive sells 522 shares

Chief Talent Officer Karalyn Yearout sold 522 WSM shares on October 9 at $239.36 each, a transaction worth $124,946. The filing reported that she retained 19,673 shares after the sale. Source: Finviz

WSM gains 1.16% and beats the major indexes

Williams-Sonoma closed at $241.78 on October 9, up 1.16% for the session versus gains of 0.60% for the S&P 500, 0.83% for the Dow and 0.64% for the Nasdaq. WSM had gained 6.82% over the preceding month, but its 25.14 forward P/E remained well above the home-furnishings industry’s 16.57. Source: Zacks Investment Research


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 6.7%, and earnings expectations are moving higher. The quarterly consensus estimate is $2.16 per share, representing 10.2% year-over-year growth, while the $9.51 full-year estimate implies 7.6% growth. Williams-Sonoma is also gaining market share while maintaining disciplined execution, according to UBS. The company’s Olive and Otto AI shopping assistants reportedly increased customer engagement by 700% and related revenue by 620%. Analysts collectively rate WSM a buy, with a $246.35 target and a high-end estimate of $280.00. The buy case is straightforward: earnings growth, market-share gains and digital engagement could push the stock through $242.25 and back toward its $254.89 high.
Bear Case
WSM is not cheap at 24.53 times earnings. Its reported 25.14 forward P/E also sits well above the home-furnishings industry’s 16.57, leaving little room for disappointment. UBS remains Neutral with a $247 target because weak housing activity, elevated interest rates and cautious consumers still threaten demand. The consensus target of $246.35 is only modestly above the current $239.16 price. Total debt of $1.53 billion exceeds total cash of $1.03 billion. With the stock already 82% through its 52-week range, slower growth or weaker execution could send it back toward the $231.34 moving average or $218.20 support.
What to Watch
The next quarterly earnings report needs to support the $2.16-per-share consensus estimate and its expected 10.2% year-over-year growth. Investors should also track whether the $9.51 full-year estimate continues rising after moving higher during the past 30 days. Revenue growth must hold near or above the reported 6.7% rate to justify the current 24.53 P/E. On the chart, a sustained break above $242.25 would strengthen the case for another test of $254.89. A drop below the $231.34 moving average would weaken momentum, while a break under $218.20 would damage the near-term setup. The broader thesis improves if market-share gains continue despite weak housing activity, elevated interest rates and cautious consumers; it weakens if those pressures slow earnings or revenue growth.
Analyst Consensus
BUY

Based on 20 analyst opinions
Low Target
$151.00
Mean Target
$246.35
High Target
$280.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Specialty Retail
Employees
19,800
Earnings & Dividends
Next Earnings
Nov 18, 2026
EPS (Trailing)
$9.75
Dividend Yield
127.0%
Payout Ratio
29.1%

Frequently Asked Questions

Is WSM a good stock to buy?
The analyst recommendation is buy based on 20 analysts, while revenue is growing 6.7%. The takeaway is that analysts are positive, but the 24.53 P/E means investors are paying for continued growth.
What is WSM’s price target?
The analyst target is $246.35, with estimates ranging from $151.00 to $280.00. The takeaway is that expectations vary widely around the current $239.16 price.
What are WSM’s support and resistance levels?
Near-term support is $218.20, and near-term resistance is $242.25. The takeaway is that $242.25 is the immediate level WSM must clear.
How close is WSM to its 52-week high?
WSM is 6.29% below its $254.89 52-week high and 44.80% above its $164.96 low. The takeaway is that the stock is trading near the upper end of its yearly range.
How strong is WSM financially?
Williams-Sonoma has $8.01 billion in revenue, $1.03 billion in cash and $1.53 billion in debt. The takeaway is that the company generates substantial revenue, but debt exceeds cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 13, 2026.