ALTSTATION.IO

Yum! Brands, Inc. (YUM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 21, 2026

Price
$150.69
Change
-0.60%
Market Cap
$41.12B
Avg Volume
2.4M

Company Overview

Yum! Brands is a global fast-food operator headquartered in Louisville, United States, operating in the Consumer Cyclical restaurant sector. The company develops, operates, and franchises quick-service restaurants across four divisions: KFC, Taco Bell, Pizza Hut, and Habit Burger & Grill. They sell mass-market staples including fried chicken, Mexican-style food, pizza, and made-to-order chargrilled burgers to everyday consumers across more than 155 countries. Roughly 98% of their 61,000 restaurants are run by independent franchisees, creating an asset-light cash engine powered by franchise royalties and fees rather than company-owned restaurant overhead.

Yum! is an undisputed market leader in fast food, backed by a global footprint second only to McDonald’s. Its clear competitive edge is category diversification, allowing strength in Mexican food and fried chicken to balance out softness in any single dining segment. Taco Bell provides high-margin domestic dominance, while KFC acts as the core engine for international growth. The biggest risk on the horizon is aggressive value discounting from rivals like McDonald’s and Wendy’s, which threatens store traffic as budget-conscious diners pull back on spending.

The company is firmly in expansion mode, opening 4,535 new stores in 2024 to push annual revenue to $7.55 billion. Digital ordering has become their biggest operational win, with digital channels generating over $30 billion and accounting for more than 50% of total system sales. KFC and Taco Bell drive the machine, pulling in $3.54 billion and $3.10 billion in 2024 revenue, while scaling Habit Burger and stabilizing Pizza Hut remain ongoing execution hurdles. The bottom line is that Yum! is a resilient royalty machine built to compound through aggressive worldwide unit growth rather than relying on same-store customer spikes.

Key Financials
Market Cap
$41.12B
Revenue
$8.72B
EBITDA
$3.07B
Gross Margin
45.3%
Profit Margin
25.4%
Revenue Growth
12.2%
Total Cash
$683.00M
Total Debt
$13.41B
Free Cash Flow
$833.25M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
18.98
Forward P/E
22.03
Beta
0.55
52-Week High
$170.14
52-Week Low
$134.26
EPS
$7.94
50-Day Avg
$145.50
200-Day Avg
$153.54
Price/Book
-5.79
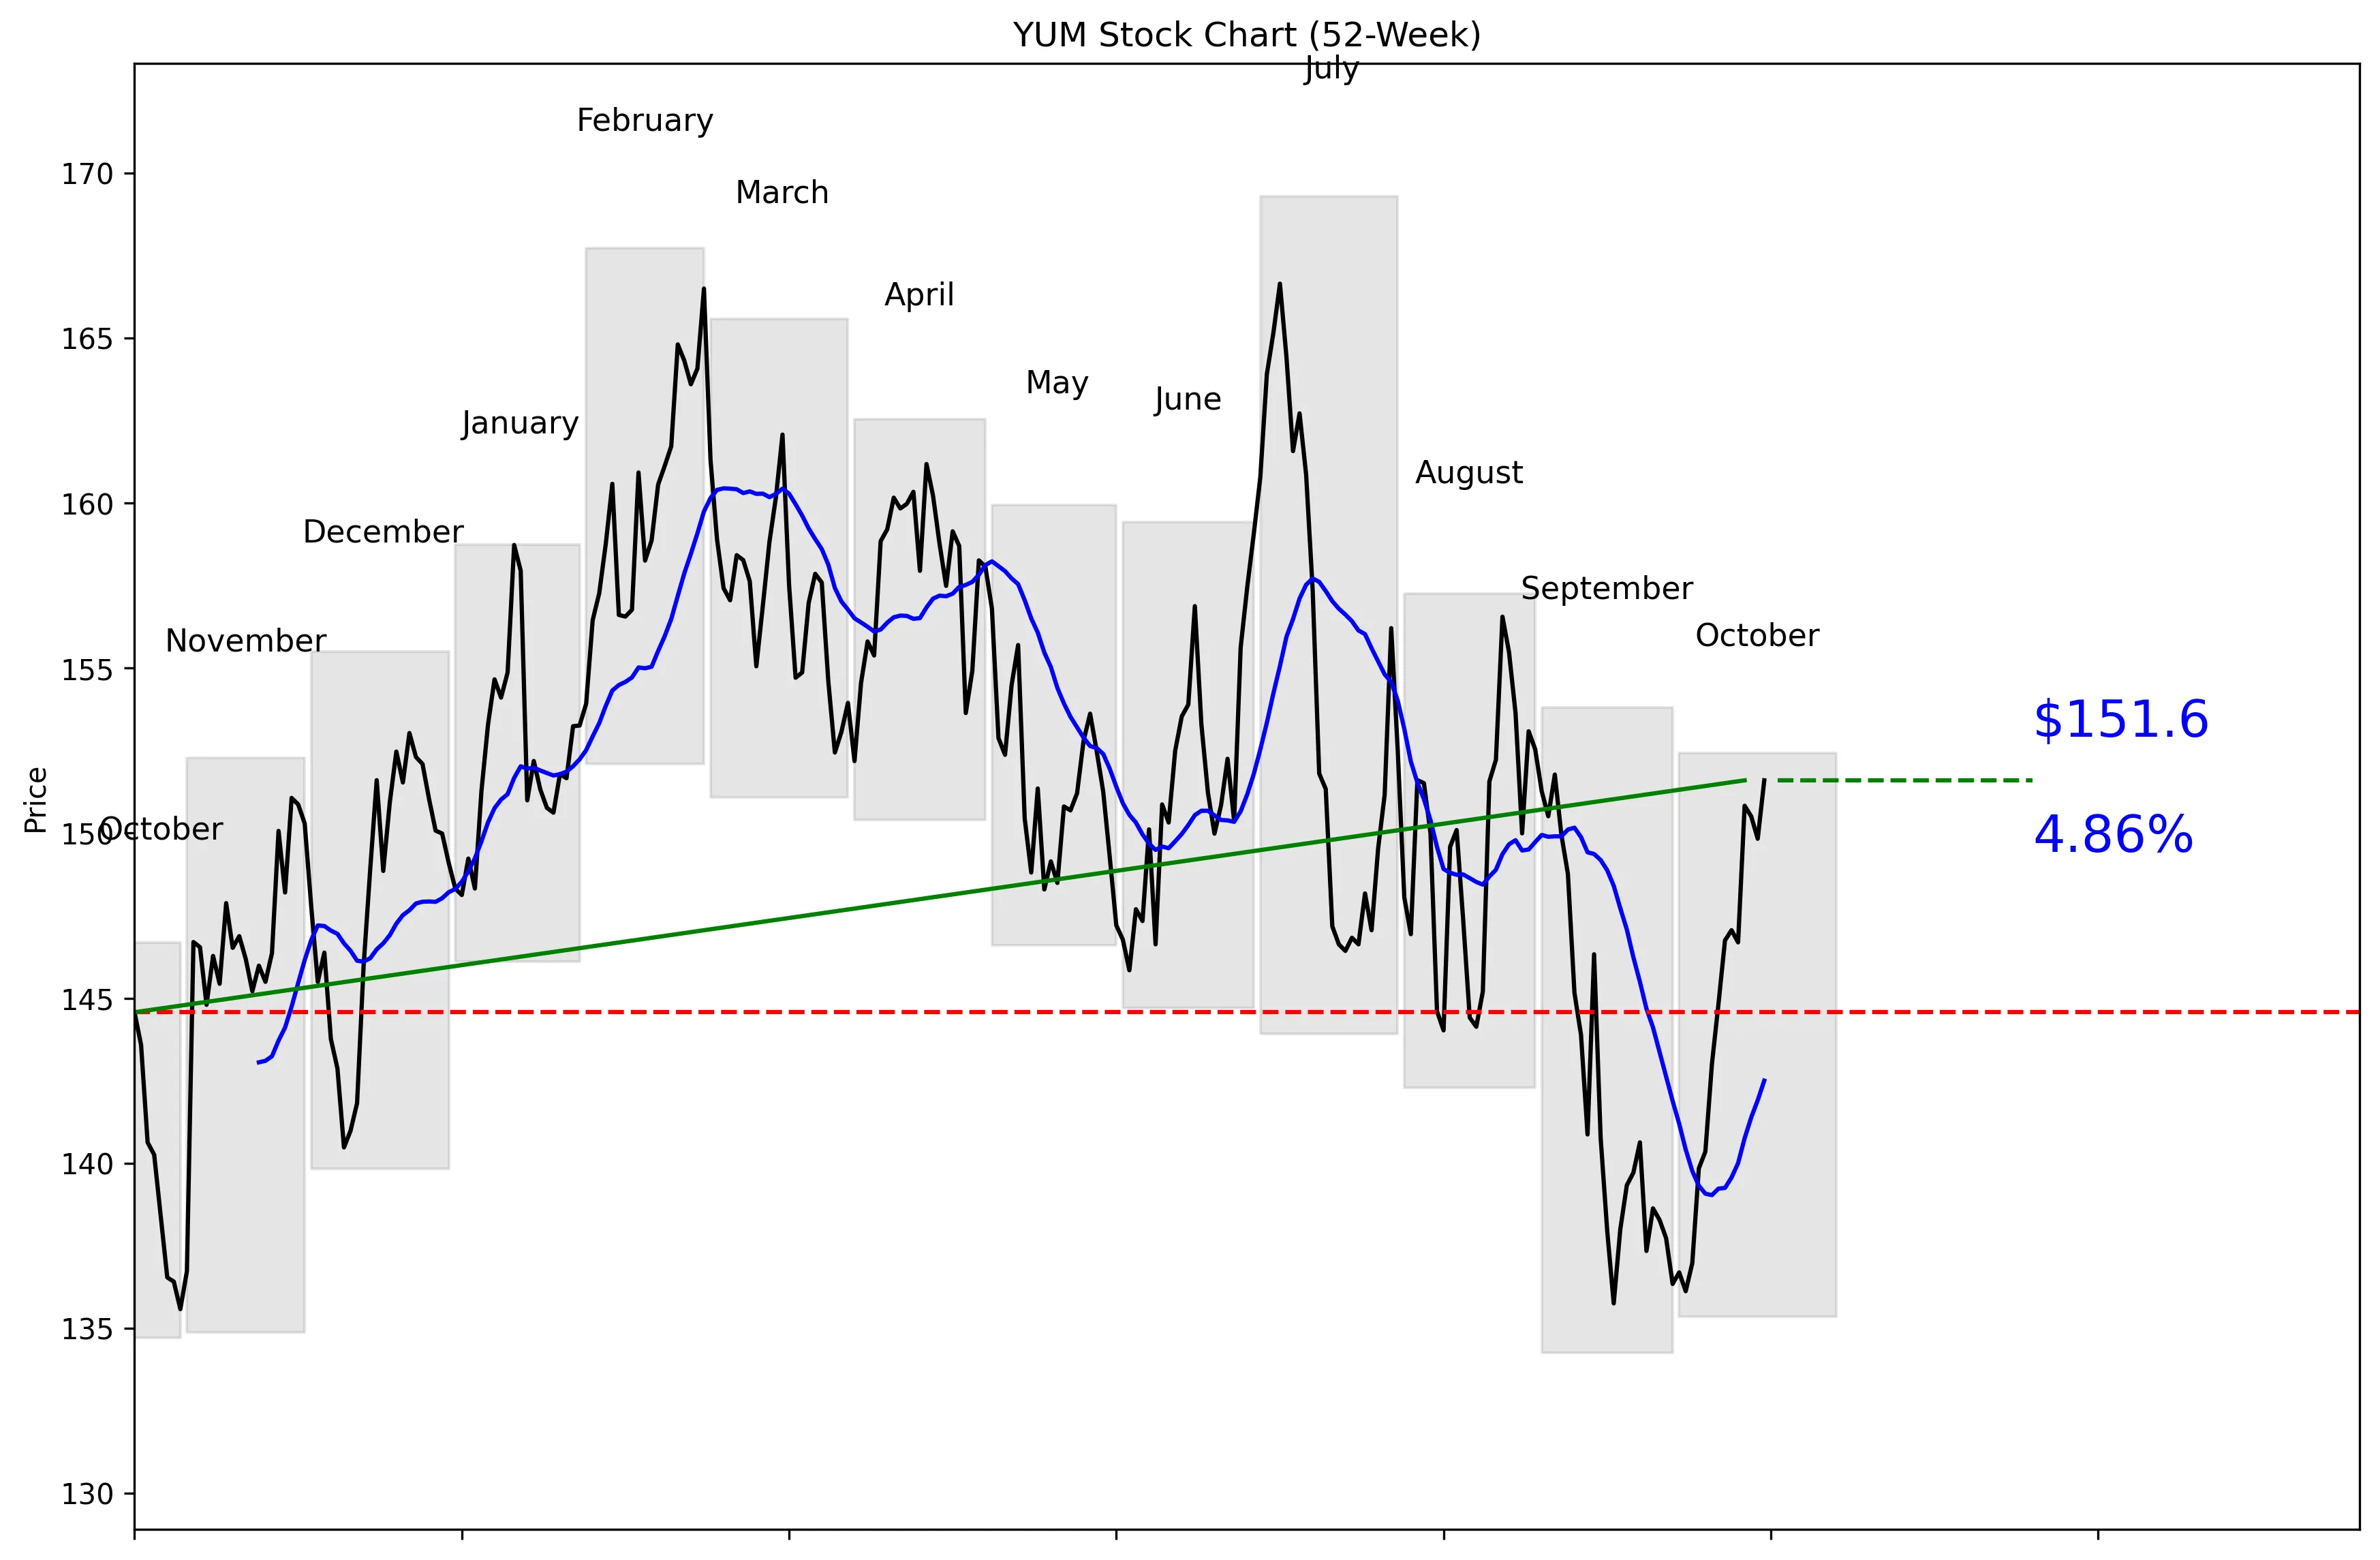
YUM 52-Week Stock Chart
Technical Analysis
YUM trades at $150.69, halfway between its $134.26 52-week low and $169.29 52-week high. The stock is 10.45% below that high and 12.92% above the low. Price sits 6.39% above the 20-day moving average of $142.50, backed by gains of 3.09% over five trading days and 8.51% over 20 trading days. Near-term support is the 30-day low of $135.75. Near-term resistance is the 30-day high of $151.60, putting the stock close to a level that momentum buyers need to break.


Recent News and Developments

Analysts split as targets reset before earnings

Deutsche Bank cut its YUM price target from $174 to $167 and kept a Hold rating, while Citi lowered its target from $176 to $163 with a Hold. Wells Fargo maintained a Buy rating with a $175 target. Source: TipRanks

Yum schedules third-quarter earnings for November 3

Yum! Brands will release third-quarter 2026 results at 7:00 a.m. ET on November 3. Management’s conference call starts at 8:15 a.m. ET. Source: Business Wire

YUM gains 3.09% in five trading days

YUM closed at $151.60 on October 20, up $1.77 or 1.18% for the session. The stock gained 3.09% over five days and 9.86% over one month. Source: Yahoo Finance


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 12.2%, giving investors a concrete reason to consider YUM beyond its brand portfolio. The stock trades at 18.98 times earnings, while the average analyst target of $170.47 sits above the current $150.69 price. Wall Street’s recommendation is buy based on 22 analysts, with targets reaching as high as $200.00. Momentum is also working: YUM is 6.39% above its 20-day moving average and has gained 8.51% over 20 trading days. The November 3 earnings report gives the stock a near-term catalyst if operating results support the growth story. Taco Bell’s Live Más Café expansion and four new horchata products add another potential traffic driver, while KFC’s U.S. switch to Coca-Cola products begins in January 2027. The bull case is straightforward: solid revenue growth, positive momentum and analyst upside at a P/E below 19.
Bear Case
YUM carries $13.41 billion in total debt against just $683.00 million in cash. That balance-sheet gap is the clearest financial risk in the supplied data. The stock is also pressing against near-term resistance at $151.60 after gaining 8.51% over 20 trading days, so expectations have already moved higher. Analyst conviction is not uniform: Deutsche Bank cut its target from $174 to $167, and Citi lowered its target from $176 to $163; both retained Hold ratings. The analyst target range starts at $147.00, below the current $150.69 price. A weak earnings report on November 3 could send the stock back toward its $142.50 moving average or $135.75 near-term support, though those levels are technical markers rather than forecasts. YUM needs to prove that 12.2% revenue growth can continue while managing a heavily debt-loaded balance sheet.
What to Watch
Third-quarter 2026 results arrive at 7:00 a.m. ET on November 3, followed by management’s call at 8:15 a.m. ET. The first question is whether the results support the reported 12.2% revenue growth rate. Investors should also watch whether the stock clears the $151.60 30-day high or loses momentum toward the $142.50 20-day moving average. A drop through $135.75 would break the stated near-term support level and materially weaken the chart. Analyst revisions after earnings matter because current views range from $147.00 to $200.00, with an average target of $170.47. Operationally, Taco Bell’s Live Más Café expansion and four horchata launches should be monitored as potential traffic drivers. KFC’s Coca-Cola transition begins in January 2027, so management’s comments on timing and execution could shape expectations for the next quarter.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$147.00
Mean Target
$170.47
High Target
$200.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Restaurants
Employees
49,000
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$7.94
Dividend Yield
198.0%
Payout Ratio
36.8%

Frequently Asked Questions

Is YUM a good stock to buy?
The stated recommendation is buy based on 22 analysts, and revenue growth is 12.2%. The clear takeaway is that analyst sentiment and growth favor buyers, but the $13.41 billion debt load remains a major risk.
What is YUM’s price target?
The average analyst target is $170.47, with estimates ranging from $147.00 to $200.00. The takeaway is that the consensus target sits above the current $150.69 price, but the lowest target sits below it.
What is YUM’s P/E ratio?
YUM trades at a P/E ratio of 18.98. The takeaway is that investors are paying 18.98 times reported earnings at the current valuation.
What are YUM’s support and resistance levels?
Near-term support is $135.75, while near-term resistance is $151.60. The takeaway is that YUM is trading close to resistance at its current $150.69 price.
How strong is YUM’s recent momentum?
YUM gained 3.09% over the last five trading days and 8.51% over the last 20 trading days. The stock is also 6.39% above its $142.50 20-day moving average, so the takeaway is that near-term momentum is positive.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 21, 2026.