ALTSTATION.IO

Darden Restaurants, Inc. (DRI) Stock Analysis

By Nova Skye | AltStation.io | Updated October 17, 2026

Price
$216.06
Change
+0.82%
Market Cap
$24.45B
Avg Volume
1.2M

Company Overview

Darden Restaurants is the largest full-service restaurant company in North America, operating more than 2,200 locations across the United States and Canada. Headquartered in Orlando, Florida, the company operates in the Consumer Cyclical sector, specifically within the restaurant industry. Their business is selling meals and beverages to retail diners across brands like Olive Garden, LongHorn Steakhouse, Cheddar’s Scratch Kitchen, and fine-dining spots like The Capital Grille and Ruth’s Chris Steak House. Founded in 1938, Darden captures a wide demographic, catering to value-focused family dinners on one end and high-ticket corporate dining on the other to generate over $13 billion in annual sales.

Darden is the clear market leader in the casual dining category, holding a massive supply chain and marketing advantage over competitors like Texas Roadhouse, Bloomin’ Brands, and Brinker International. Its primary edge is operational scale, which lets flagships like Olive Garden negotiate cheaper food costs and run national ad campaigns that regional and independent restaurants cannot match. The biggest ongoing threat is consumer spending fatigue, where inflation pushes middle-income diners to cut back on sit-down meals or trade down to fast-food chains. That said, Darden’s balance across casual dining and high-end steakhouses shields it better against economic downturns than single-concept restaurant peers.

The company is currently in expansion mode, growing total revenue by opening new locations and acquiring proven regional chains. Darden bolstered its fine-dining division by acquiring Ruth’s Chris Steak House in June 2023 and added Tex-Mex concept Chuy’s in October 2024 for roughly $605 million. Instead of panicking with margin-killing discounts when foot traffic slows, management has protected its bottom line by focusing on labor efficiency and steady menu pricing. Darden is using its scale to systematically take market share from struggling independent operators, cementing its position as the top operator in the restaurant space.

Key Financials
Market Cap
$24.45B
Revenue
$13.37B
EBITDA
$2.14B
Gross Margin
21.7%
Profit Margin
8.8%
Revenue Growth
5.1%
Total Cash
$220.50M
Total Debt
$8.59B
Free Cash Flow
$794.79M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
20.98
Forward P/E
17.42
Beta
0.62
52-Week High
$229.76
52-Week Low
$169.00
EPS
$10.30
50-Day Avg
$211.42
200-Day Avg
$204.71
Price/Book
11.84
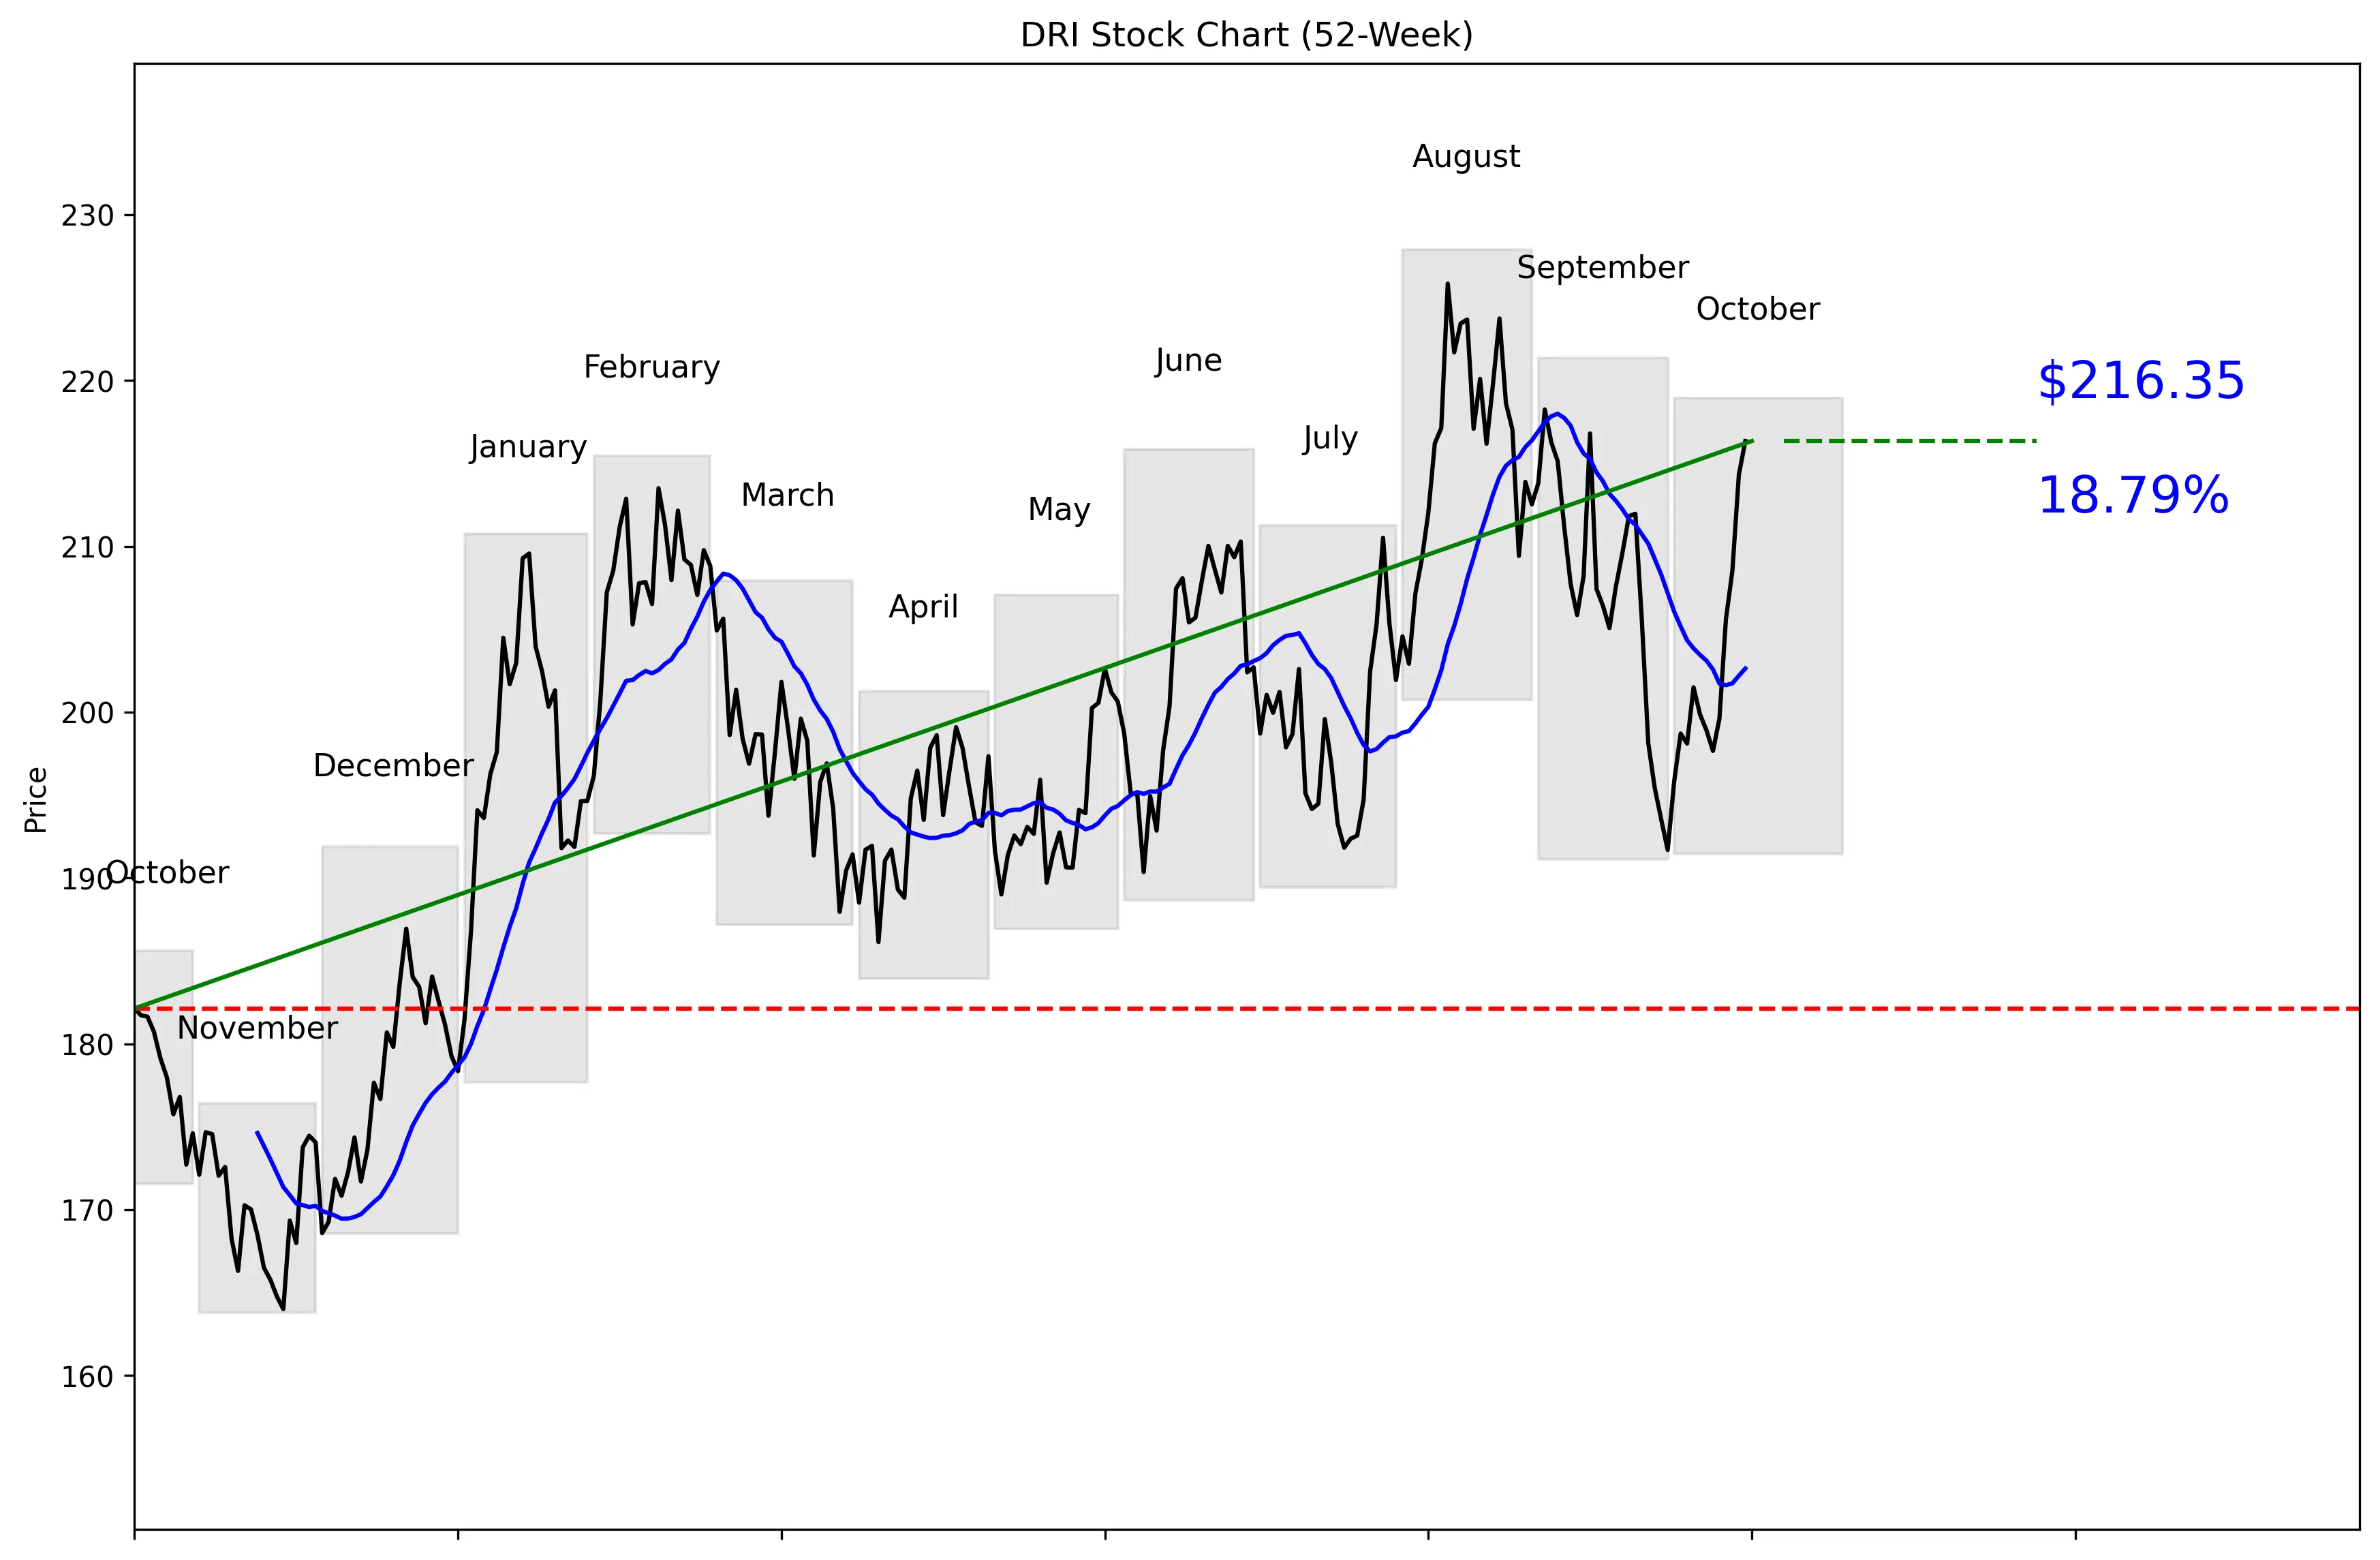
DRI 52-Week Stock Chart
Technical Analysis
DRI trades at $216.06, placing it 82% of the way from its $163.80 52-week low to its $227.90 high. The stock is 5.07% below that high and 32.08% above the low. Price sits 6.77% above its 20-day moving average of $202.63, while momentum is 9.46% over five trading days and 4.22% over 20 days. Near-term support is $191.69, and the immediate resistance level is $216.80. The trend is bullish, but DRI is now pressing resistance after a sharp five-session run.


Recent News and Developments

Darden extends 72 Olive Garden and LongHorn leases

Darden extended all 66 Olive Garden and LongHorn leases due in October 2027 and exercised early extensions on six leases due in October 2028. The leases run approximately five additional years with 1.5% annual rent increases and no landlord concessions or capital contributions. Source: Business Wire

Citi keeps Buy rating and $247 target

Citi reiterated its Buy rating on Darden on October 14 with a $247 price target. This was a reaffirmation, not an upgrade. Source: TipRanks

Bernstein reiterates Buy with $230 target

Bernstein reiterated its Buy rating on Darden on October 13 with a $230 price target. The call was also a reaffirmation rather than a new upgrade. Source: TipRanks


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $13.37 billion and growing 5.1%, giving Darden a solid operating base with continued top-line expansion. The analyst consensus is buy across 25 analysts, with an average target of $233.44 versus the current $216.06 price. Citi reiterated a Buy rating and $247 target on October 14, while Bernstein reiterated Buy with a $230 target on October 13. DRI gained 9.5% across five sessions, climbing from $197.66 on October 9 to $216.35 on October 16. Darden also extended all 66 Olive Garden and LongHorn leases due in October 2027 and exercised early extensions on six leases due in October 2028. The bullish case is straightforward: revenue is growing, price momentum is strong, and the average analyst target remains above the current share price.
Bear Case
DRI is not cheap at 20.98 times earnings. The stock already sits 82% of the way through its 52-week range and only 5.07% below its $227.90 high. It is also 6.77% above its 20-day moving average after gaining 9.46% in five trading days, increasing the risk of a near-term pullback. The balance sheet carries $8.59 billion in total debt against only $220.50 million in cash. The extended restaurant leases include 1.5% annual rent increases and no landlord concessions or capital contributions. Analyst expectations also vary widely, with targets ranging from $163.00 to $276.00. At $216.06, buyers are paying a full valuation while accepting substantial debt and limited distance from the recent high.
What to Watch
The first technical test is whether DRI can break and hold above the $216.80 30-day high. Failure at that level would put the $202.63 20-day moving average back in focus, followed by the $191.69 30-day low. Investors should monitor whether the recent 9.46% five-day momentum persists or fades toward the weaker 4.22% 20-day reading. Revenue growth needs to remain near or above the reported 5.1% to support a 20.98 P/E ratio. Watch whether analyst targets remain above the $216.06 share price, particularly Citi’s $247 target and Bernstein’s $230 target. The next quarter should also clarify whether the lease extensions, including 1.5% annual rent increases and no landlord contributions, pressure the risk-reward case. A move toward the $233.44 consensus target would support the bull case, while a decline toward the $163.00 low-end target would signal a major reassessment.
Analyst Consensus
BUY

Based on 25 analyst opinions
Low Target
$163.00
Mean Target
$233.44
High Target
$276.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Restaurants
Employees
209,931
Earnings & Dividends
Next Earnings
Dec 18, 2026
EPS (Trailing)
$10.30
Dividend Yield
302.0%
Payout Ratio
59.4%

Frequently Asked Questions

Is DRI a good stock to buy?
The recommendation is buy based on 25 analysts, and revenue is growing 5.1%. The takeaway is that Wall Street is bullish, but the stock is already near the upper end of its 52-week range.
What is DRI’s price target?
The average analyst target is $233.44, with estimates ranging from $163.00 to $276.00. The takeaway is that the consensus target sits above the current $216.06 price, but analyst expectations vary widely.
Is DRI stock overvalued?
DRI trades at a P/E ratio of 20.98 and sits 82% of the way from its $163.80 52-week low to its $227.90 high. The takeaway is that the stock carries a substantial valuation and is trading near the top of its range.
What are DRI’s support and resistance levels?
Near-term support is the 30-day low of $191.69, while near-term resistance is the 30-day high of $216.80. The takeaway is that DRI is currently trading just below resistance at $216.06.
Does DRI pay a dividend?
The provided data does not include DRI’s dividend rate, yield, or payment history. The takeaway is that investors should verify current dividend information separately before making an income-focused decision.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 17, 2026.