ALTSTATION.IO

Bristol-Myers Squibb Company (BMY) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$62.09
Change
-1.48%
Market Cap
$126.91B
Avg Volume
11.2M

Company Overview

Bristol-Myers Squibb is a global biopharmaceutical manufacturer headquartered in Princeton, New Jersey, operating in the healthcare sector. Founded in 1887, the company develops, manufactures, and sells prescription drugs across oncology, hematology, immunology, cardiovascular, and neuroscience indications. Its commercial lineup includes high-volume therapies such as Opdivo, Eliquis, Revlimid, Orencia, and Yervoy. It sells these products worldwide directly to wholesalers, distributors, specialty pharmacies, retailers, hospitals, clinics, and government agencies.

BMY sits firmly as an established market leader in commercial pharma, backed by a massive global distribution network and deep footholds in oncology and cardiovascular care. Its main competitive edge is a broad portfolio of multi-indication therapies spanning solid tumors, hematology, and autoimmune conditions. The primary vulnerability is heavy exposure to mature blockbuster drugs like Revlimid and Eliquis, which face ongoing patent erosion and generic competition. Defending market share requires BMY to maximize line extensions like subcutaneous Opdivo Qvantig while pushing newer specialty treatments into clinical practice.

The company is currently executing a strategic transition, redirecting its focus from legacy cash cows into newer commercial launches. Growth now hinges on recent additions like Cobenfy for schizophrenia, Camzyos for obstructive HCM, Sotyktu for plaque psoriasis, and targeted oncology assets like Krazati and Augtyro. Strategic dealmaking remains central to this effort, highlighted by an active collaboration with Arcus Biosciences to develop tumor-control regimens for kidney cancer. BMY has the pipeline depth to manage the shift, but commercial execution on these newer neuroscience and oncology therapies must accelerate to offset mature drug declines.

Key Financials
Market Cap
$126.91B
Revenue
$50.03B
EBITDA
$18.24B
Gross Margin
70.5%
Profit Margin
18.5%
Revenue Growth
6.9%
Total Cash
$12.58B
Total Debt
$44.81B
Free Cash Flow
$6.36B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
13.77
Forward P/E
9.33
Beta
0.19
52-Week High
$68.64
52-Week Low
$45.27
EPS
$4.51
50-Day Avg
$62.72
200-Day Avg
$59.98
Price/Book
5.42
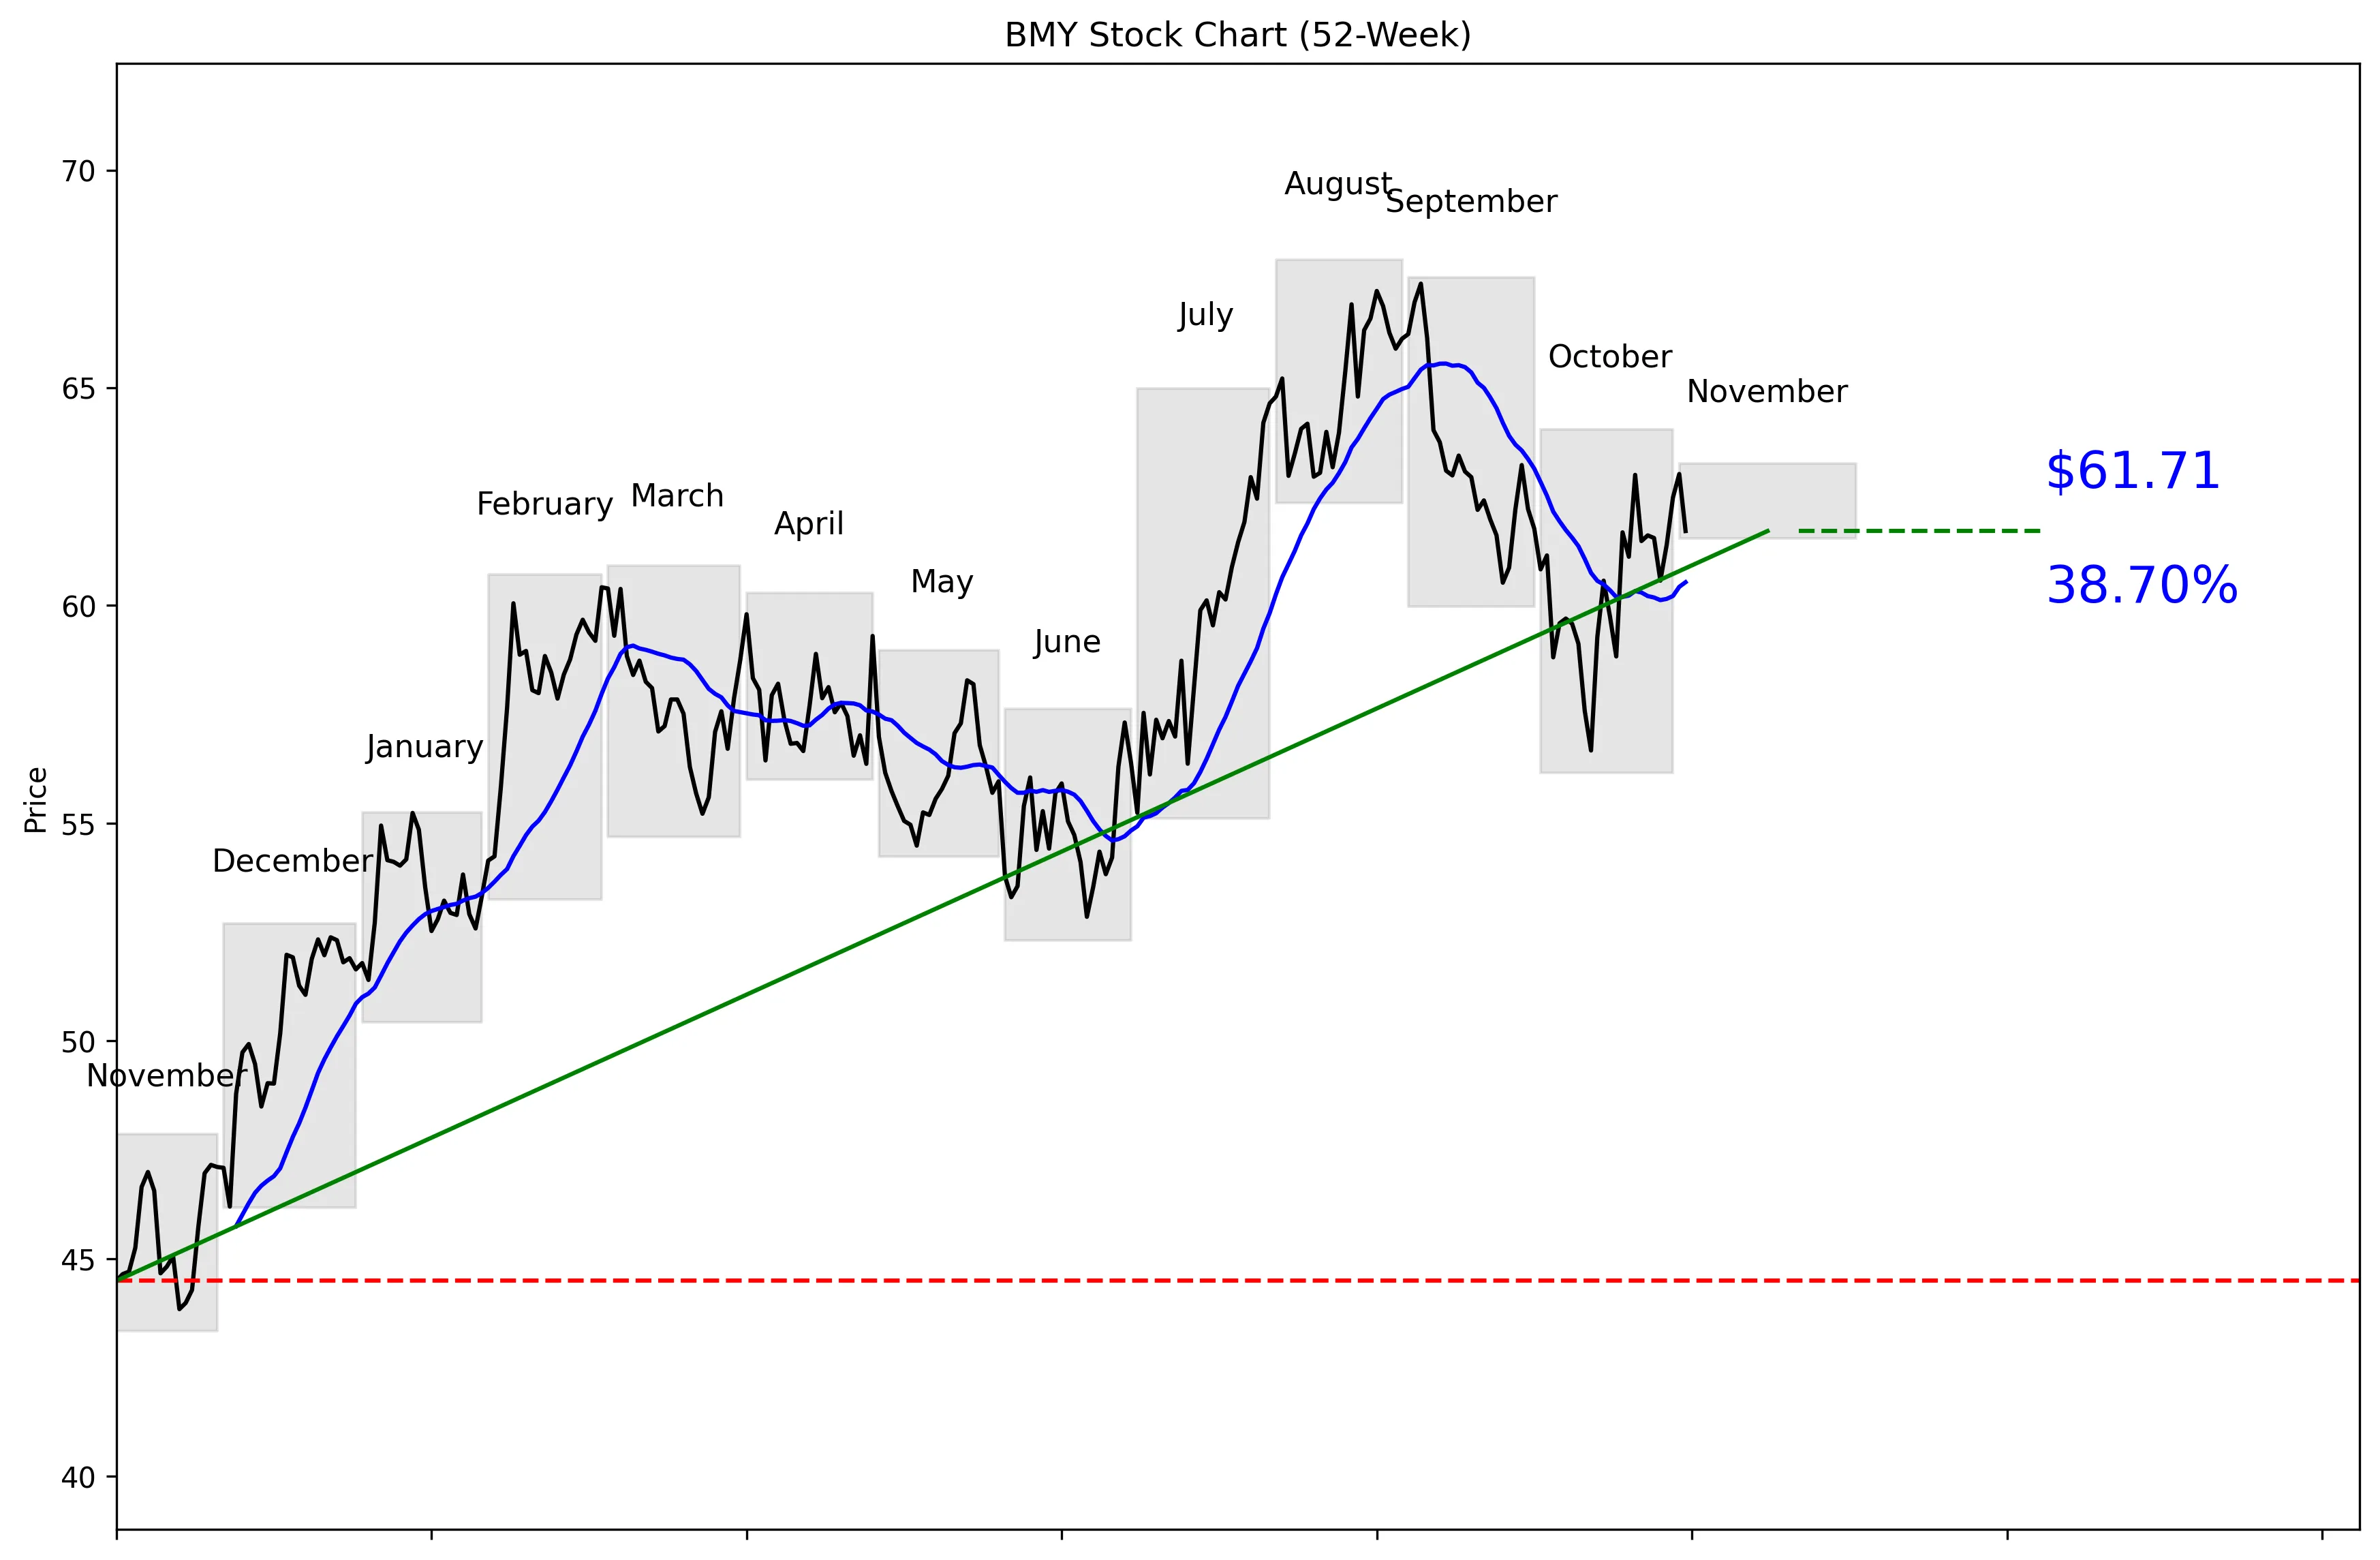
BMY 52-Week Stock Chart
Technical Analysis
BMY trades at $62.09, 75% of the way from its exact 52-week low of $43.34 to its exact 52-week high of $67.94. The stock is 9.17% below that high and 42.38% above the low. Price sits 1.94% above the 20-day moving average of $60.53, while momentum is positive at 0.26% over five trading days and 3.56% over 20 trading days. Near-term support is the 30-day low of $56.67. Near-term resistance is the 30-day high of $63.23, just $1.14 above the current price.


Recent News and Developments

Bristol Myers beats Q3 estimates and lifts revenue outlook

Third-quarter revenue rose 7% to $13.1 billion, beating the $12.75 billion analyst estimate. Adjusted earnings reached $1.35 per share, 21 cents above expectations, while full-year revenue guidance increased to $49.75 billion to $50.25 billion. Source: Reuters

Acquisition charge forces Bristol Myers to cut profit guidance

Bristol Myers lowered its 2026 adjusted earnings forecast to $6.35-$6.55 per share from $6.75-$7.00 after recording a 58-cent quarterly charge. The reduced profit outlook takes some shine off the revenue beat. Source: Reuters

BMY gains 2.2% after earnings beat

Bristol Myers shares rose 2.2% to $61.94 in premarket trading on October 29 after the company beat third-quarter expectations and raised its annual revenue forecast. The move shows investors prioritized stronger sales over the reduced earnings outlook. Source: Reuters


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth is 6.9%, and third-quarter revenue climbed 7% to $13.1 billion. That result beat the $12.75 billion analyst estimate by $350 million. Adjusted earnings of $1.35 per share beat expectations by $0.21. Management also raised full-year revenue guidance to between $49.75 billion and $50.25 billion. At $62.09, BMY trades at 13.77 times earnings and remains below the $65.25 consensus analyst target. The buy case is straightforward: improving sales, an earnings beat, a higher revenue outlook, and a valuation that does not require aggressive growth assumptions.
Bear Case
Bristol Myers cut its 2026 adjusted earnings forecast from $6.75-$7.00 per share to $6.35-$6.55 after recording a $0.58 quarterly acquisition charge. That reduction matters because stronger revenue is not translating cleanly into the previous profit outlook. Debt is $44.81 billion against $12.58 billion in cash, leaving debt $32.23 billion above cash. The stock is already 42.38% above its exact 52-week low and sits 75% of the way through its exact annual range, so much of the recovery has already happened. Analyst conviction is also mixed: Morgan Stanley maintained Underweight with a $40 target, while Wells Fargo and Scotiabank held at $60. The broad analyst target range of $40 to $80 shows serious disagreement about BMY’s value, and the $40 low represents substantial downside from $62.09.
What to Watch
The next quarterly revenue result needs to confirm that the recent 7% growth rate was sustainable. Investors should compare future revenue against the raised full-year guidance range of $49.75 billion to $50.25 billion. Profit execution is the bigger test after 2026 adjusted earnings guidance fell to $6.35-$6.55 per share. Another acquisition-related charge would make the $44.81 billion debt load harder to ignore, especially with only $12.58 billion in cash. On the chart, a move above $63.23 would clear the 30-day high, while a drop below the $60.53 moving average would weaken the current positive trend. A break below $56.67 would damage the near-term setup, while progress toward the $65.25 consensus target would show that investors remain focused on revenue growth rather than the reduced profit forecast.
Analyst Consensus
BUY

Based on 24 analyst opinions
Low Target
$40.00
Mean Target
$65.25
High Target
$80.00


Earnings and Financial Data

Sector
Healthcare
Industry
Drug Manufacturers – General
Employees
32,500
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$4.51
Dividend Yield
400.0%
Payout Ratio
55.9%

Frequently Asked Questions

Is BMY a good stock to buy?
The analyst recommendation is buy based on 24 analysts, and BMY has 6.9% revenue growth with a P/E of 13.77. The clear takeaway is that the available data supports a buy case, but the analyst view is not unanimous.
What is BMY’s price target?
The consensus analyst target is $65.25, with estimates ranging from $40.00 to $80.00. The clear takeaway is that the average target is above the current $62.09 price, but the range shows wide disagreement.
Is BMY stock overvalued?
BMY trades at a P/E of 13.77 and sits 75% of the way from its exact 52-week low of $43.34 to its exact high of $67.94. The clear takeaway is that the stock is well above its low, but the provided data does not establish that it is overvalued.
What are BMY’s support and resistance levels?
Near-term support is $56.67, the 30-day low, and near-term resistance is $63.23, the 30-day high. The clear takeaway is that BMY is trading close to resistance at its current price of $62.09.
Does BMY pay a dividend?
The provided key and technical data do not include dividend information. The clear takeaway is that no dividend conclusion can be made from the supplied data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.